Mangal Electrical Industries' standalone net profit fell 17.5% YoY to ₹10.97 Cr in Q2 FY27 (from ₹13.30 Cr a year ago), even as revenue from operations grew 9.2% YoY to ₹168.58 Cr (from ₹154.33 Cr) — topline growth that didn't translate to the bottom line. Operating margin (segment EBITDA/revenue) compressed to 9.15% from 14.15% YoY, and net margin fell to 6.43% from 8.55%. There are no exceptional items in either period, so the decline is entirely operational, not accounting-driven.
The compression traces to the EPC Contract segment, which the company's own segment report shows swinging from a ₹2.51 Cr profit a year ago to a ₹1.15 Cr loss this quarter, on revenue that collapsed 55.7% YoY to ₹5.33 Cr. The core Manufacturing & Trading business (electrical transformers, CRGO, and related accessories) held up, growing revenue 14.7% YoY to ₹163.25 Cr, but its own segment profit also eased to ₹16.58 Cr from ₹19.33 Cr YoY, pointing to some margin pressure even in the core business and not just a one-off EPC drag.
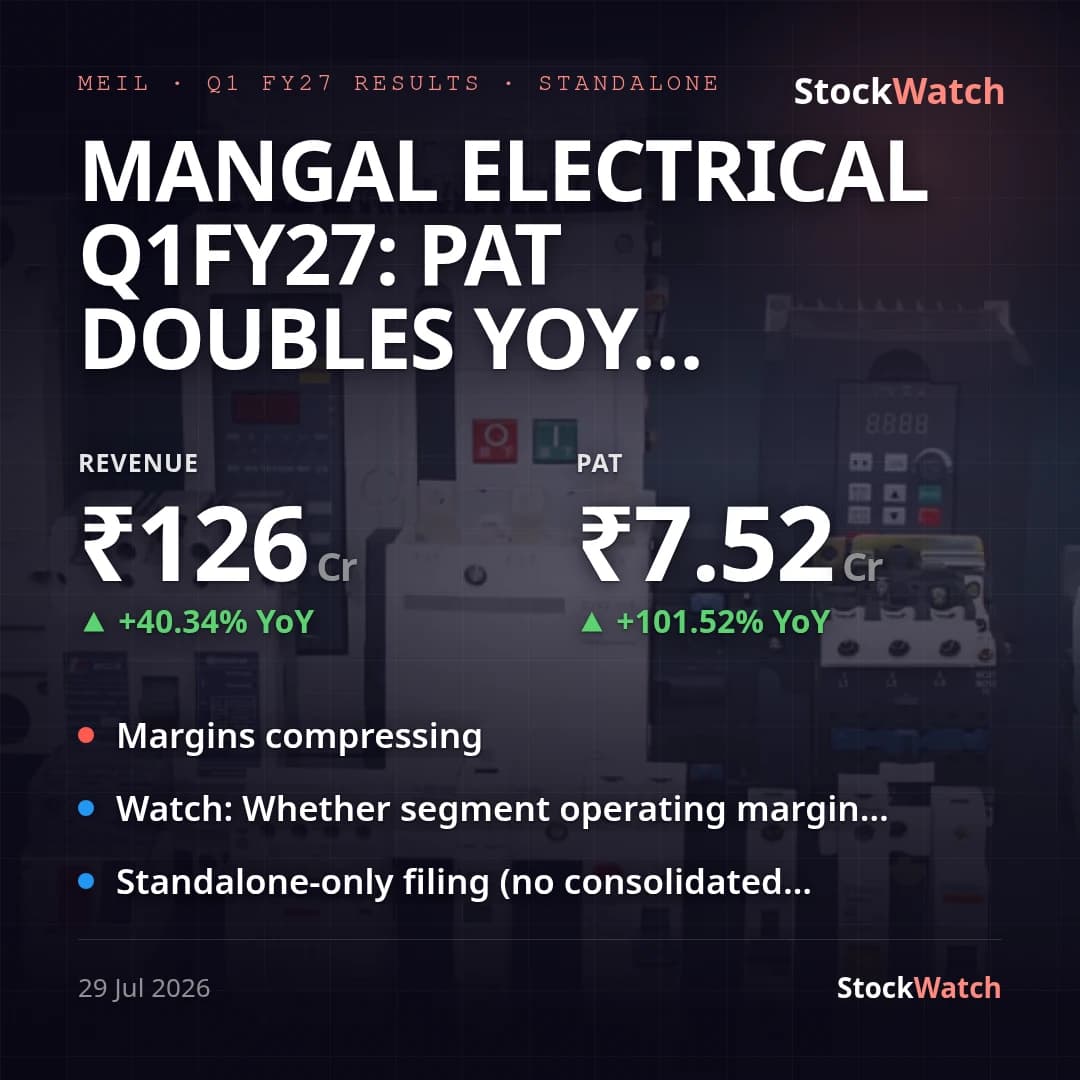
Sequentially, both revenue (+34.0%) and PAT (+45.9%) rose sharply from Q1 FY27 (₹125.83 Cr revenue, ₹7.52 Cr PAT), but Q1 was a seasonally soft base for this company, so the QoQ jump should not be read as a turnaround — the YoY comparison, where profit declined, is the more telling one. There is no formal management guidance or prior concall commentary on record to grade this print against, and no management press release was available at extraction time, so there is no company framing to reconcile against the numbers. The stock carries no formal analyst coverage per available searches (a function of its August 2025 listing), so there is no street consensus to compare against either — vsStreet is marked unknown rather than inferred. The quarter's other disclosures — CFO Rohit Pokharna's appointment (Sept 16, 2026), a director's resignation (Sept 18, 2026), and the COO's designation as Senior Management Personnel effective today — are governance/personnel items with no direct read-through to this quarter's P&L.