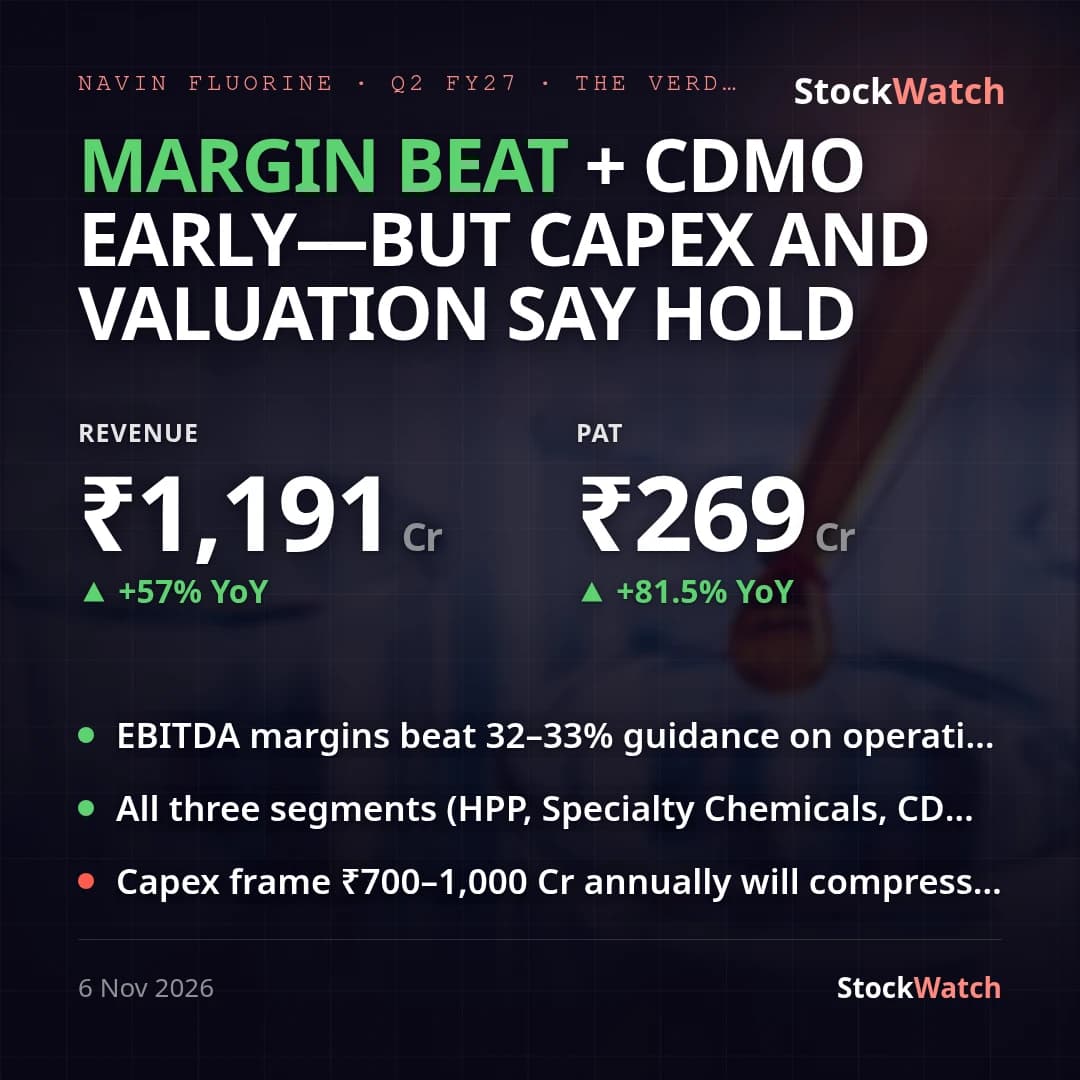
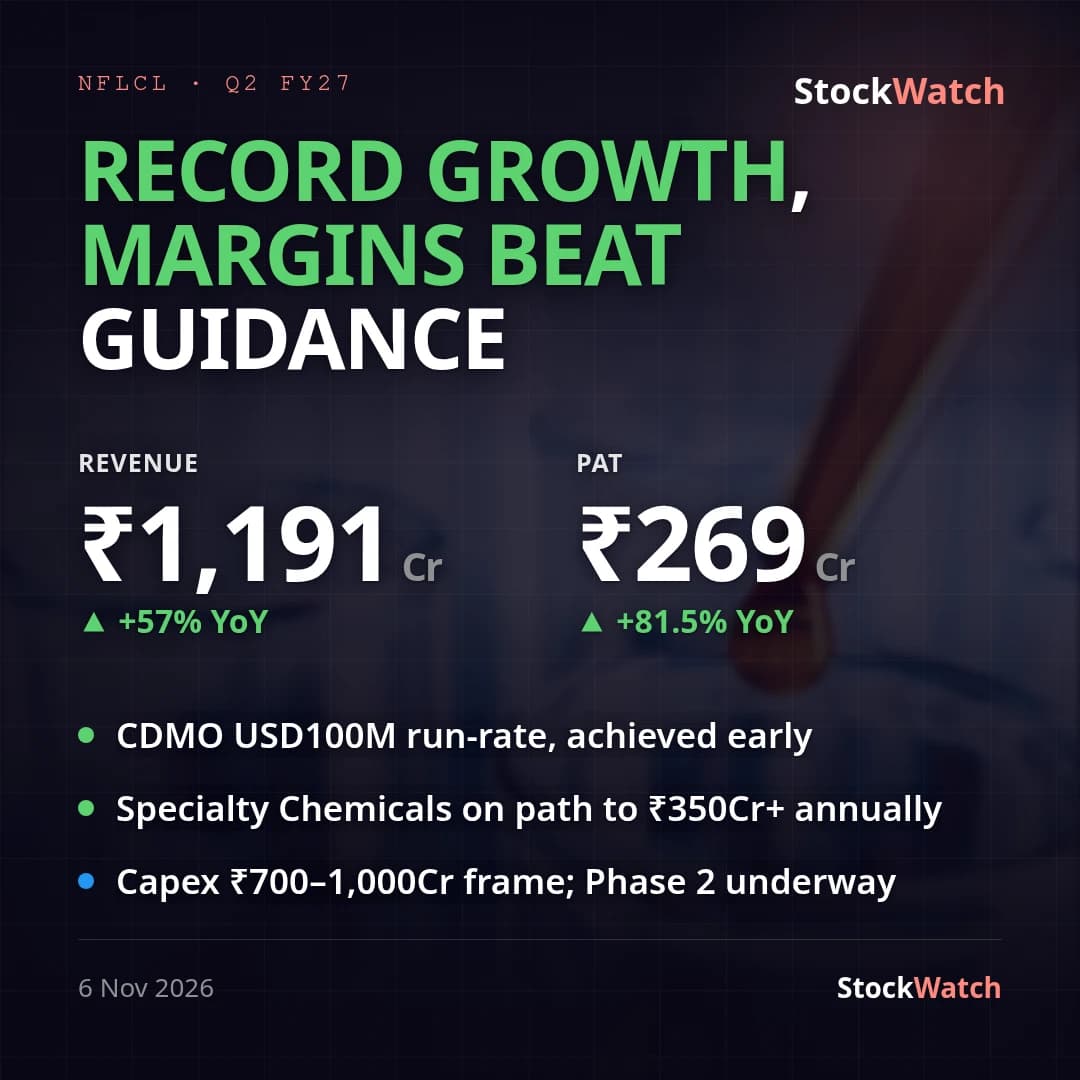
Navin Fluorine Q2 FY27: consolidated PAT up 81% YoY to ₹269 Cr, margins top guidance
Navin Fluorine's consolidated revenue for Q2 FY27 (quarter ended September 30, 2026) came in at ₹1,190.74 Cr, up 57.0% YoY from ₹758.42 Cr and up 13.9% QoQ from ₹1,045.08 Cr. Consolidated PAT was ₹269.24 Cr, up 81.4% YoY from ₹148.37 Cr and up 10.7% QoQ from ₹243.31 Cr — profit growth continued to outrun revenue growth YoY, extending the pattern from Q1 FY27 (PAT +107.7% YoY). Basic EPS was ₹52.48 against ₹29.06 a year earlier. No exceptional items were recorded in either the current or year-ago quarter, so the growth is unadjusted/clean; the only one-off in the trailing record is a ₹6.75 Cr consolidated labour-code provision booked for the FY26 full year, outside both compared quarters.
OPM (EBITDA/revenue from operations) expanded to 34.2% from 32.46% a year ago, and held essentially flat against Q1 FY27's 34.17% — sitting at or just above the top of management's own FY27 guided band of "normalized EBITDA margins 32-33% ±1%" set out on the August 2026 Q1 concall, meaning the quarter met to slightly beat that outlook. NPM was 22.3%, up sharply from 19.1% YoY but down marginally from 22.5% in Q1, as other income normalized to ₹15.6 Cr from ₹35.1 Cr in Q1. Standalone PAT was ₹204.57 Cr on standalone revenue of ₹737.26 Cr; the gap to consolidated PAT of ₹269.24 Cr (roughly ₹65 Cr, about a quarter of group profit) reflects contribution from the foreign subsidiaries and the CDMO/Advanced Sciences units the company has been directing capex toward.
No separate management press release accompanied this filing beyond the regulatory board-outcome letter, so framing claims could not be cross-checked against company commentary; the relevant benchmark remains the FY27 margin band and CDMO targets from the Q1 concall, against which this quarter's 34.2% OPM is tracking at the top end. Public searches turned up no specific sell-side consensus estimate published for this exact quarter, so vsStreet is marked unknown rather than inferred — contemporaneous coverage had noted Q1 FY27 results "crushed Street estimates," and this quarter's growth cadence (revenue +57%, PAT +81% YoY) is broadly consistent with that trajectory continuing. The quarter also carried several corporate developments tying into the print: the board declared an ₹8/share interim dividend (400% of face value, record date November 5, 2026); the Honeywell HFC supply contract was extended to $590 Mn on October 29; and a subsidiary commissioned MPP debottlenecking capacity on September 29.
Going into Q3 FY27, the markers to watch are whether the 34%+ OPM holds as the HFC/MPP/Chemours capex base scales further — management's own guided ceiling is 34%, so any further expansion would exceed its stated range — progress on the CDMO 3x asset-turn-by-FY29 target and the 3-4 FDA readouts flagged for the next 8-12 months, and whether other income normalizes further from this quarter's ₹15.6 Cr as NPM settles.