Niva Bupa Q1: PAT ₹138 Cr, near-doubles YoY on Ind AS basis; combined ratio to 93.6%
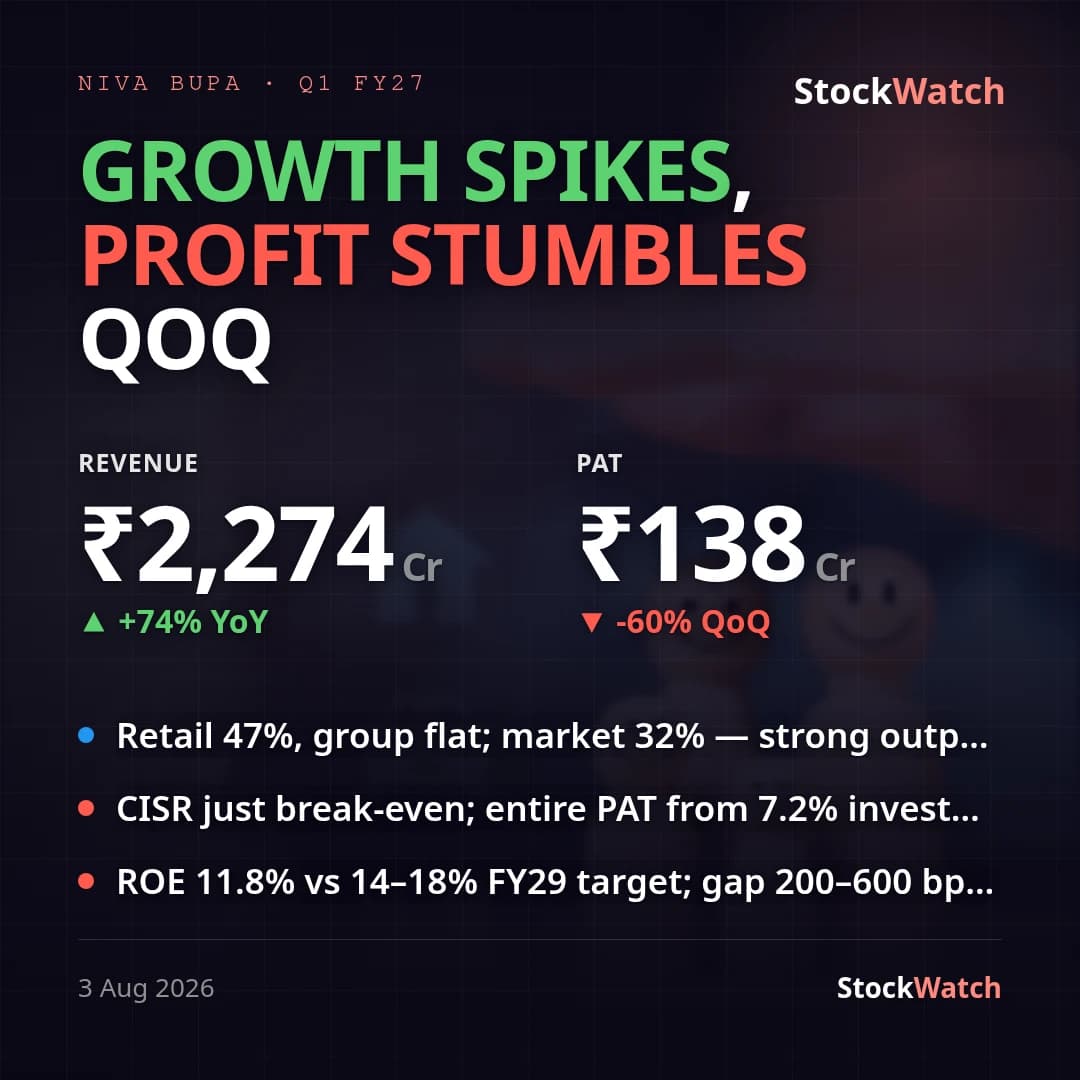
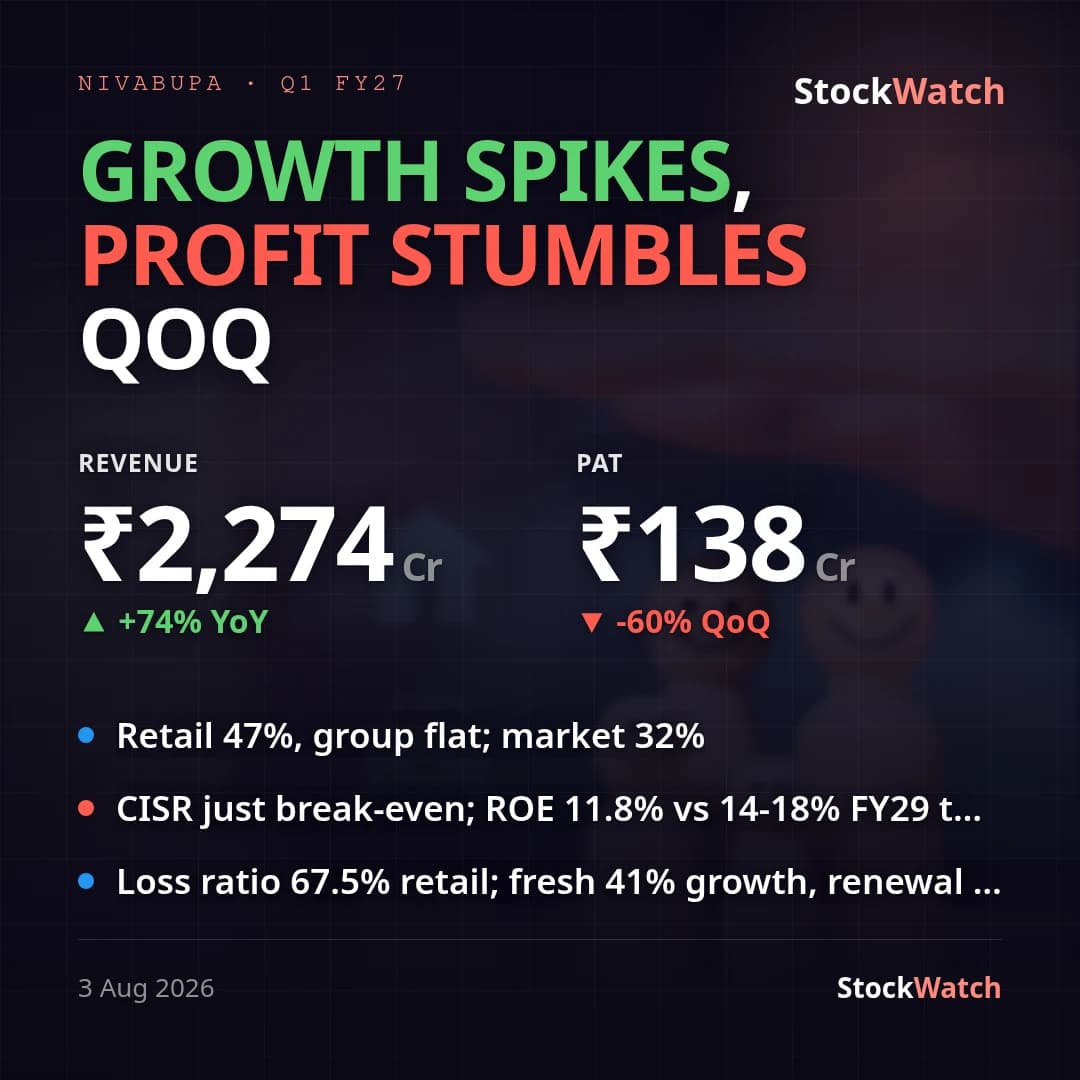
Niva Bupa reported its first quarter under Ind AS 117 (adopted 1-Apr-2026), and on the filing's own restated comparatives the print is strong: standalone PAT of ₹137.80 Cr rose ~93% from ₹71.44 Cr a year ago, while insurance revenue grew 28.6% YoY to ₹2,273.72 Cr and gross written premium climbed 31.7% YoY to ₹2,149.96 Cr. A word on the base: our records carry the year-ago quarter as a ₹91.44 Cr loss under the old GAAP, so on a headline basis this reads like a turnaround — but the company has restated Q1FY26 to a ₹71.44 Cr Ind AS profit, and the honest comparison is growth-on-growth, not loss-to-profit. There are no exceptional items on either side, so reported and underlying growth are the same.
The quality of the quarter is in the ratios. The combined operating ratio improved to 93.55% from 98.50% a year ago, driven by a lower claims ratio (63.01% vs 66.83%) and a leaner expense ratio (30.54% vs 31.67%) — i.e. both the loss and cost sides moved the right way, lifting net insurance margin to 4.44% from 0.43%. Return on equity rose to 3.71% from 2.11%. Sequentially, though, the print softened: PAT fell 13.5% from Q4FY26's ₹159.36 Cr, margin slipped from 5.26%, and the expense ratio ticked up from 29.66% — a normal give-back after a seasonally heavy March quarter, not a trend break.
Against management's own framing, the quarter tracks well ahead of plan: on the last concall the board guided to a ~99% long-term combined ratio by FY2029 and mid-to-high-teens ROE off operating leverage and expense efficiency, and at 93.55% the combined ratio is already inside that target with the claims ratio broadly stable, exactly as guided. On the Street, brokerages have modelled ~15-20% PAT growth for FY27 (supporting a ₹96 target) with no specific Q1 consensus on record; the ~93% restated YoY jump flatters against that full-year bar and is not a clean read given the Ind AS transition, so we mark the print vs Street as unknown rather than a beat.
Alongside results the board approved raising up to ₹500 Cr via NCDs on private placement — notable because the solvency ratio eased to 2.25x from 2.86x a year ago (and 2.49x in Q4), so the debt raise reads as capital reinforcement to support the 30%+ premium growth rather than expansion for its own sake. A ₹22.12 Cr tax refund order (Jul 15) and no unresolved investor complaints round out an otherwise clean quarter.