StockWatch
·

Orkla India Ltd

BSE: 544595

P/L Snapshot

Q1 FY27 · standalone

vs Q4 FY26
Revenue
661.60
+5.0%
Expenditure
547.10
+3.0%
Net Profit
86.38
+17.7%
OPM %
17.47%
+1.88pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00185.25370.50555.75740.99Q2 FY26Q3 FY26Q4 FY26Q1 FY27
Price Chart
Reports

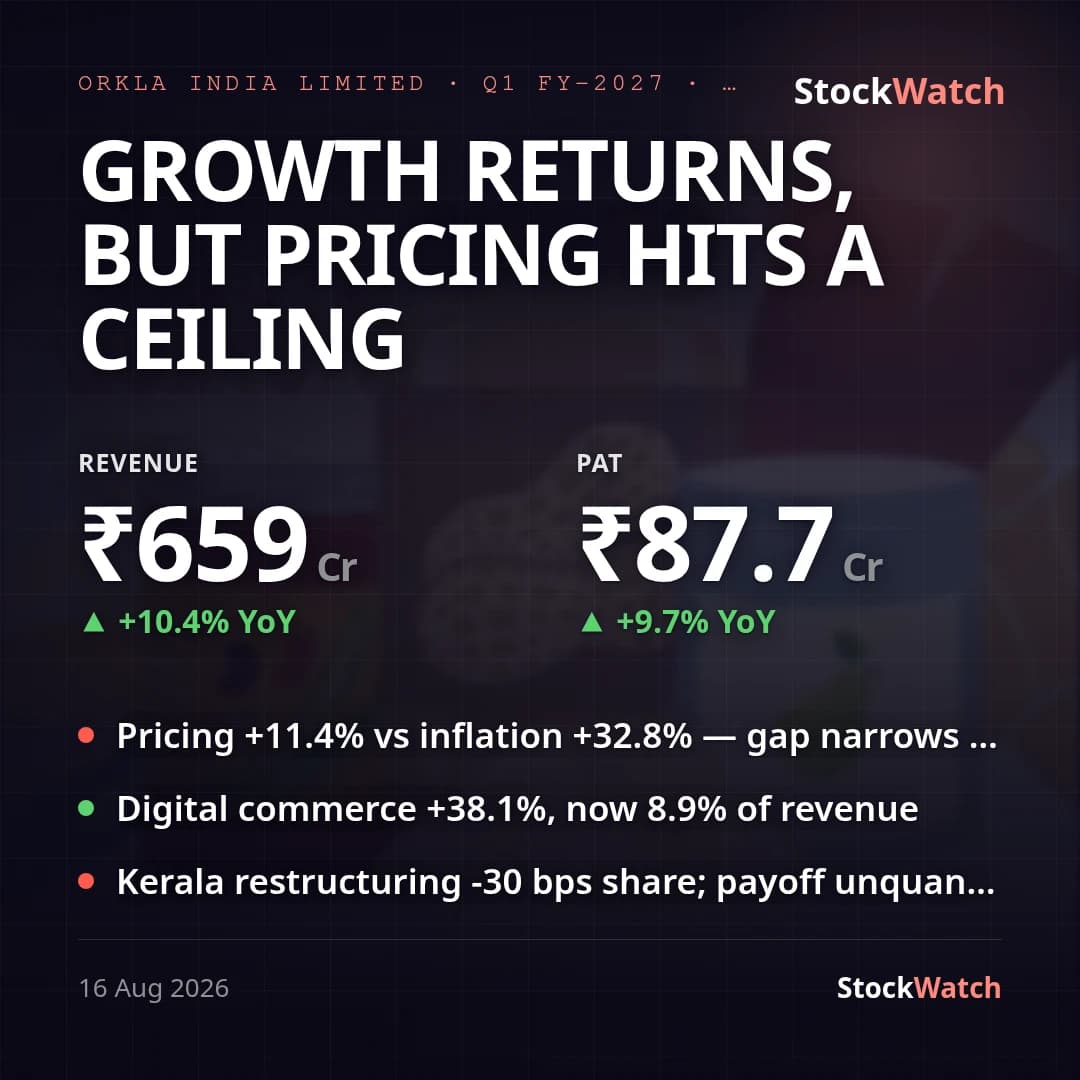
Growth Returns, but Pricing Hits a Ceiling

pricing power · volume elasticity · commodity inflation
Result verdictFollow-upQ1 FY2716 Aug 20266 minFMCG

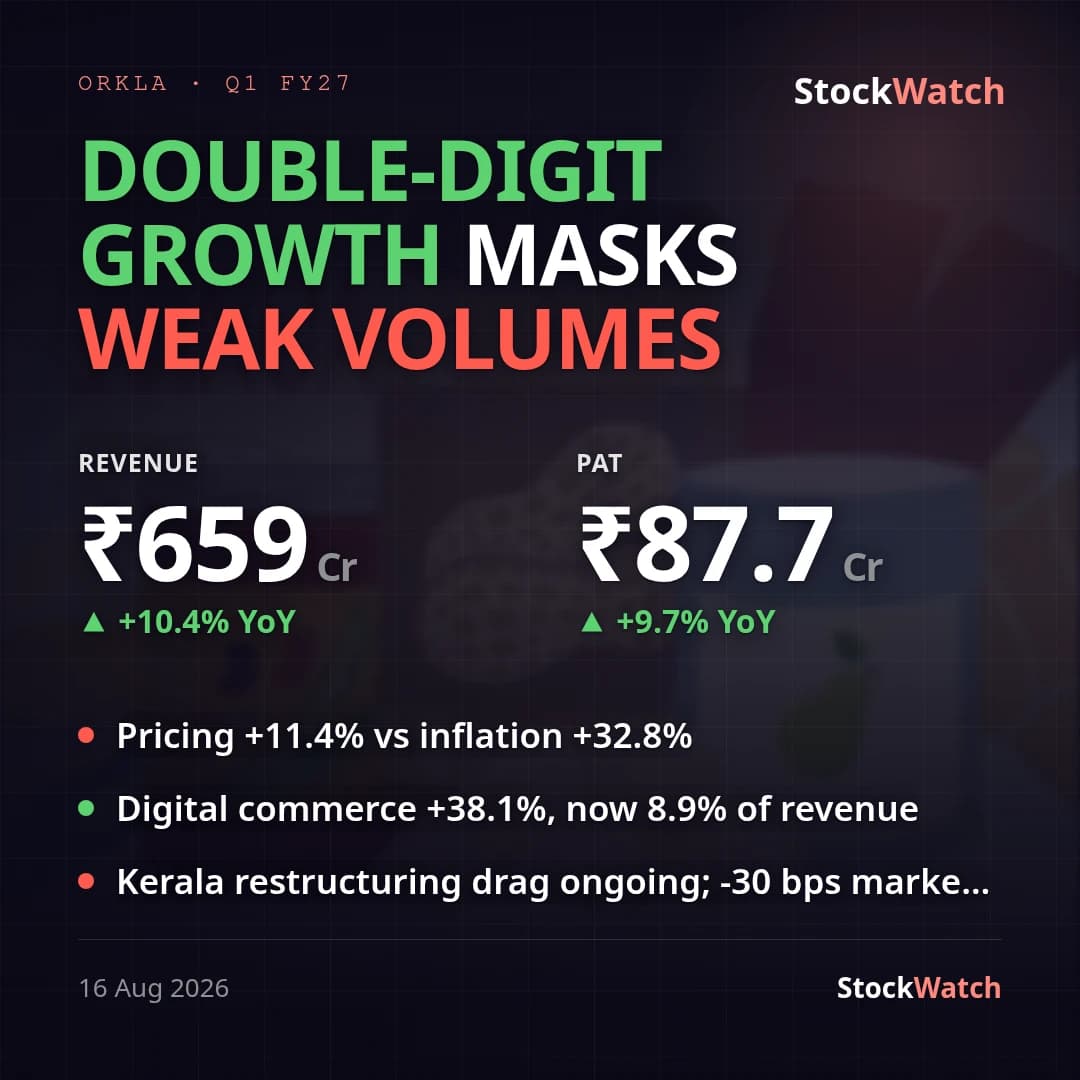
Double-digit growth returns, but volume weak amid inflation headwinds

pricing power · commodity inflation · volume elasticity
TranscriptDeep diveQ1 FY2716 Aug 20266 minFMCG

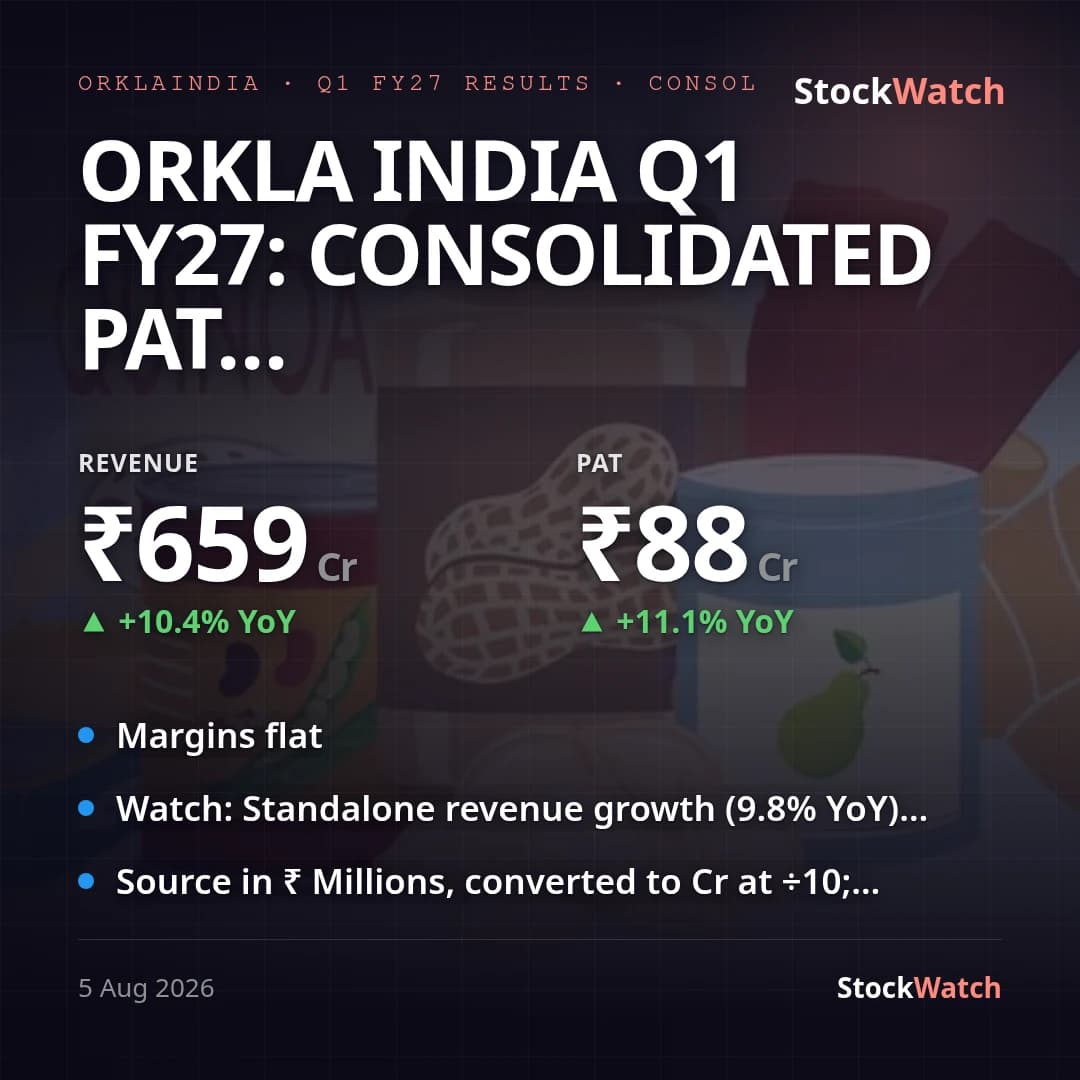
Orkla India Q1 FY27: consolidated PAT +11% YoY to ₹87.7 Cr, revenue +10.4% to ₹659 Cr

fmcg · food products · margin flat yoy

ResultsQ1 FY2705 Aug 20263 minFMCG
Latest
Board Meeting4 Aug, 4:10 pm

Orkla India Q1 FY27: consolidated PAT +11% YoY to ₹87.7 Cr, revenue +10.4% to ₹659 Cr

Orkla India's consolidated (primary) PAT for the quarter ended June 30, 2026 came in at ₹87.7 Cr, up 11.1% YoY, on revenue of ₹659.1 Cr, up 10.4% YoY — this print achieves the "return to double-digit revenue growth" management guided to on the Q4 FY26 call. Standalone, the secondary basis, told a near-identical story: PAT ₹86.4 Cr (+11.3% YoY) on revenue ₹644.2 Cr (+9.8% YoY), just shy of double digits but not materially divergent from the consolidated read. The quarter carried a ₹1.5 Cr exceptional gain — a write-back of the gratuity provision booked earlier under the new Labour Codes — versus zero exceptional items in the year-ago quarter. Adjusting for this one-off, consolidated PAT growth was closer to ~9.7% YoY versus the 11.1% reported. Core operating margin (profit before exceptional items and tax, as a % of total income) was 17.1% versus 17.5% a year ago — essentially flat YoY despite the sequential jump from 15.4% in Q4 FY26 — and net margin was similarly flat YoY at 13.0% versus 13.0% (up from 11.5% QoQ). The QoQ margin and PAT improvement (PAT +19.4% QoQ) mostly reflects a seasonal step-up off a softer March quarter rather than a structural gain, since the YoY comparison is flat. No pre-result street estimates for this print turned up in a web search, so vsStreet is marked unknown rather than inferred. Against management's own prior guidance — double-digit revenue growth aided by calibrated pricing and volume expansion, with Kerala distribution restructuring flagged as a near-term headwind — the quarter is a clean "met," with consolidated revenue growth landing at 10.4%. Management's press release cites "11.5% revenue growth" and "broad-based momentum across categories, channels and geographies"; that figure runs slightly above the 10.4% headline in the filed statement, a gap this filing does not itself reconcile (likely a different growth base or like-for-like adjustment). Separately, on July 21, 2026 the company disclosed an ₹8.4 Cr GST show-cause notice — a post-quarter-end development not reflected in these Q1 numbers. Going into Q2 FY27, the flat YoY margin trend and the standalone/consolidated growth gap (9.8% vs 10.4%) are the threads to watch, alongside the Kerala distribution overhaul management flagged as an ongoing headwind and the outcome of the GST notice.

4 Aug 2026, 04:10 pm

Corporate Events

Board MeetingORKLAINDIA
2026
19Aug

Board Meeting

The 30th Annual General Meeting of the Company will be held …

BSE Filing ↗
Board MeetingORKLAINDIA
2026
4Aug

Board Meeting

The meeting of the Board of Directors is scheduled to be hel…

BSE Filing ↗