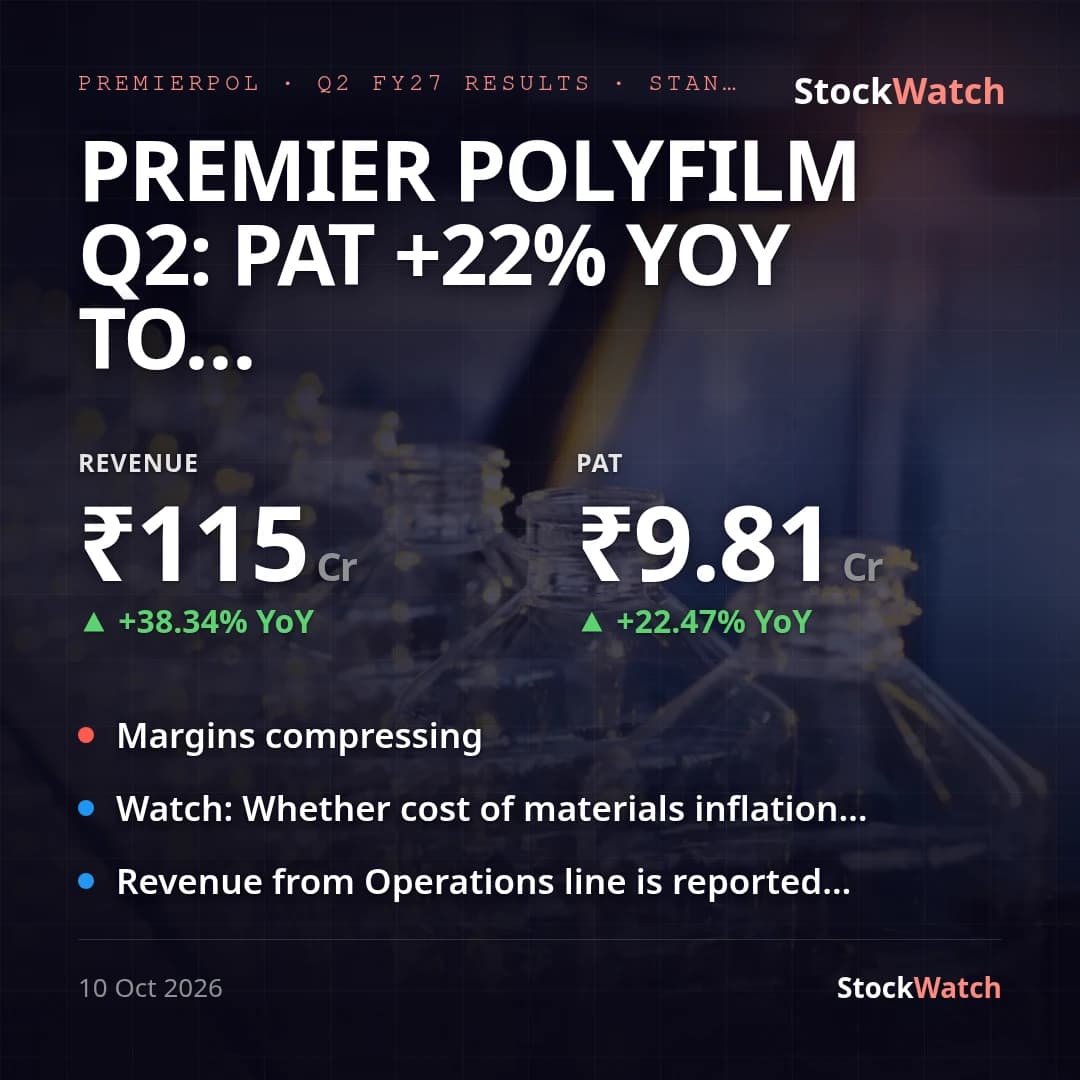
Premier Polyfilm Q2: PAT +22% YoY to ₹9.81 Cr, margins compress on costlier inputs
Premier Polyfilm's standalone revenue rose 38.3% YoY (and 15.0% QoQ) to ₹115.06 Cr, while standalone net profit grew a slower 22.5% YoY (8.0% QoQ) to ₹9.81 Cr, with basic EPS at ₹0.94 versus ₹0.76 a year ago and ₹0.87 last quarter. There were no exceptional items in either the current or year-ago quarter, so the reported and adjusted YoY PAT growth are the same ~22.5% — profit growth trailing revenue growth by a wide margin is the core story, not a one-off distortion. The company has no subsidiary, associate or joint venture, so standalone is the only basis available.
Net profit margin (on total income) fell to 8.44% from 9.52% a year ago and 9.02% last quarter — the second straight quarter of NPM compression. Cost of materials consumed, the largest expense line, rose 64.2% YoY to ₹68.43 Cr versus 38.3% revenue growth, roughly 26 percentage points faster than the topline and the clear source of the squeeze; purchases of stock-in-trade were flat YoY (₹2.17 Cr vs ₹2.15 Cr). The GST expensed through the P&L rose 29.5% YoY to ₹13.63 Cr, consistent with the gross-of-GST revenue presentation, while employee costs rose a more moderate 14.6% YoY to ₹8.88 Cr.
No analyst previews or consensus estimates for this quarter turned up in a web search (checked Tickertape, Motilal Oswal/MarketsMojo, Nirmal Bang, Equitymaster, IndMoney) — this is a micro-cap with no visible street coverage, so vsStreet is unknown rather than inferred. Our records also carry no prior concall commentary or formal management guidance, so vsGuidance is unknown as well — management gives no outlook on record to measure this print against. No management press release accompanying this filing had been extracted at the time of this analysis. Corporate developments this quarter are governance-related rather than operational: the AGM on 24-Sep-2026 approved management changes and appointed A D V AND CO. LLP as the new statutory auditor (replacing the prior auditor from Q3 FY27 reporting onward), the company issued a clarification on a trading-volume increase the same day, and promoter-linked Manvi Goenka sold 2,06,902 shares on 25-Sep-2026 — none of these directly explain the quarter's numbers but are concurrent disclosures worth flagging.
For the half year, standalone PAT is up 34.8% YoY to ₹18.89 Cr on revenue up 36.5% YoY to ₹215.12 Cr, the same revenue-ahead-of-profit pattern seen in the quarter. The next print is the one that will show whether the materials-cost inflation driving this compression eases or persists into H2 FY27.