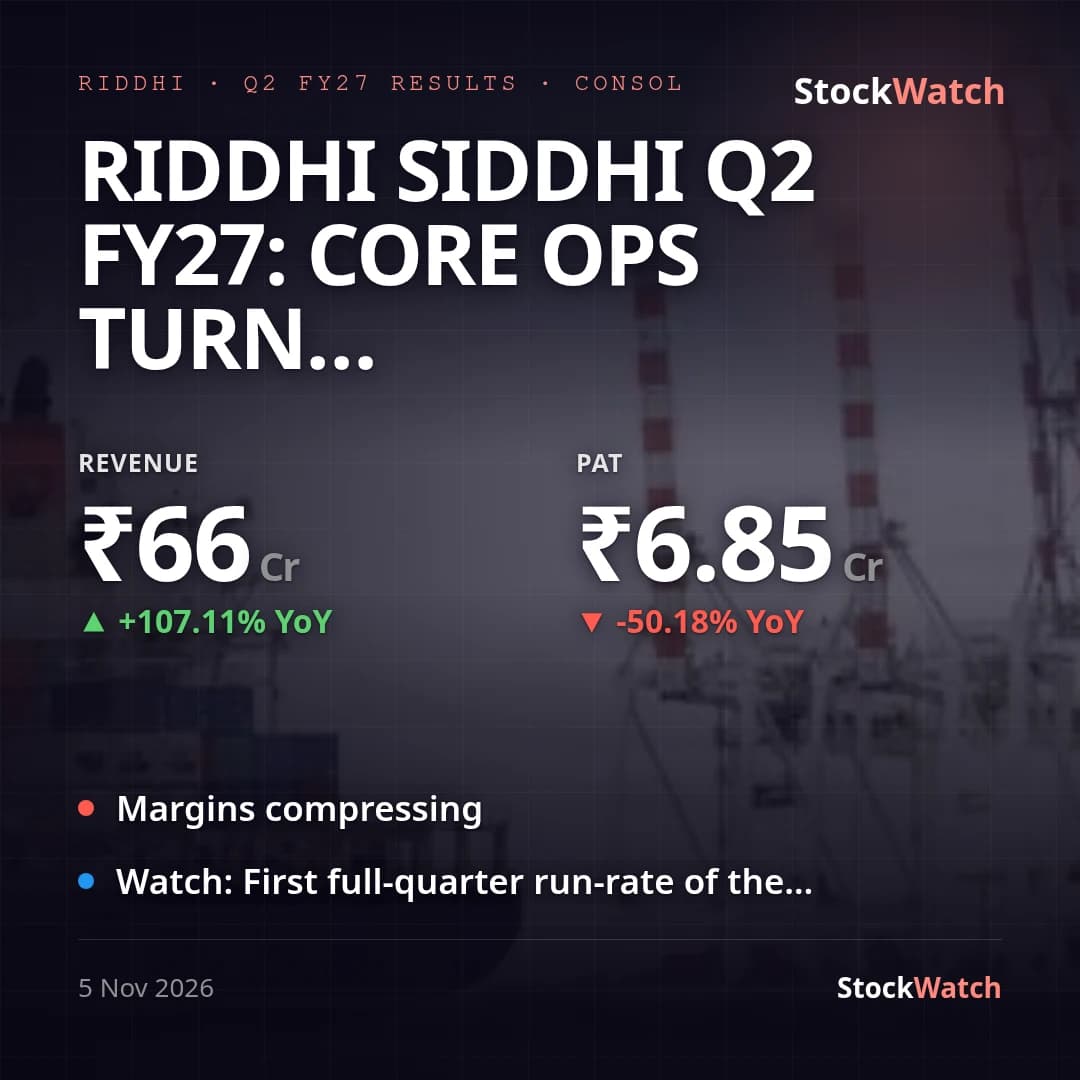
Riddhi Siddhi Q2 FY27: Core Ops Turn Profitable, but Consol PAT Falls 50% YoY to ₹6.85 Cr
On a consolidated basis (the primary lens here, given the gap with standalone below), Riddhi Siddhi Gluco Biols reported Q2 FY27 revenue of ₹66.49 Cr, up 107.1% YoY from ₹32.10 Cr but down 26.0% QoQ from ₹89.87 Cr, while PAT for the period was ₹6.85 Cr — down 50.2% YoY from ₹13.75 Cr but up 128.0% QoQ from ₹3.01 Cr. Standalone PAT, by contrast, came in far higher at ₹17.68 Cr, because the standalone entity excludes the subsidiary's discontinued paper-division loss (-₹1.32 Cr this quarter) and non-controlling interest; readers tracking standalone numbers elsewhere should not read the two as contradictory.
The YoY revenue surge is not organic: it is driven by the Trading segment (₹49.39 Cr vs ₹17.23 Cr YoY), which now includes the starch-division assets acquired from Cargill India under an APA completed April 27, 2026 — the company itself flags the two periods as "not directly comparable" on this count. Even so, core operating performance genuinely improved: the Trading segment swung from a ₹1.99 Cr loss to a ₹7.60 Cr profit YoY, and total segment EBIT nearly tripled to ₹13.93 Cr from ₹4.53 Cr, lifting operating margin to ~6.09% from ~4.84% YoY (margin expanding at the operating line). The reported bottom line fell YoY purely because "other un-allocable income" (treasury/investment income on the company's large surplus-funds portfolio) normalized to ₹1.75 Cr from an unusually elevated ₹17.10 Cr a year ago — a ₹15.35 Cr swing that swamps the operating gain. On that basis the adjusted, ex-treasury-income picture is a turnaround (core pre-tax profit moved from roughly a ₹0.60 Cr loss to an ₹8.40 Cr profit YoY), even as headline net margin compresses to 8.51% of total income from 25.36% YoY.
There is no street consensus to measure against — this is a micro-cap (paid-up capital ₹7.13 Cr) with no analyst previews or consensus estimates found for this quarter, and the company issues no formal guidance; our records and a web search both turn up none. Management gave no separate press-release commentary beyond the regulatory filing. The quarter's other corporate threads tie into the balance sheet rather than the P&L: the company completed a promoter OFS of 11.55% of equity (June 22-23, 2026) to meet SEBI's 25% minimum public shareholding norm, ending the SAT/Supreme-Court-ordered securities-market restraint (concluding December 23, 2026), and separately shifted its registered office to Haryana. A ₹3.08 Cr contingent tax liability from a CIT Appeals order remains under appeal at the ITAT and is unprovided for.
Going forward, the quarter sets up a cleaner read on the newly acquired starch business's run-rate contribution to Trading segment profit, and on whether the sharply lower treasury income this quarter is the new normal or another one-off swing.