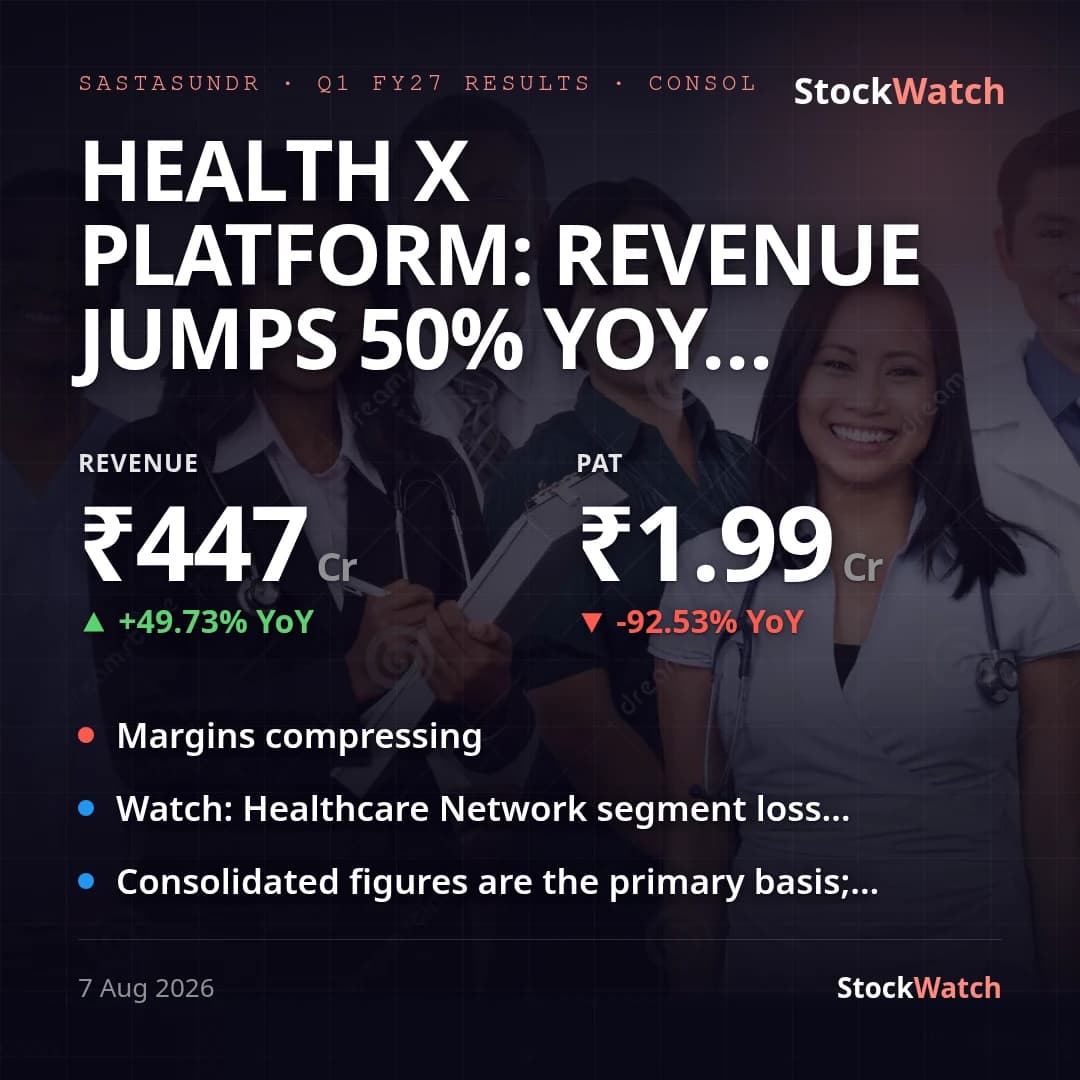
Health X Platform: revenue jumps 50% YoY but consolidated PAT crashes 93% to ₹2 Cr
Health X Platform (formerly Sastasundar Ventures) posted consolidated revenue from operations of ₹446.85 Cr for Q1 FY27, up 49.7% YoY from ₹298.43 Cr and up 19.6% QoQ from ₹373.78 Cr in Q4 FY26. But consolidated PAT collapsed to just ₹1.99 Cr, down 92.5% from ₹26.59 Cr a year ago — even as it marks a turnaround from Q4 FY26's ₹12.97 Cr loss. Net profit margin fell to 0.43% from 8.21% YoY, and operating margin (segment result before finance cost/tax over total income) turned negative at -1.90% versus +2.03% a year ago, though it improved from -7.00% in Q4 FY26. No street previews were found for this micro-cap, so vs-street is unknown; management has issued no specific Q1 FY27 numeric guidance to grade this print against directly (only the medium/long-term targets below), so vs-guidance is also unknown for the quarter itself.
The compression is a two-segment story. Healthcare Network — the dominant segment at ₹411.78 Cr revenue (92% of the group, up 47.8% YoY) — posted a segment loss of ₹14.87 Cr before finance costs and tax, wider than the ₹13.09 Cr loss a year ago though narrower than Q4 FY26's ₹23.14 Cr loss; this segment carries the SastaSundar App/Retailer Shakti growth push. Financial Services, the historically profitable segment, saw its result fall to ₹5.57 Cr from ₹19.50 Cr YoY as "net gain on fair value changes" on the investment book dropped to ₹6.33 Cr from ₹19.69 Cr — a mark-to-market swing rather than an operating deterioration. The group's PBT of ₹1.97 Cr was ultimately salvaged by ₹11.32 Cr of net unallocable income at the holding-company level.
Management's FY26 concall guidance targeted ₹6,000 Cr revenue by FY30 (₹4,000 Cr from Retailer Shakti, ₹2,000 Cr from the SastaSundar App) and progressive EBITDA margin improvement toward 5% at scale, with Retailer Shakti FY27 revenue seen at ~₹1,700 Cr and a 1% EBITDA margin for the full year. One quarter in, Healthcare Network is still loss-making at the segment level — the QoQ narrowing of losses is directionally consistent with that plan, but the YoY widening cuts against it, so the FY27 margin path is unconfirmed. No management press-release commentary was available in this filing to corroborate framing. Separately, the Board's June 10, 2026 Composite Scheme of Arrangement (merging Microsec Resources, Innogrow Technologies and Sastasundar Healthbuddy with Health X) remains pending regulatory approval with no accounting impact yet, beyond ₹14.75 lakh of standalone-entity scheme costs.
Post quarter-end, the company won a tax dispute with a ₹65.19 lakh demand set aside (August 3, 2026) — immaterial to Q1 numbers but a minor tailwind heading into FY27. The next checkpoints are whether Healthcare Network's segment loss keeps narrowing toward break-even, whether Retailer Shakti tracks its ~₹1,700 Cr FY27 revenue/1% EBITDA path, and how the pending Scheme of Arrangement reshapes the group's segment mix once effective.