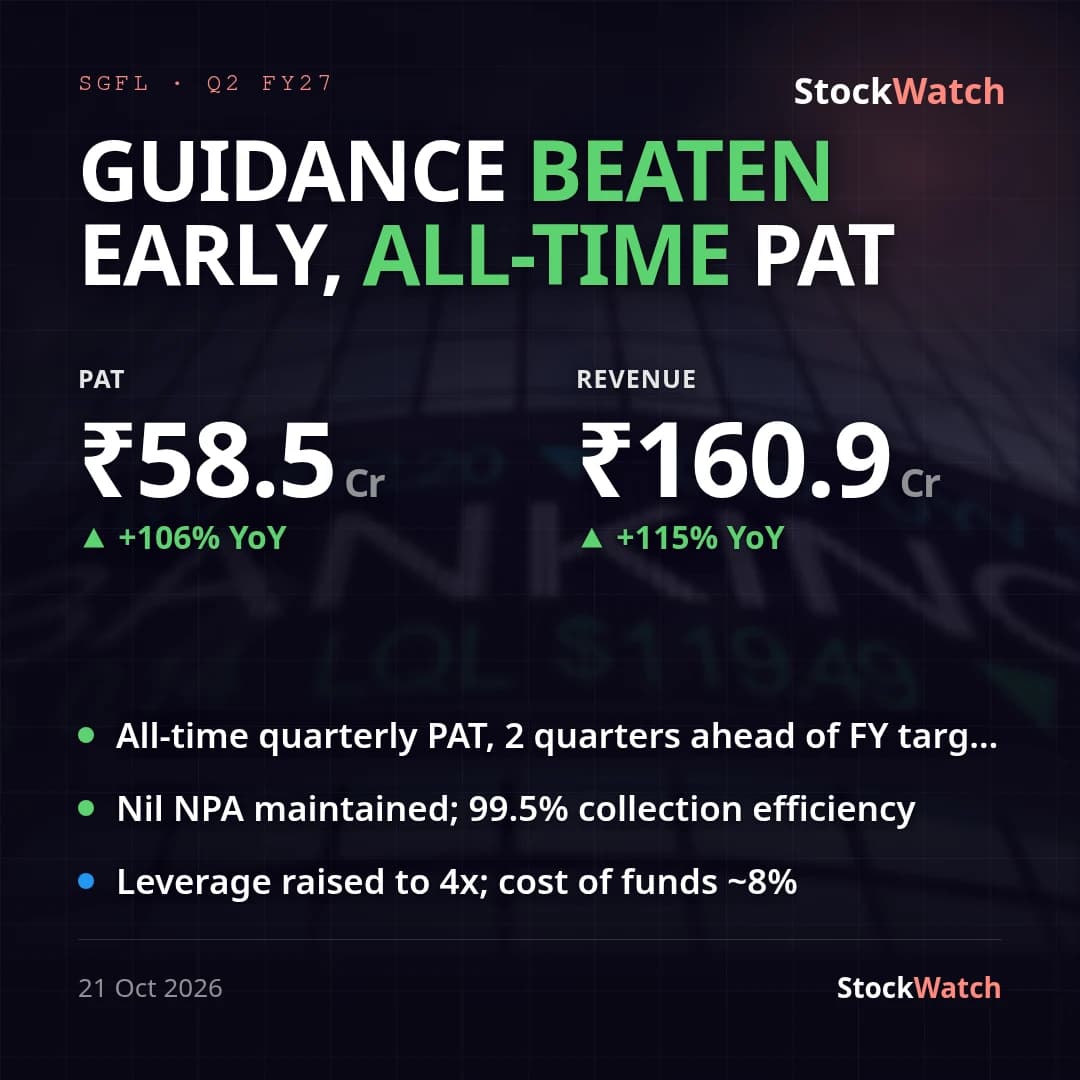
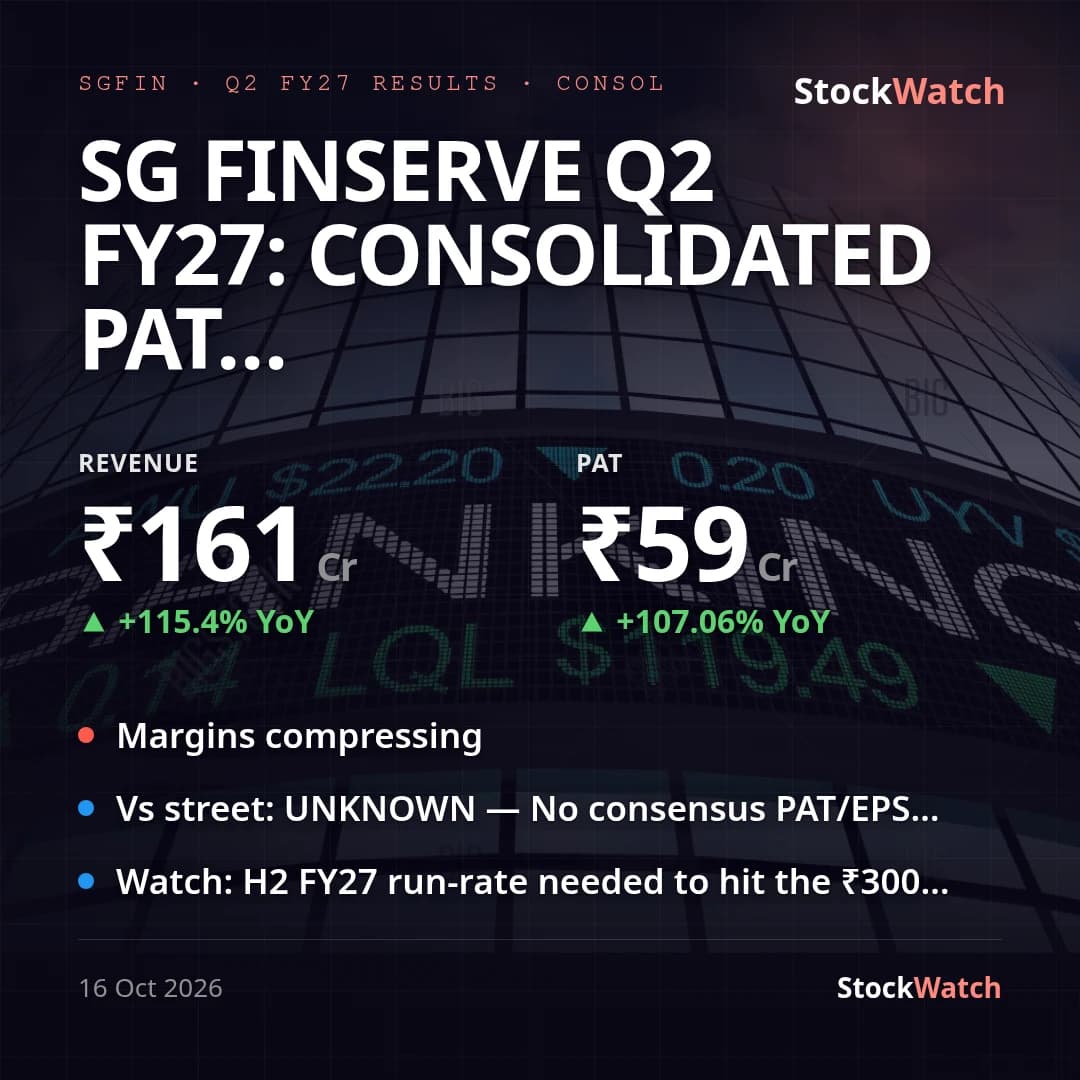
SG Finserve Q2 FY27: Consolidated PAT doubles YoY to ₹58.5 Cr, NPM eases to 36.5%
SG Finserve's Q2 FY27 (quarter ended September 30, 2026) consolidated PAT came in at ₹58.53 Cr, up 106.4% year-on-year from ₹28.40 Cr in Q2 FY26, on consolidated revenue of ₹160.94 Cr (+115.4% YoY). Standalone tells the same story at essentially the same scale — PAT ₹58.80 Cr, up 107.1% YoY on revenue of ₹160.94 Cr — with the gap between the two (under 0.5%) explained entirely by two newly consolidated, auditor-flagged-immaterial subsidiaries rather than any divergence in the core lending business. Sequentially, growth continued but decelerated as expected for a scaling book: standalone PAT rose 9.6% QoQ (₹53.68 Cr in Q1 FY27) on 18.2% QoQ revenue growth, versus the 27% QoQ PBT growth the company flagged in Q1 — a normal moderation, not a red flag, since YoY remains the primary read and that stayed strong.
The quarter's story is operating leverage lagging a book that is scaling fast: standalone net profit margin eased to 36.54% from 39.43% last quarter and 38.01% a year ago, with finance costs of ₹68.22 Cr (NPM eased to 36.5%).
consuming over 42% of total expenses as the loan book, funded increasingly through debt (debt-equity moved to 2.73x from 2.18x QoQ per the regulatory ratio disclosures), scaled alongside revenue. Gross and net NPAs remained nil for the quarter, so the margin dip is a funding-cost/mix effect on a fast-growing book, not a credit-quality issue — consistent with the zero-NPA watch item flagged pre-result.
Against management's own FY27 guidance of ₹300 Cr PBT and a ₹5,500 Cr AUM target, the quarter is tracking ahead: H1 FY27 standalone PBT of ₹150.98 Cr is almost exactly half the full-year PBT target (on pace, with two quarters to go), while the loan book has already reached ₹5,694 Cr as of H1-end — past the full-year AUM target with Q3 and Q4 still ahead, confirming the 25-30% AUM CAGR ambition laid out last quarter. Against our pre-result preview's expectations, the print lands squarely in range: Q2 PBT of ₹79.38 Cr (standalone) / ₹79.11 Cr (consolidated) sits within the flagged ₹75-80 Cr band, and the loan book at ₹5,694 Cr is marginally below the ~₹5,750 Cr estimate but still represents a 16%+ sequential pace. Street coverage remains thin — no consensus PAT/EPS estimate exists per our pre-result check, only broker price targets (Arihant Capital BUY, target ₹646; Univest target ₹705 for 2026) — so this print cannot be graded against a numeric consensus, only against the company's own guidance, which it is meeting or beating. The board used the same meeting to approve a 15.5% stake (₹4.65 Cr) in Succession Technologies, an IT-services firm, explicitly to build in-house AI and digital capability for the company's supply-chain financing and digital-lending book, alongside a 24.5% related-party stake in SG Enterprise Solutions for shared group services and a ₹48 Cr GIFT City subsidiary investment plan — all incremental infrastructure bets rather than capital-structure changes, with management reiterating no equity raise is planned.