Shivalik Bimetal Q2 FY27: consol PAT up 40% YoY to ₹34.8 Cr, revenue surges 44%, OPM up
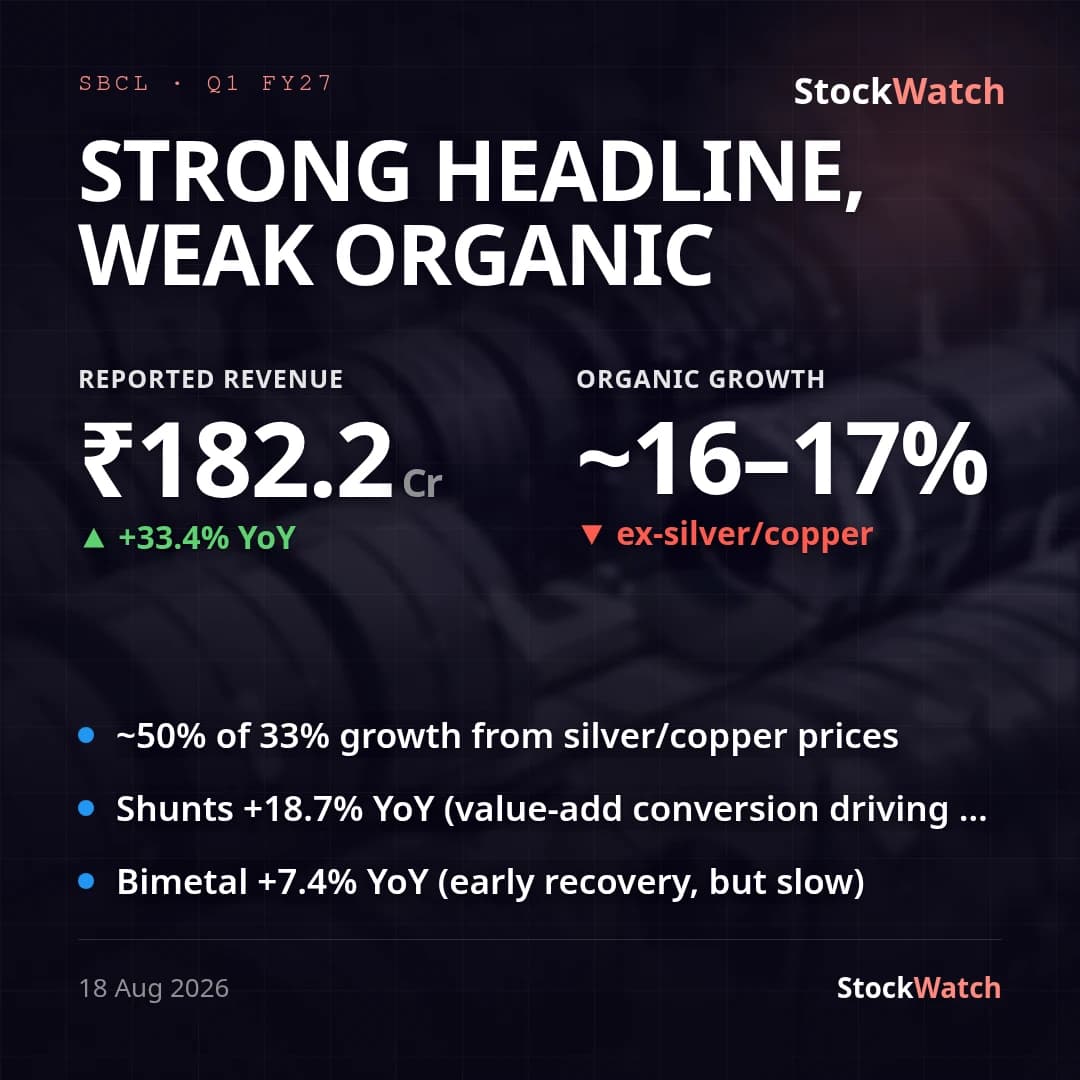
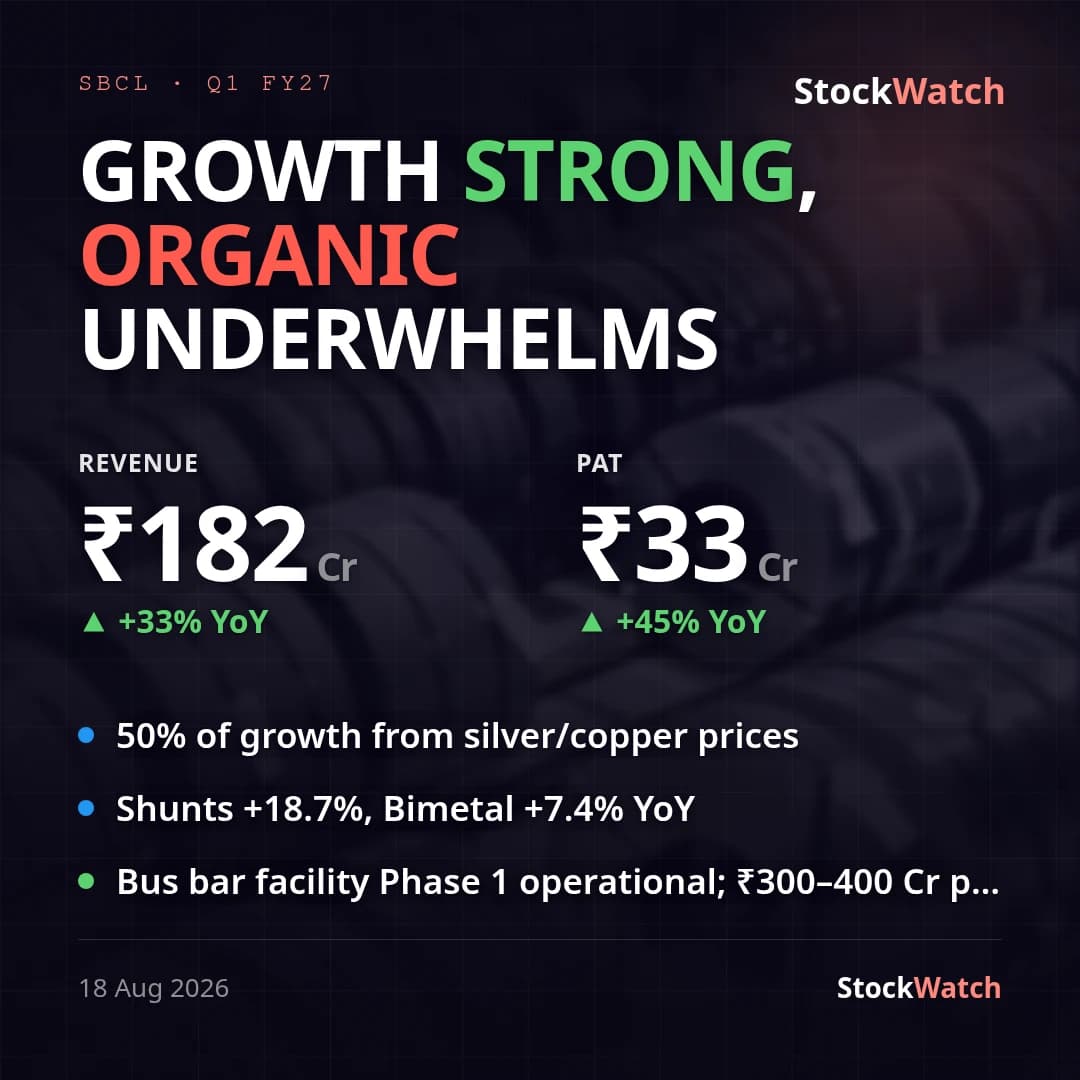
On a consolidated basis — the primary read — Shivalik Bimetal posted Q2 FY27 revenue of ₹197.79 Cr, up 43.95% YoY and 8.56% QoQ, with net profit of ₹34.75 Cr, up 39.82% YoY and 5.29% QoQ. Both figures run well ahead of management's own FY27 guidance of 20–30% organic revenue growth (ex-commodities) issued last quarter — H1 FY27 consolidated revenue is already up 38.68% YoY. No Q2-specific brokerage estimate could be located; against Trendlyne's FY27 consensus of +21.4% revenue and +22.8% profit growth, the quarter's pace is running materially hotter, which points to likely upward estimate revisions rather than a miss.
The margin picture is two-sided. Core operating margin expanded to 25.38% from 22.62% a year ago and 23.86% last quarter, reflecting better absorption of material and employee costs as volumes scaled. But net margin slipped to roughly 17.6% from about 18.1% a year ago, because finance costs jumped 84% YoY to ₹2.11 Cr and depreciation rose 61% YoY to ₹5.41 Cr — both consistent with the ongoing Pune capex (₹28.70 Cr spent on PP&E/CWIP in H1 FY27 consolidated) — while the effective tax rate also ticked up to roughly 25.8% from 24.7%. In other words, the business itself is getting more profitable before financing and depreciation; it is the cost of funding the expansion that is compressing the bottom line.
Standalone revenue grew a slower 22.37% YoY to ₹144.91 Cr (PAT +40.80% to ₹29.81 Cr) versus the consolidated 43.95% — a gap of roughly ₹52.9 Cr in revenue that did not show up at the standalone level, pointing to the wholly owned subsidiary (likely housing the bus bar/CCS assembly ramp management guided at ₹30–60 Cr in year one of a ₹300–400 Cr three-year opportunity) as the quarter's real growth engine; the board separately noted restructuring of that subsidiary's bank borrowing facilities, consistent with it needing working-capital headroom for the ramp. Alongside the result, the board declared a 100% (₹2/share) interim dividend and a 2:1 bonus issue, and flagged a leadership transition — a new CFO joins in January 2027 (interim charge with Whole-time Director Sumer Ghumman until then), the Company Secretary resigns effective December 7, 2026, and director Swarnjit Singh passed away on September 1, 2026. Pune Phase 2 is guided to turn operational in October 2026, which should shape the depreciation and finance-cost trajectory into Q3.