Star Cement Q2 FY27: consolidated PAT falls 44% YoY to ₹39.6 Cr on margin squeeze
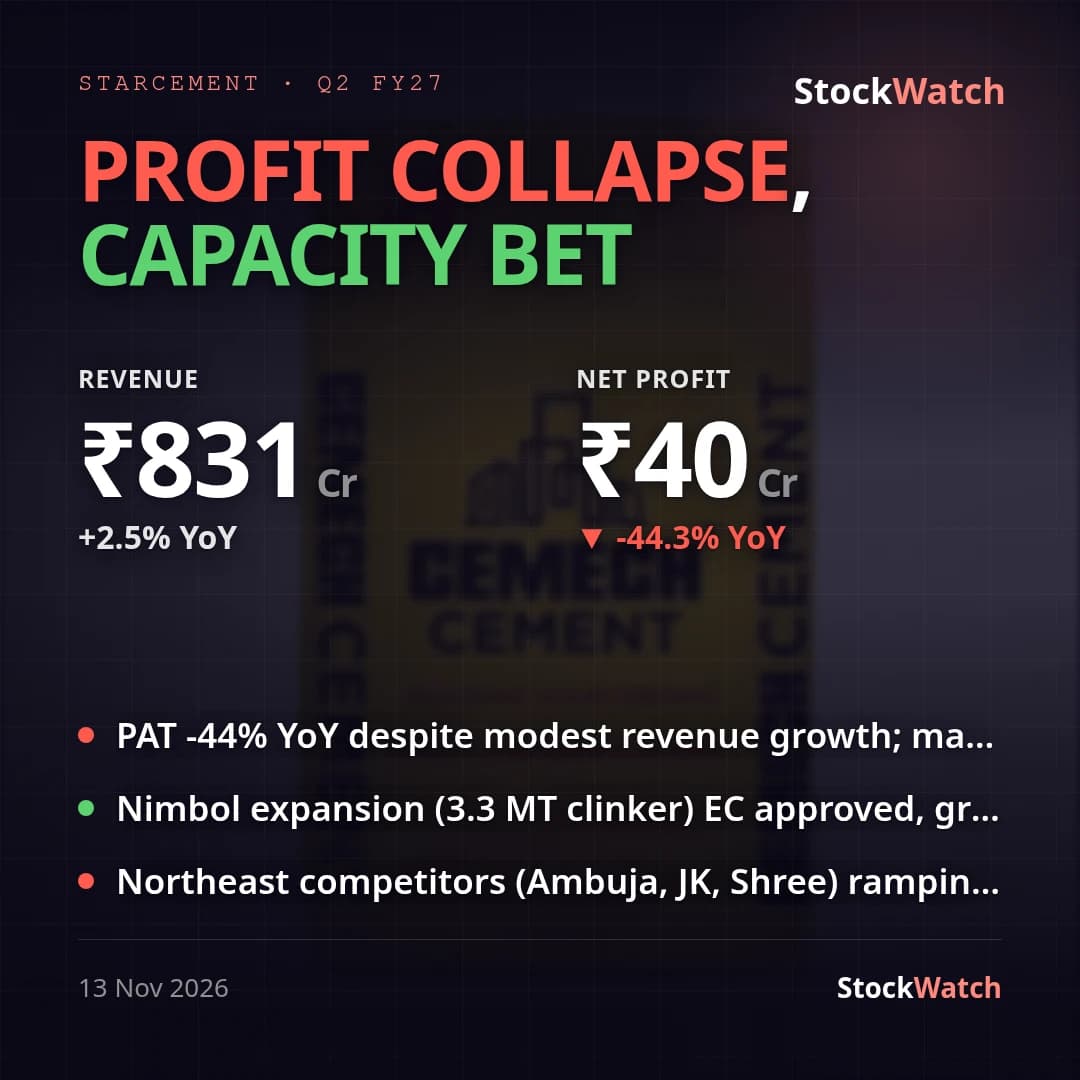
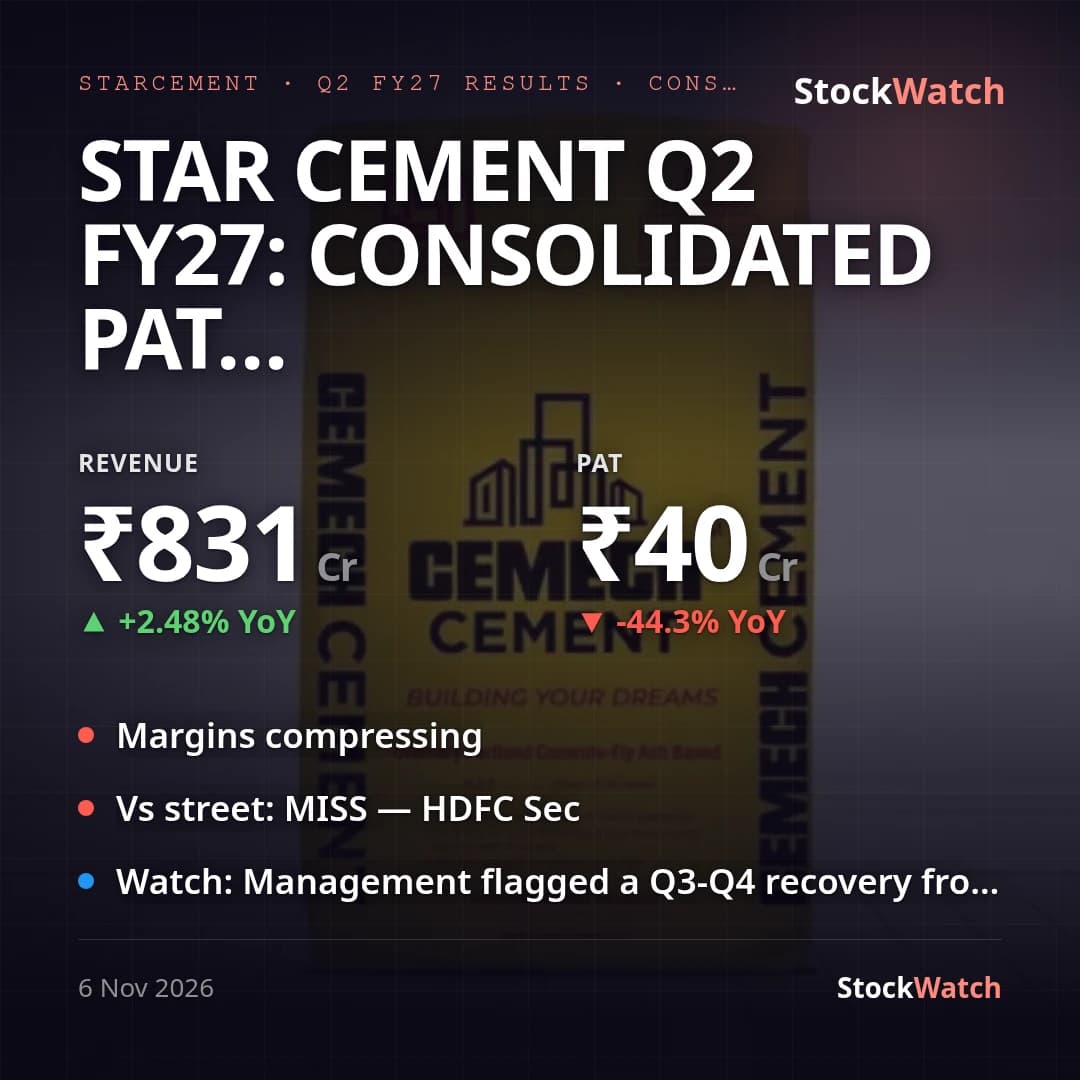
Star Cement's consolidated (primary) PAT for Q2 FY27 (quarter ended September 30, 2026) fell 44.3% YoY to ₹39.58 Cr, from ₹71.06 Cr in Q2 FY26, and was down 46.4% sequentially from ₹73.91 Cr in Q1 FY27. Consolidated revenue grew a modest 2.5% YoY to ₹831.03 Cr but slipped 11.9% QoQ from ₹942.89 Cr — the sequential dip is largely a seasonal monsoon-quarter pattern for an NE-India cement producer, not a one-off, so the YoY comparison is the one that matters here. EPS (basic, consolidated) fell to ₹1.00 from ₹1.78 a year ago and ₹1.85 in Q1 FY27. This is a weak print, not a loss, and it is unaudited (subject to limited review only).
The weakness is a margin story: consolidated total expenses rose 9.0% YoY to ₹786.72 Cr while total income rose only 3.4% YoY, compressing net profit margin to 4.70% from 8.73% a year ago and from 7.77% in Q1 FY27. Cost of materials consumed (+13.2% YoY), employee costs (+16.9%) and finance costs (+37.5%, as borrowings rose) outpaced the top line; power & fuel cost was the one tailwind, down 16.1% YoY. Notably, standalone (parent-only) PAT actually rose 23.6% YoY to ₹18.98 Cr — the entire consolidated shortfall sits at the subsidiary level, where combined profit contribution fell to roughly ₹20.6 Cr this quarter from roughly ₹55.7 Cr a year ago (and ₹50.2 Cr last quarter). That lines up with management's own guidance that fiscal incentives would be cut to ₹115 Cr for FY27 from ₹145 Cr following an Assam policy change — those incentives accrue to the operating (subsidiary) entities, not the standalone parent.
Against a pre-result preview from HDFC Securities (Sep 2026) that guided to flattish YoY volume and flattish QoQ margins (EBITDA/tonne of ~₹1,400 versus a FY27 target of ₹1,500-1,600, hit by a planned maintenance shutdown), the actual margin compression was sharper than guided — a miss on that specific marker, even as revenue growth roughly tracked the flattish-volume call. Against management's own prior-concall guidance (defensive tone, negative short-term outlook, Q3-Q4 recovery expected from pent-up demand), this soft Q2 print is consistent with — not a departure from — what was already flagged; no company press-release commentary was available to cross-check at filing time. Same-day, the board declared a 100% (₹1/share) interim dividend and deferred a previously shareholder-approved ₹1,500 Cr fundraise, citing capital-market conditions, saying capex (₹500 Cr planned for FY27, ₹1,500 Cr for FY28, both unchanged) will instead be funded via internal accruals and/or bank borrowings — consistent with the 37.5% YoY jump in finance costs this quarter.
Going forward, the quarter sets up three checks: whether the Q3-Q4 recovery from pent-up demand that management flagged actually materialises in the next print; whether subsidiary-level profit (down to ~₹20.6 Cr this quarter) stabilises as the lower Assam incentive run-rate (₹115 Cr guided) fully phases in; and whether finance costs keep climbing as capex is funded through borrowings rather than the shelved equity raise.