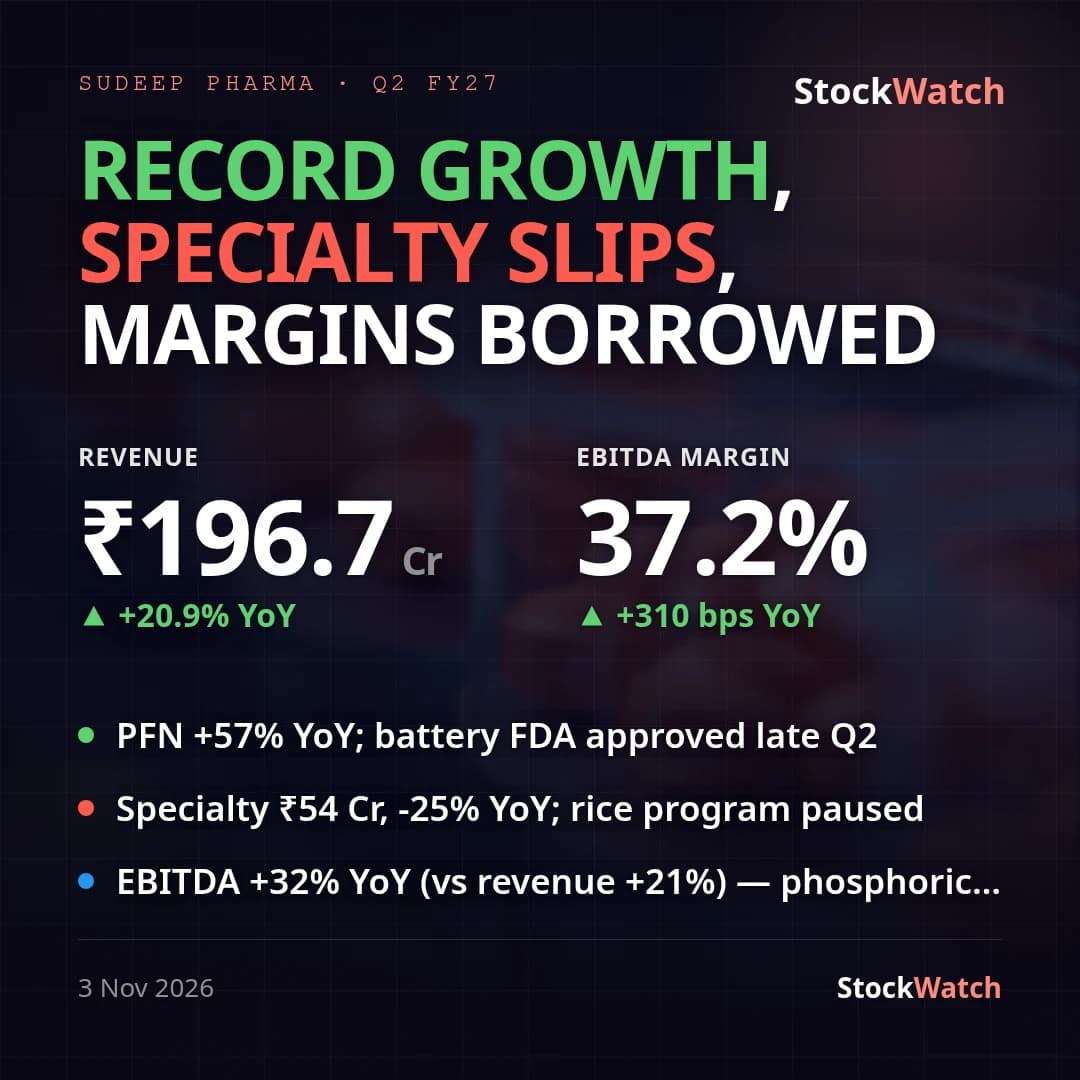
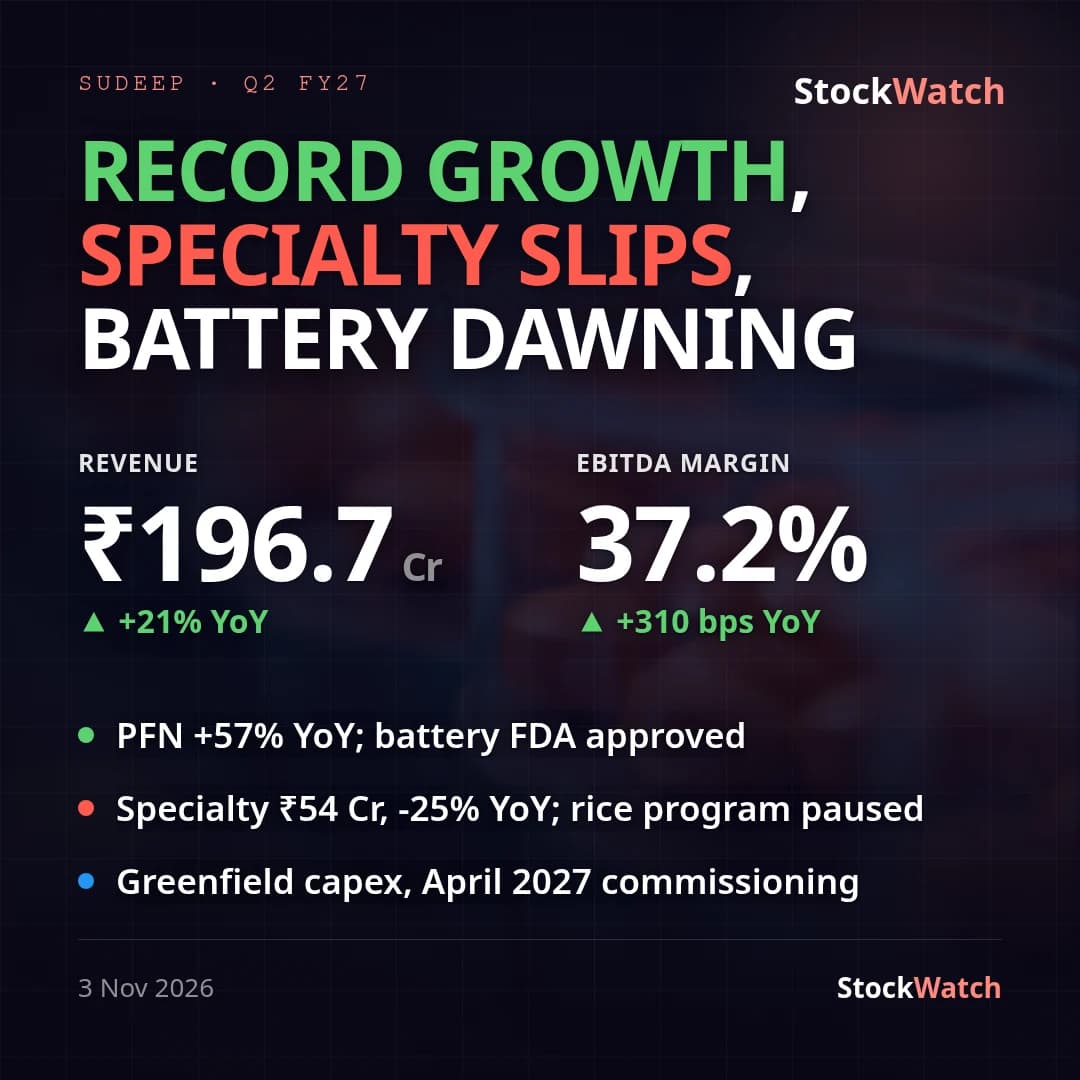
Sudeep Pharma's consolidated Q2 FY27 print: revenue ₹196.70 Cr (+20.9% YoY, +24.3% QoQ), PAT ₹51.81 Cr (+10.8% YoY, +27.7% QoQ), EPS ₹4.59. Both land above our pre-result preview's working range (revenue ₹165–180 Cr, PAT ₹43–47 Cr), and EBITDA margin of 37.24% sits inside the preview's 35–37% watch band and inside management's own 37–38% guided recovery band from 34.7% — a line management said would recover "within quarters" at the Q1 call and delivered on this quarter. Analyst coverage is thin (2 analysts, 1 Hold/1 Sell, median target ₹663.50 vs CMP ₹966.2) and no public PAT/revenue consensus exists to benchmark against; against our own pre-result range the print is a clear beat on revenue, margin and profit.
The EBITDA bridge (PBT + D&A + finance costs − other income) rose to ₹73.24 Cr from ₹55.46 Cr a year ago, with the gain concentrated in the Pharmaceutical, food & nutrition segment — external revenue up 57.5% YoY to ₹142.50 Cr, segment profit nearly doubling (+97.6% YoY). That was offset by Speciality ingredients, where external revenue fell 24.9% YoY to ₹54.20 Cr and segment profit dropped 42.1% YoY — directly contradicting the Q1 guidance that this segment would "return to its historical growth trajectory" in Q2 (the +8.7% QoQ uptick doesn't erase the YoY decline). Net profit margin actually slipped to 25.56% from 27.07% a year ago (even as it improved from 24.79% last quarter), because finance costs (+23.3% YoY to ₹2.81 Cr) and depreciation (+41.1% YoY to ₹5.38 Cr) — both tied to the capex buildout (consolidated PPE went from ₹223.99 Cr at 31 March 2026 to ₹400.57 Cr at 30 September 2026) — plus a higher effective tax rate (27.1% vs 21.4% YoY) ate into the EBITDA gain before it reached the bottom line.
Standalone PAT of ₹42.34 Cr grew 42.4% YoY on revenue up 56.4% YoY, far outpacing the consolidated numbers — confirming the group-level growth drag sits entirely in the Speciality ingredients subsidiaries, not the core standalone pharma/nutrition business. Among this quarter's disclosed developments: USFDA approval for the Gujarat plant (Oct 26) is a regulatory positive for the pharma segment but falls just outside the reporting quarter; the MD transition at the US subsidiary (announced Oct 5) is the execution risk the pre-result preview flagged, and this filing carries no further commentary on it. No standalone management press release accompanied this filing to cross-check against company framing. Beyond reaffirming the 37–38% EBITDA band, the greenfield commissioning (Q3 FY27) and SAM Phase 1 (April 2027) targets from the Q1 call, management offered no new quarter-specific guidance in the filing notes.