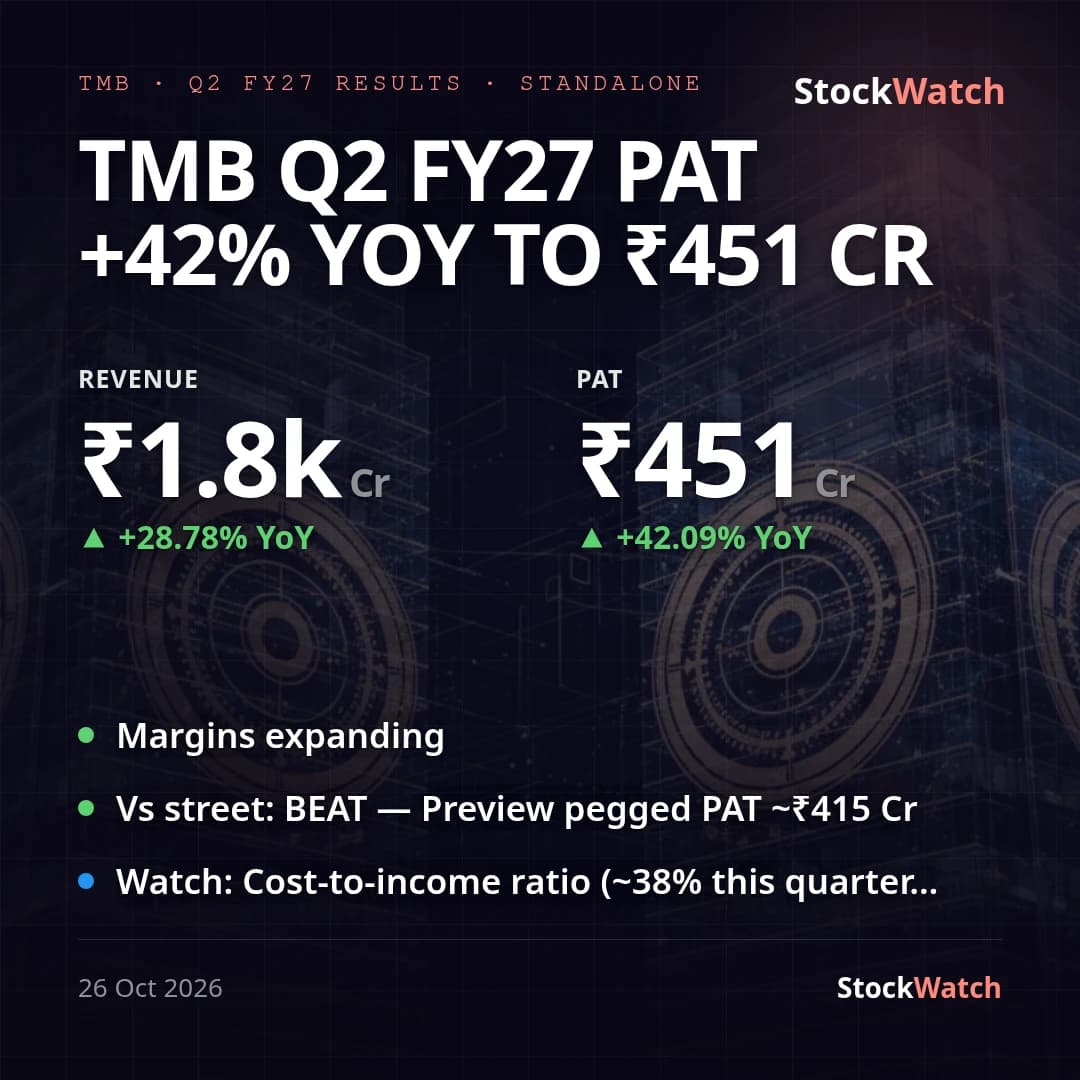
TMB Q2 FY27 PAT +42% YoY to ₹451 Cr, NPM expands to 22%, beats Street and guidance
Tamilnad Mercantile Bank's standalone net profit rose 42.1% year-on-year to ₹451.14 Cr for Q2 FY27 (interest earned ₹1,820.16 Cr, +28.8% YoY), comfortably ahead of both the Street's pre-result marker of ~₹415 Cr (a ~8.7% beat) and our preview's ₹410–425 Cr expected band. Adjusted for a ₹15.45 Cr one-off — a provision reversal after the SAFEMA Appellate Tribunal cut the penalty on the bank and its directors from ₹16.99 Cr/₹2.25 Cr to ₹3.4 Cr/₹0.39 Cr — underlying PAT growth is closer to ~38.5%, still strong but a touch below the reported headline. Sequentially PAT grew a slower 9.6% QoQ and revenue 9.5% QoQ, which is the secondary read; the YoY print is what carries the quarter.
Net profit margin expanded to 21.98% from 19.58% a year ago and 21.65% last quarter, while the operating margin improved YoY (31.26% vs 27.90%) but eased slightly from Q1's 32.15%. The margin story is balance-sheet-led rather than cost-led: advances grew 29.7% YoY to ₹60,429 Cr and deposits 25.5% YoY to ₹69,546 Cr, both running well ahead of the 21–22% advances and 18% deposit growth management guided on the Q1 call, and total business is up 27.27% YoY to ₹1,30,261 Cr per our event records — consistent with the quarter's own numbers. Asset quality improved further, with Gross NPA down to 0.61% (from 1.01% YoY, 0.69% QoQ) and Net NPA at 0.14%, against management's <1% GNPA guidance — a clear beat. ROA rose to 2.18% from 1.85% YoY, above the >2% guided, and CET1 held at a high 31.36%.
On guidance, the quarter mostly confirms management's confident Q1 tone: deposit/advances/total-business growth and asset quality all ran ahead of plan, though the cost-to-income ratio (computed on NII plus other income) stayed low at roughly 38%, extending rather than normalising from Q1's "unusual" ~39% that management had guided would drift up to 46–47% — a case where the quarter undershoots its own stated cost trajectory, favourably. NIM was not separately disclosed in this filing, so the >4% NIM guidance cannot be directly checked from the statement alone. The quarter also saw an RLLR cut to 8.50% (Oct 7) and continued branch expansion (Kadambur and two others), both consistent with the volume-led growth story, while a new RBI-approved director appointment is a governance item with no numeric read-through. No separate management press release was available with this filing to cross-check against the numbers.
Going into Q3, the open items are whether cost-to-income moves toward the guided 46–47% band or stays structurally low, how CASA — not disclosed in this result — tracks against management's ~27–30% target, and whether the ~30%/25% advances/deposit growth pace holds given the deposit-repricing competition flagged in the pre-result Street read.