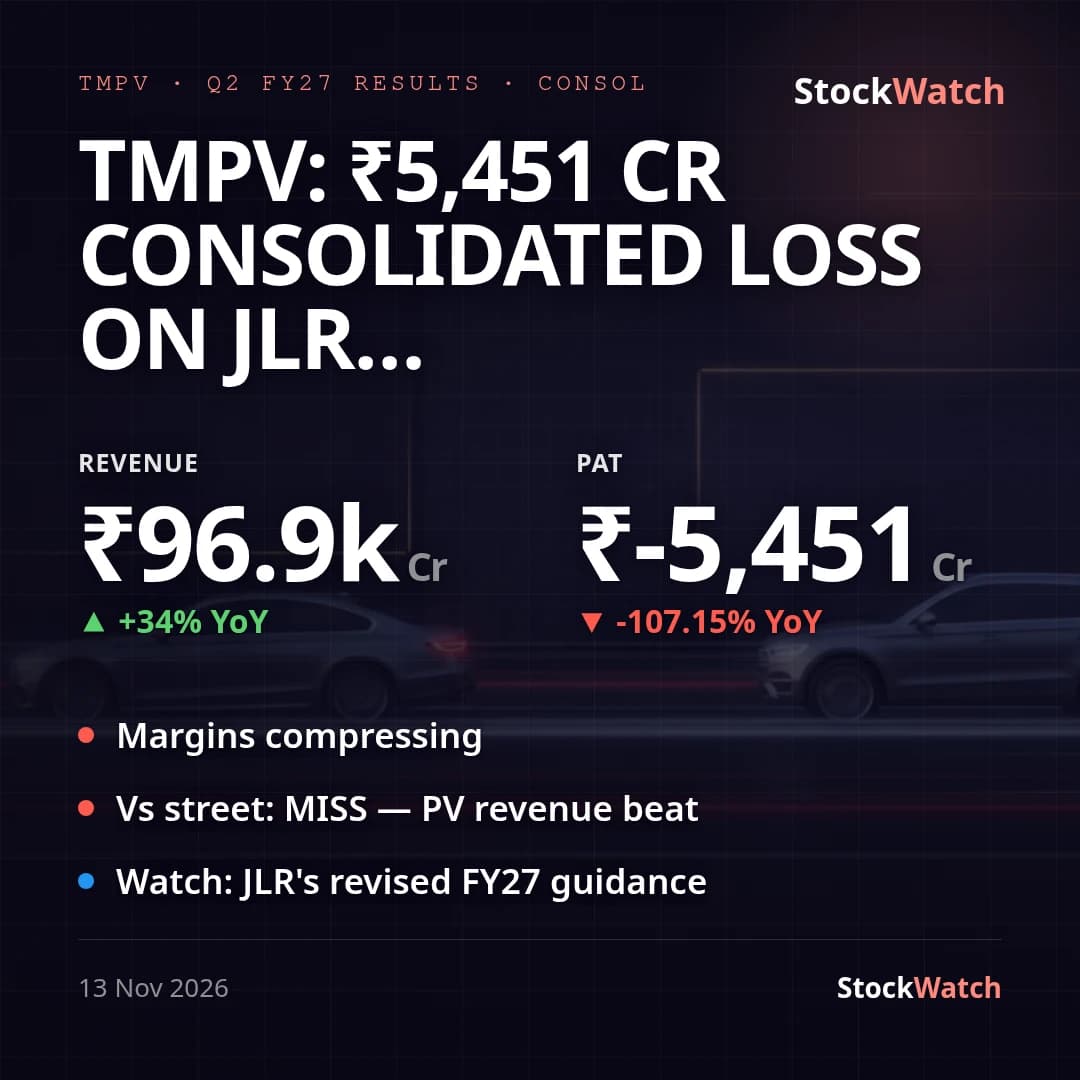
TMPV: ₹5,451 Cr consolidated loss on JLR exceptional charge; core PBT turns positive
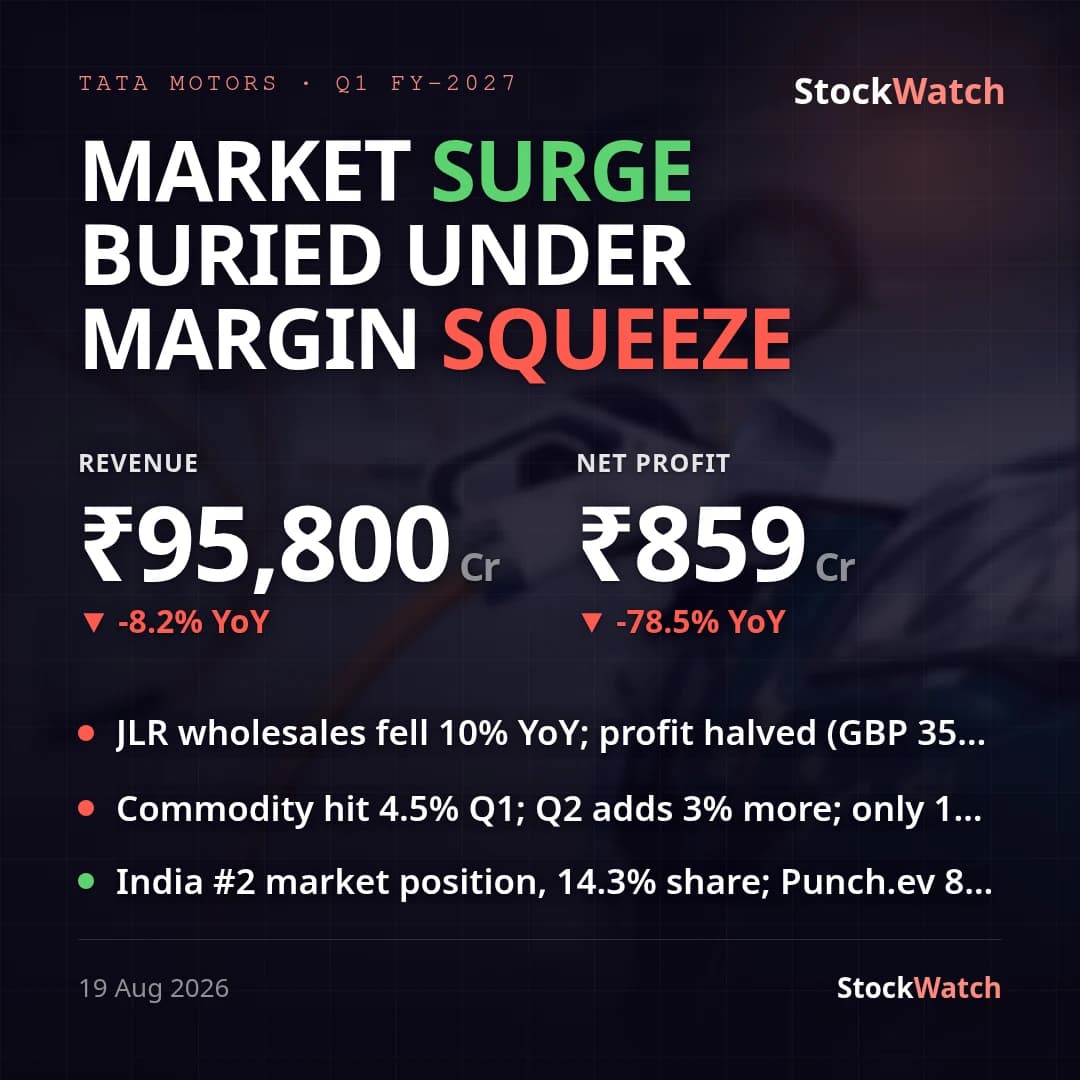
Tata Motors Passenger Vehicles Ltd. (TMPV, formerly Tata Motors Ltd., now housing JLR plus the India PV business after the October 2025 commercial-vehicle demerger) swung to a consolidated net loss of ₹5,451 Cr in Q2 FY27, against a ₹859 Cr profit in Q1 FY27 and a reported ₹76,248 Cr profit a year ago — a figure that was almost entirely a one-off ₹82,616 Cr demerger gain rather than operating profit. Stripped of one-offs on both sides, the picture flips: adjusted PBT (before exceptional items) was ₹403 Cr this quarter versus an adjusted loss of roughly ₹5,462 Cr in Q2 FY26, when JLR was still recovering from its cyber incident — an underlying swing of about ₹5,865 Cr YoY even though the reported bottom line is negative. Revenue rose 34.0% YoY (+1.2% QoQ) to ₹96,920 Cr, with JLR wholesales up 20.3% YoY to 82,400 units on the cyber-incident base effect and Tata PV posting a record ₹20,423 Cr (+51% YoY) on 40% volume growth.
The reported loss was driven by ₹6,738 Cr of exceptional items — chiefly JLR employee separation costs and an asset impairment — taken against a core PBT of just ₹403 Cr; a ₹1,745 Cr deferred-tax credit narrowed the eventual net loss to ₹5,451 Cr. Margins stayed under pressure on both sides of the group: consolidated EBITDA margin was 6.2%, down from 6.41% in Q1 FY27 even as it improved roughly 630 bps YoY off a depressed base, while Tata PV's standalone EBITDA margin compressed further to 4.0% (-180 bps YoY) despite record volumes, as adverse mix and commodity costs outpaced the roughly 1% pricing taken through H1. Standalone (TMPV ex-JLR) results were barely profitable, with PAT of ₹3 Cr on ₹19,201 Cr revenue.
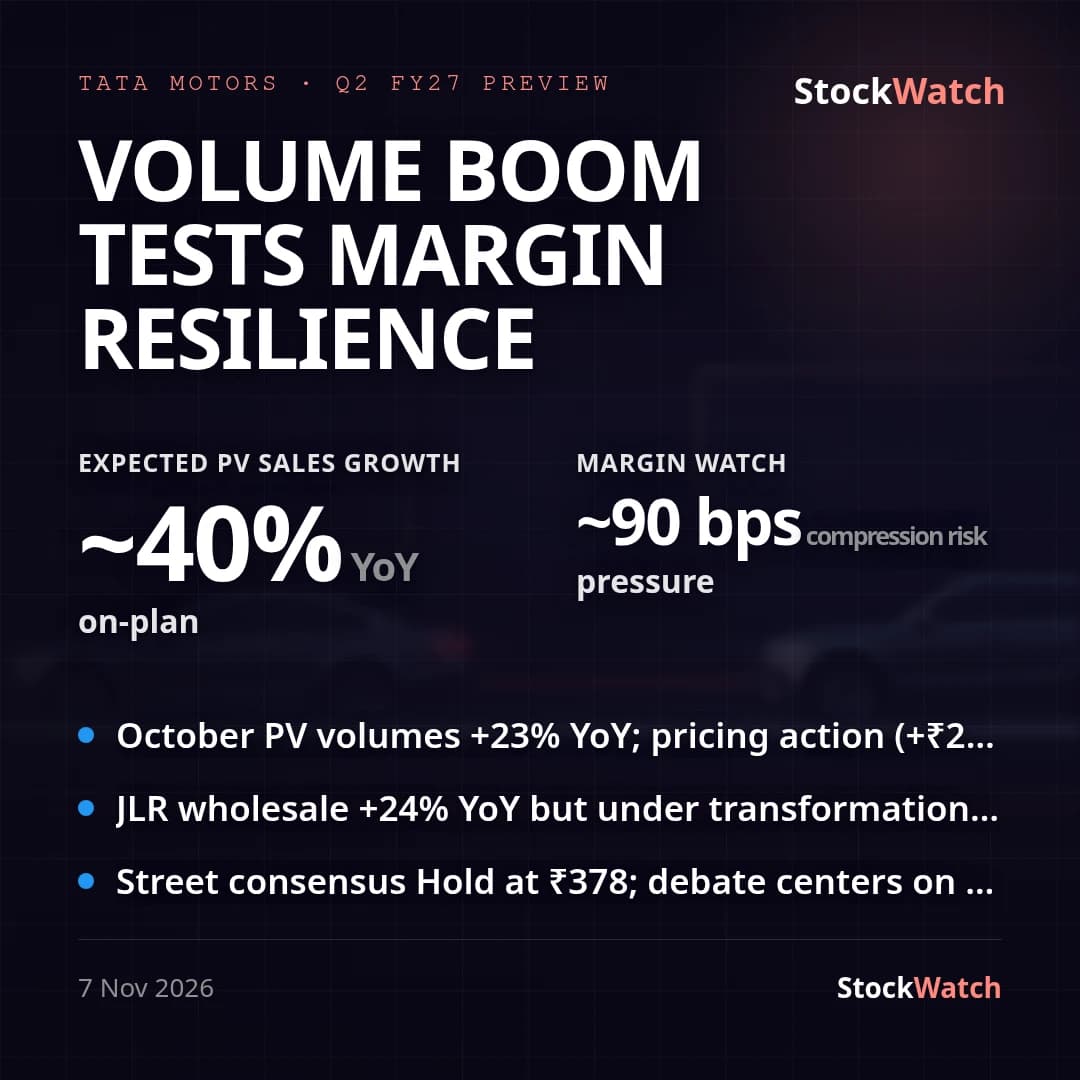
Street consensus (27-analyst poll, Hold rating, average target ₹378.74) and our pre-result preview had flagged margin squeeze as the key swing factor; against the preview's expected Tata PV revenue band of ₹18,500-19,000 Cr and EBITDA margin of 9-10.5%, the actual print beat on revenue but missed badly on margin (4.0% actual), confirming the preview's central thesis. On guidance, the India business continued to outperform — 40% volume growth comfortably beats management's own "higher double-digit" FY27 target reiterated last quarter — but JLR cut its full-year outlook to an adjusted EBIT margin of 2-3% and free cash outflow of roughly £1.25bn, reversing the "maintaining full-year guidance" line management held at the Q1 call; that is a guidance miss at the group level even though the domestic business beat its own bar.
Management's own framing (CFO Dhiman Gupta) attributed the margin pressure to "adverse mix and persistent commodity pressures" while calling both businesses "fundamentally strong." JLR CEO PB Balaji pointed to three new EV launches (Range Rover Electric, Range Rover Sport Electric, Jaguar Type 01, deliveries from early 2027) and the £1.7bn Enterprise Missions cost-savings plan as the path back from the cut guidance range, while Tata PV CEO Shailesh Chandra flagged EV volumes nearly doubling (+90% YoY, 43% EV market share) as evidence that pricing and cost actions are still being calibrated against commodity headwinds rather than resolved.