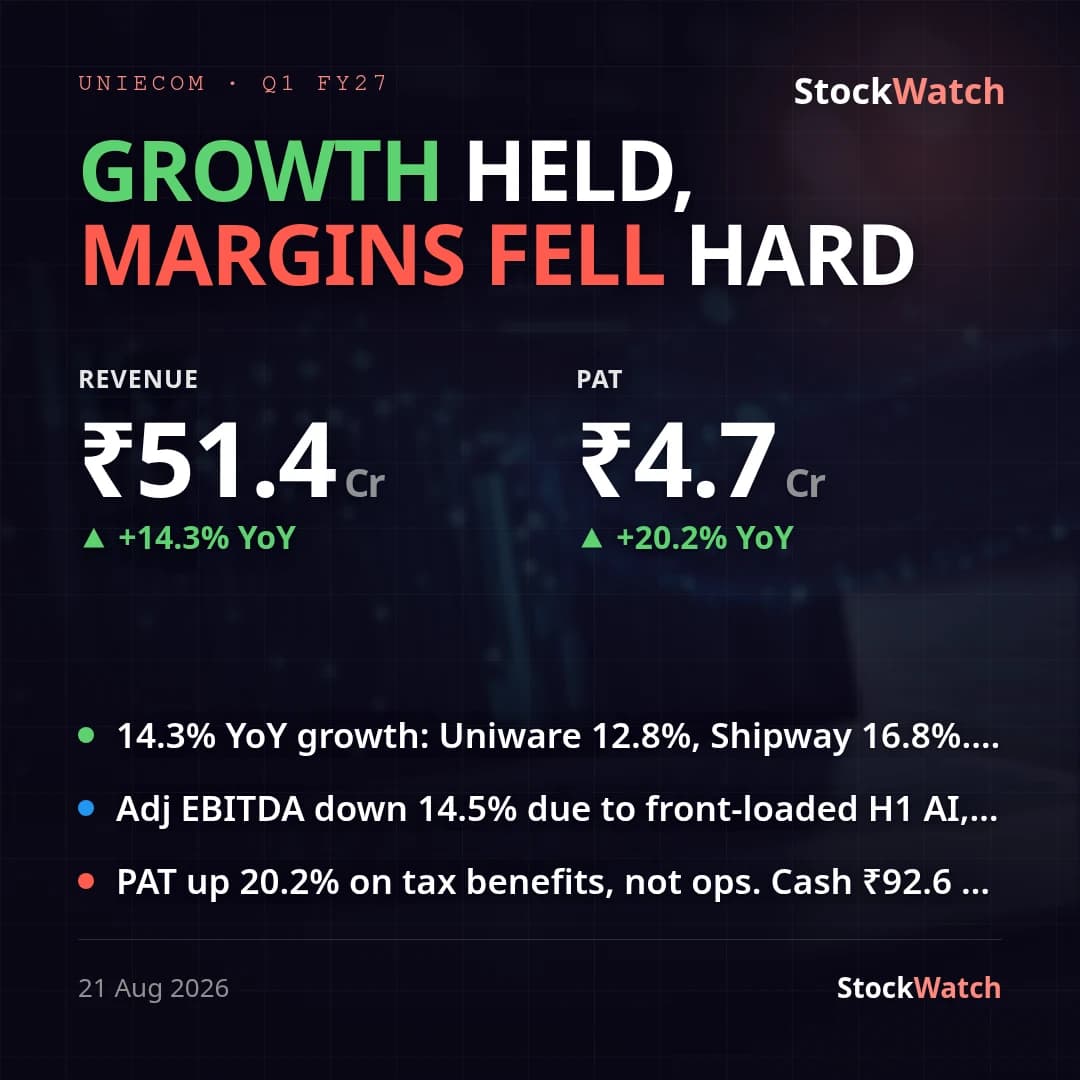
Unicommerce Q1 FY27: revenue +14.3% YoY, OPM compresses to ~11% on guided AI investment
Unicommerce's consolidated Q1 FY27 revenue rose 14.3% YoY to ₹51.37 Cr (down 0.5% QoQ), with reported PAT climbing 20.2% YoY to ₹4.68 Cr (₹0.40 basic EPS). That headline profit growth is not operational, though: consolidated PBT actually fell 11.5% YoY to ₹4.56 Cr, and the entire PAT increase traces to a swing in the tax line — a ₹0.11 Cr net tax credit this quarter versus a ₹1.27 Cr tax expense a year ago. Applying Q1 FY26's ~24.6% effective tax rate to this quarter's PBT gives an adjusted PAT of roughly ₹3.44 Cr, an ~11.5% YoY decline — the underlying read is materially weaker than the +20.2% reported figure suggests. No street consensus for this specific quarter turned up in a search, so vsStreet is marked unknown rather than guessed.
The pressure sits squarely on operating margin: OPM (revenue less employee, hosting and other opex) compressed to ~10.7% from 18.7% a year ago and 13.4% last quarter, as employee benefits expense (₹20.61 Cr, the largest cost line), server hosting (₹1.78 Cr) and other expenses (₹23.51 Cr) all grew faster than the 14.3% topline. This tracks what management flagged after Q4 FY26: guidance called for lower adjusted EBITDA/PAT over the next two quarters due to stepped-up AI, sales and marketing investment, with full-year FY27 profitability still expected to exceed FY26 — so the margin compression is on-plan rather than a surprise miss. NPM, by contrast, rose to 8.9% (from 6.4% QoQ, 8.5% YoY) — but that move is the tax credit again, not genuine margin expansion.
Segment-wise, Uniware grew 12.8% YoY and Shipway 16.8% YoY per management's own release, meeting the guided "double-digit Uniware, faster double-digit Shipway" growth split for FY27. The quarter also saw 115 new enterprise customers onboarded and fresh partnerships signed with Swiggy Networks, Ajanta Group and Opptra. Standalone PAT of ₹6.97 Cr sits well above the consolidated ₹4.68 Cr print — Shipway's ₹1.57 Cr quarterly net loss plus consolidation adjustments explain the gap, and readers comparing the two bases should expect standalone to look meaningfully stronger than consolidated this quarter. Management's framing — "pleased to start FY27 with continued momentum... driven by double-digit growth across both Uniware and Shipway" — holds at the revenue line but glosses over the PBT decline and margin compression underneath.
Two things to track from here: whether OPM recovers toward the high-teens as the AI/sales investment phase matures, since management's own full-year FY27 profitability guidance depends on it; and whether the tax line normalizes — a return to a ~24-25% effective rate would mechanically pull reported PAT growth back toward the weaker PBT trend.