UNO Minda Q2 FY27: consolidated PAT up 37% YoY to ₹441 Cr, revenue +38% to ₹6,655 Cr
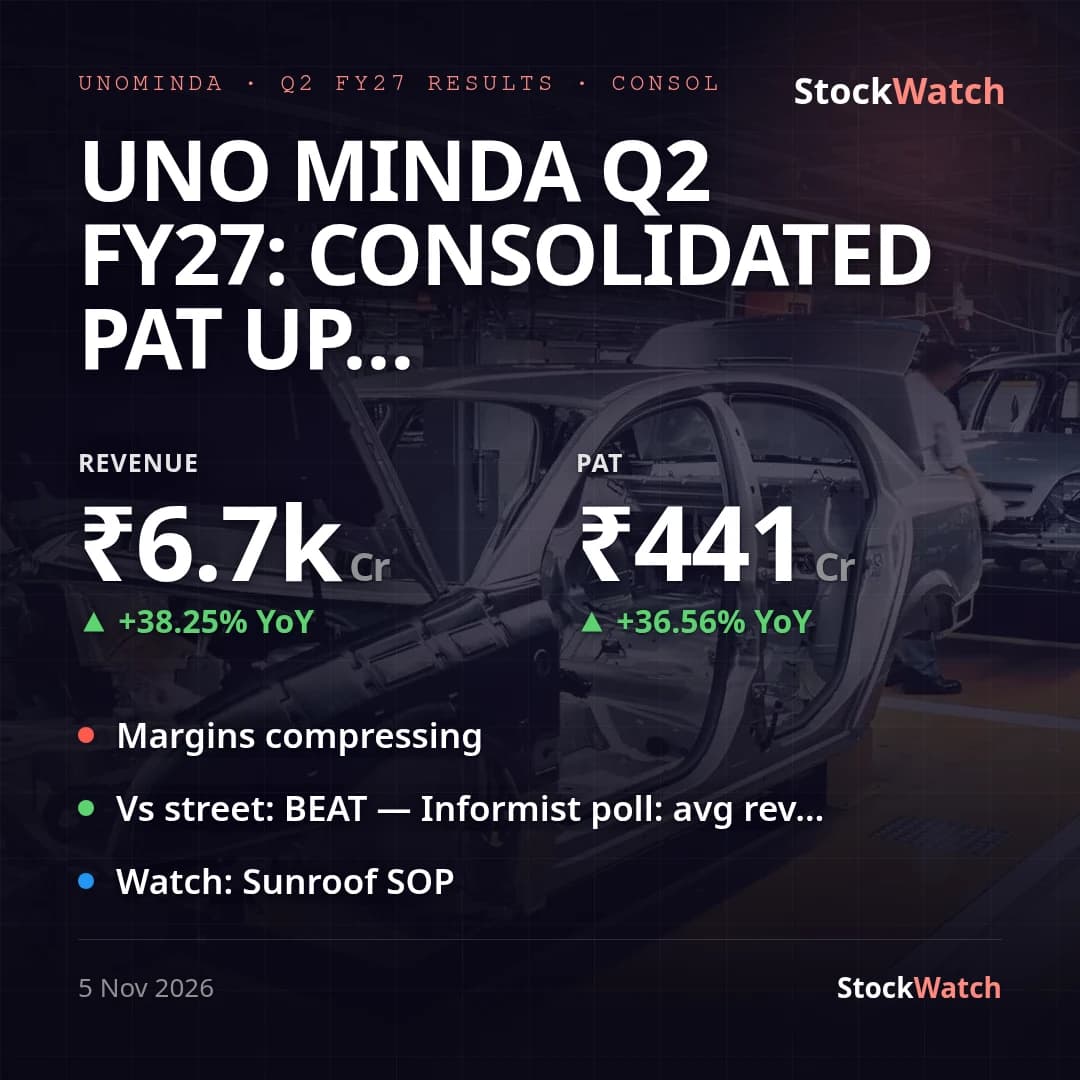
UNO Minda's consolidated revenue came in at ₹6,655.42 Cr, up 38.2% YoY from ₹4,814.03 Cr and 19.8% QoQ from ₹5,556.85 Cr. Net profit for the period was ₹440.81 Cr, up 36.6% YoY (₹322.79 Cr) and 39.7% QoQ (₹315.51 Cr); the owners' share was ₹419.72 Cr, up 38.1% YoY. Basic EPS rose to ₹7.27 from ₹5.28 a year ago. Neither this quarter nor the year-ago quarter carried exceptional items, so these are clean, unadjusted comparisons. Standalone told a softer story — revenue ₹4,907.98 Cr (+35.1% YoY) but PAT of just ₹392.58 Cr (+16.0% YoY) — with the gap versus consolidated driven almost entirely by a 29% YoY drop in standalone other income (dividends from subsidiaries fell to ₹83.31 Cr from ₹115.55 Cr), an intercompany flow that nets out on consolidation rather than a sign of weaker operations.
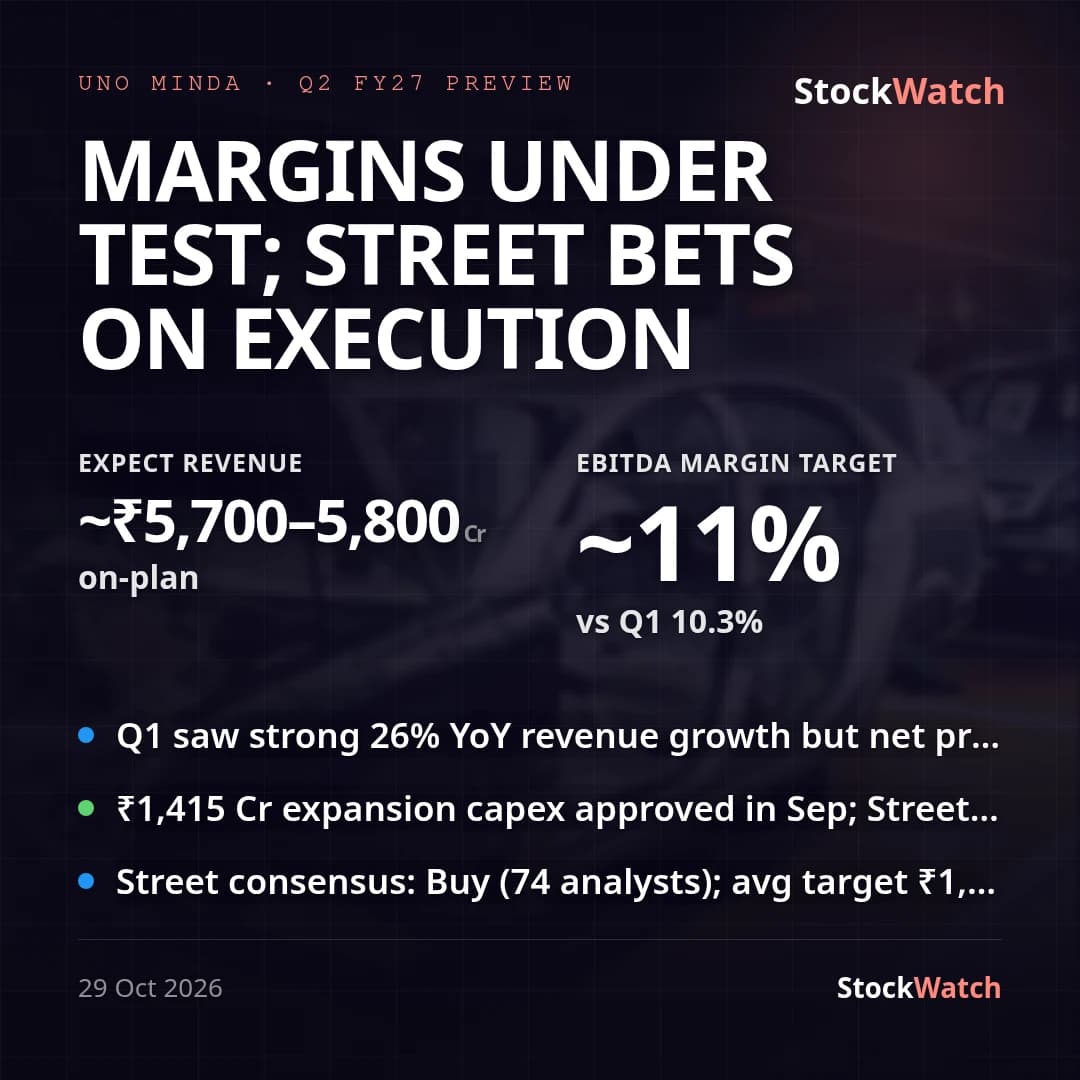
The print came in well above Street. Informist's brokerage consensus had pegged the quarter at revenue of roughly ₹4,795 Cr and PAT of roughly ₹281 Cr, with EBITDA margin seen contracting about 36bps YoY; UNO Minda's actual topline and bottom line both landed well clear of those averages. Margins were mixed depending on the reference period: operating margin (PBT before JV/associate share and exceptional items, adjusted for depreciation, finance cost and other income, over revenue from operations) was 11.02%, down 44bps from 11.46% a year ago but up 73bps sequentially from 10.29% in Q1 FY27; net profit margin was 6.62%, down a slim 8bps YoY but up 95bps QoQ. Against management's own FY27 guidance of 11% EBITDA margin ±50bps with a stated bias toward the higher end (given on the August concall), the 11.02% print sits mid-band — on track with guidance, but not yet showing the higher-end bias management had flagged.
The quarter's capex pipeline stayed active alongside the result. The Board approved an incremental ₹85 Cr for sunroof capacity at Bawal (adding 2,91,000 units p.a., SOP targeted from Q2 FY28), layered on the existing 1,45,000-unit line still awaiting its own March-2027 start-up — consistent with the 'sunroof capacity to start end-FY27, peak FY29' timeline management laid out last quarter. That sits alongside the ₹1,415 Cr four-project expansion approved September 15, the ₹1,500 Cr+ capacity/NCD approval from September 14, and two ₹100 Cr commercial paper issuances (September 25, October 28) funding working capital through the ramp. The Board also approved a leadership reshuffle effective November 5: Nitesh Minda becomes CEO-designate of the SCS Domain ahead of A.G. Giridharan's retirement, Kartikeya Joshi is elevated to Chief Marketing Officer, and Amit Jain is re-designated Group Chief Growth and Technology Officer with expanded EV and manufacturing-excellence oversight.
H1 FY27 consolidated operating cash flow of ₹711.01 Cr ran against H1 capex of ₹806.53 Cr, showing the expansion being funded largely through internal accruals and borrowings within the ₹1,750 Cr FY27 capex guided in August. With revenue growth running well ahead of the 'continued healthy growth' language from the prior concall and margins sitting mid-guidance, the next checkpoints are whether H2 FY27 margins move toward the guided higher end and whether the sunroof and seating (Q2 FY28 ops) ramps stay on the timelines management has now reaffirmed through this quarter's capacity approvals.