Wockhardt Q2 FY27: consolidated PAT falls 11% YoY to ₹73 Cr as units abroad swing to loss
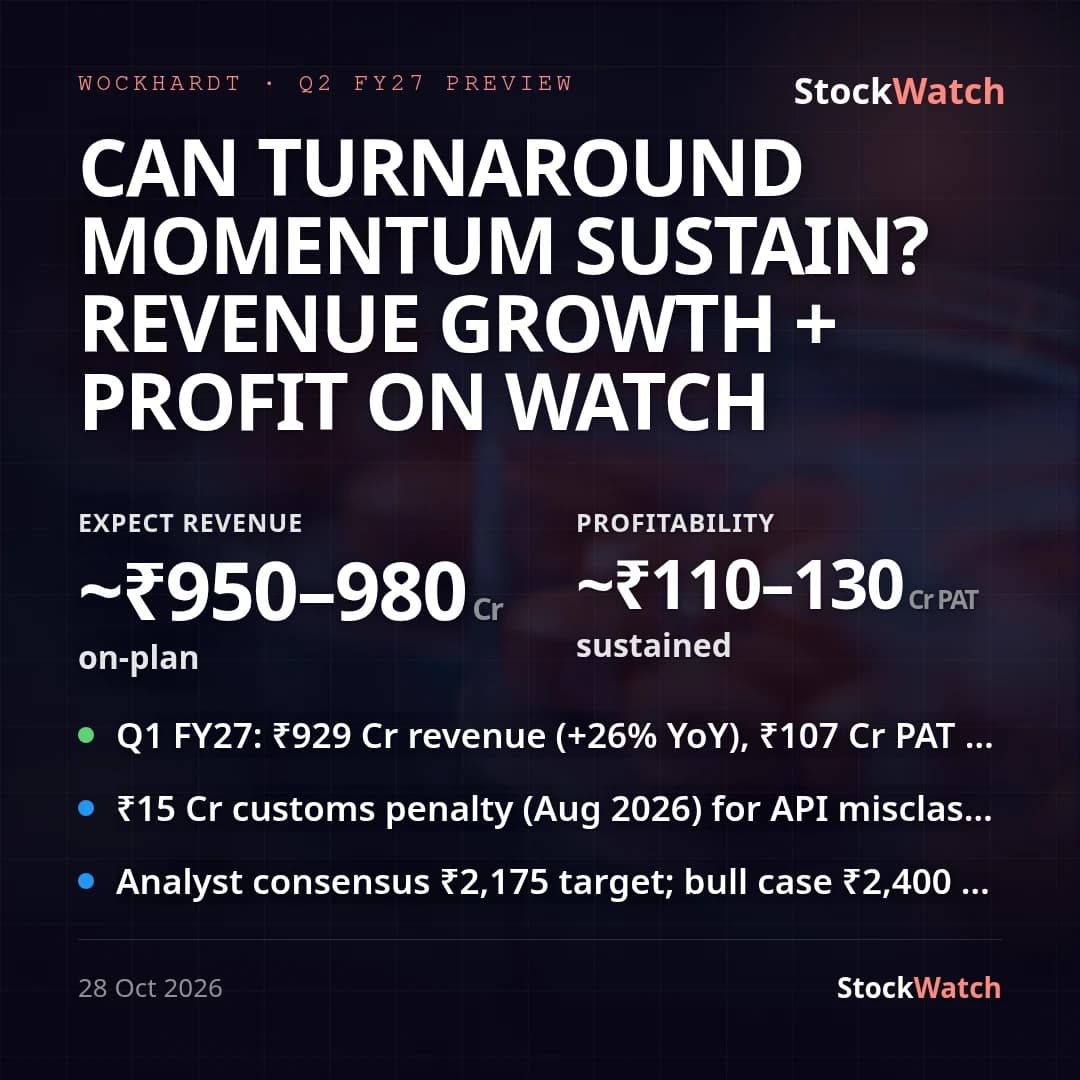
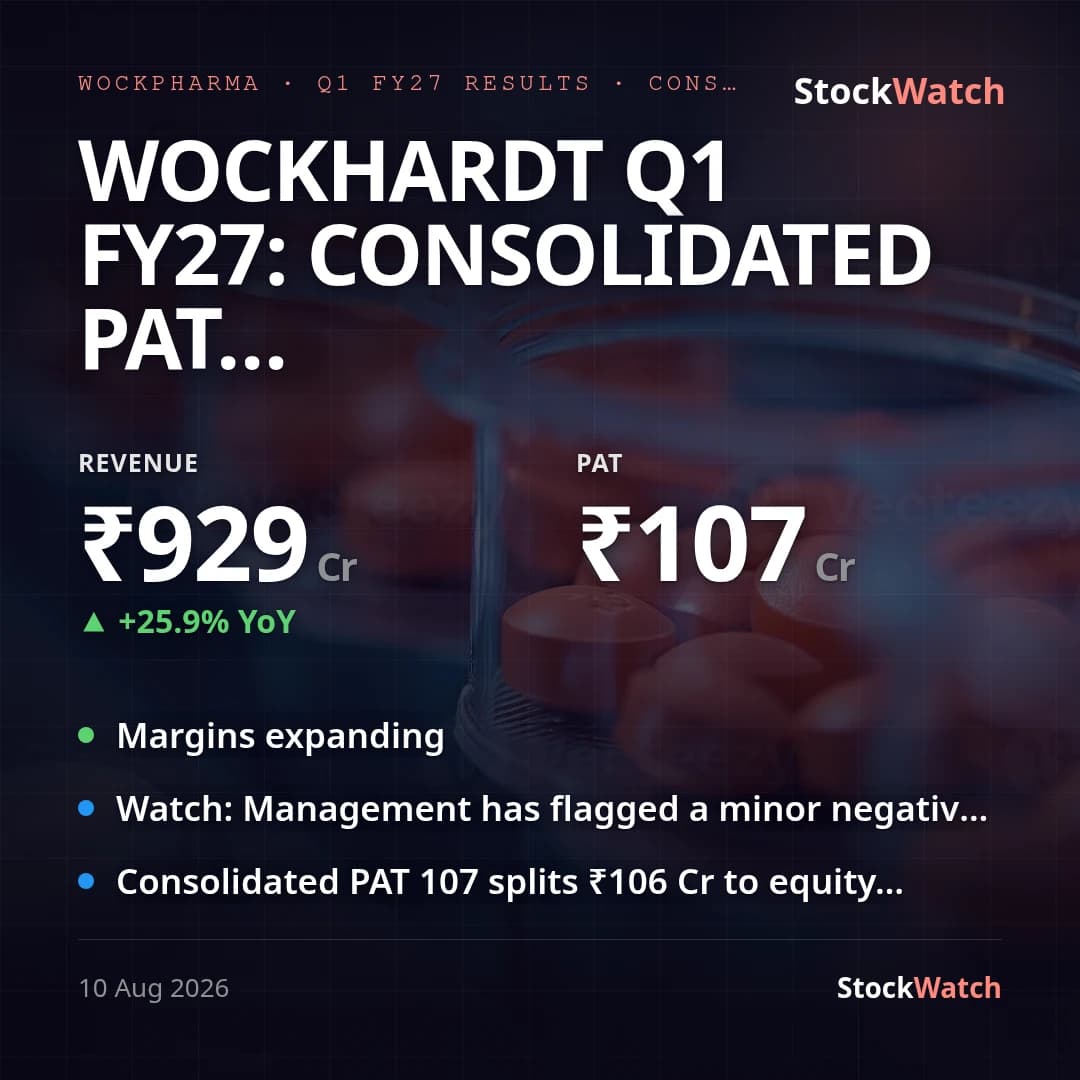
Wockhardt's consolidated (primary basis) revenue rose 23.9% YoY and 4.3% QoQ to ₹969 Cr, but consolidated net profit fell 11.0% YoY and 31.8% QoQ to ₹73 Cr, down from ₹107 Cr in Q1 FY27 and ₹82 Cr a year ago. That YoY profit decline despite strong topline growth is the headline: this was a margin-compression quarter, not a growth miss. The standalone (India) business tells almost the opposite story — standalone revenue jumped 52.6% YoY to ₹580 Cr and standalone PAT surged 85.2% YoY to ₹100 Cr, roughly in line with Q1's ₹107 Cr. The >3% divergence between the two bases is real and traceable: implied subsidiary-level profit (consolidated PAT minus standalone PAT) swung from +₹28 Cr a year ago and roughly breakeven last quarter to a ~₹27 Cr loss this quarter, even as implied subsidiary revenue held broadly flat (₹389 Cr vs ₹402 Cr YoY). The international/generics subsidiaries, not the India business, drove the miss.
The margin bridge confirms it: consolidated operating margin (EBITDA/revenue from operations) compressed to 17.85% from 22.76% a year ago and 20.67% last quarter — roughly a 490bps YoY and 280bps QoQ hit — while net margin (PAT/total income) fell to 7.45% from 10.21% YoY and 11.15% QoQ. The combined cost of materials and purchased goods (net of inventory movement) rose to about 35.2% of revenue from 29.8% a year ago, the single largest driver, with other expenses also running higher as a share of sales (27.1% vs 26.0% YoY). Finance costs (₹56 Cr) and depreciation (₹55 Cr) were both broadly flat YoY and QoQ, so the squeeze sits entirely in operating costs, not below-the-line items. One offsetting nuance: because non-controlling interest absorbed a ₹6 Cr loss this quarter (vs a ₹4 Cr profit a year ago and ₹1 Cr last quarter), PAT attributable to Wockhardt's own shareholders (₹79 Cr) held up far better than total PAT — down just ~1.3% YoY and basic EPS was effectively flat at ₹4.85 against ₹4.81 a year ago, even though total consolidated PAT fell double digits.
No consensus estimates for this specific quarter turned up in a search, and the comparison context carries no prior management guidance or concall read on record, so this cannot be graded against a Street number or a stated outlook — management gives no formal guidance on this print. Among the quarter's corporate developments, the company confirmed on August 10 that QIP proceeds utilization showed no deviation, consistent with continued capex/pipeline build: consolidated intangible assets under development rose to ₹1,743 Cr (from ₹1,708 Cr at FY26-end) and capital work-in-progress stood at ₹676 Cr. Separately, Wockhardt was fined ₹15 Cr by Customs on August 25 for API mis-classification; since the filing shows no exceptional item this quarter, that fine — if absorbed — would sit inside the regular expense lines rather than being called out, which the company has not done explicitly.