Zaggle Q1FY27: PAT falls 33% YoY on margin compression despite 27.5% revenue growth
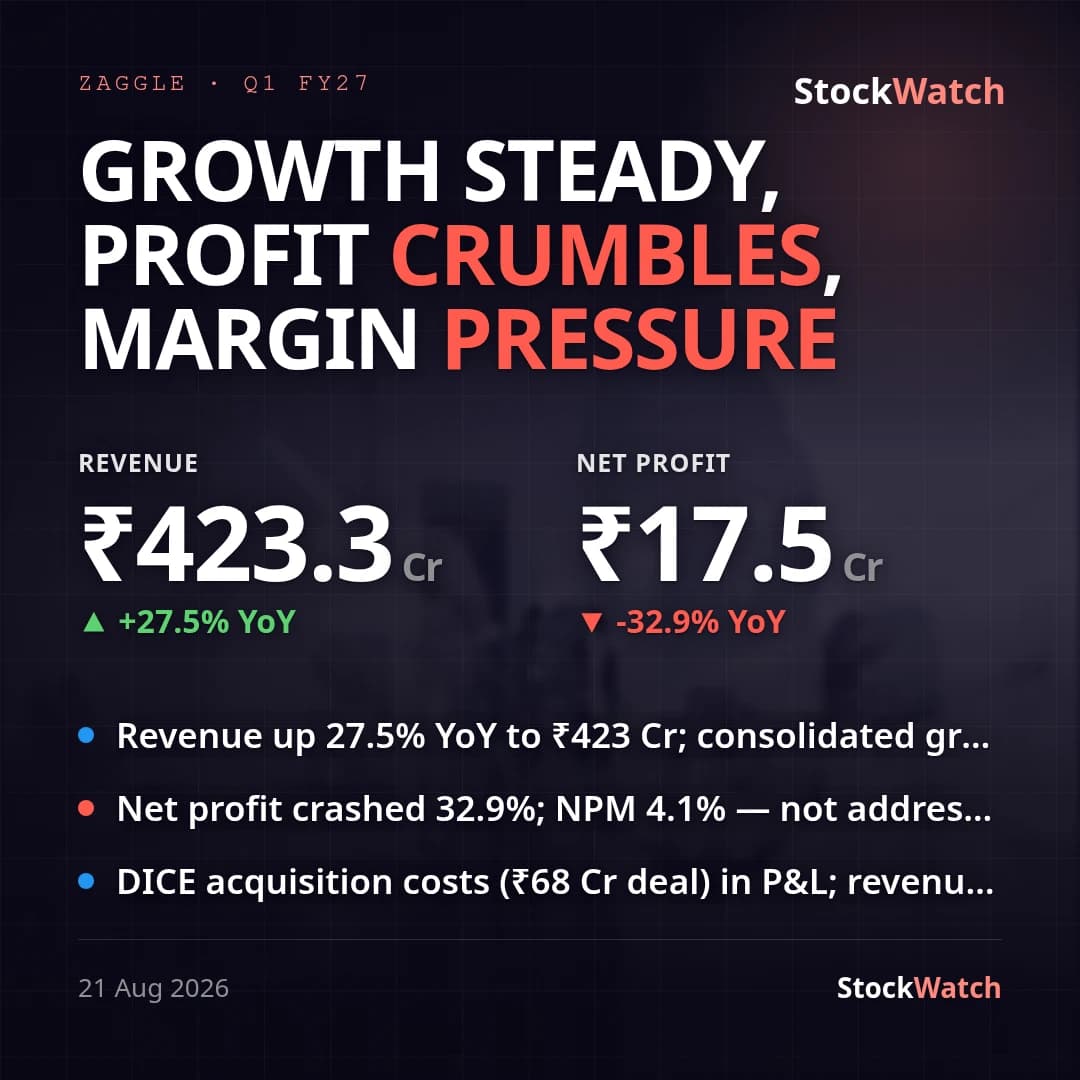
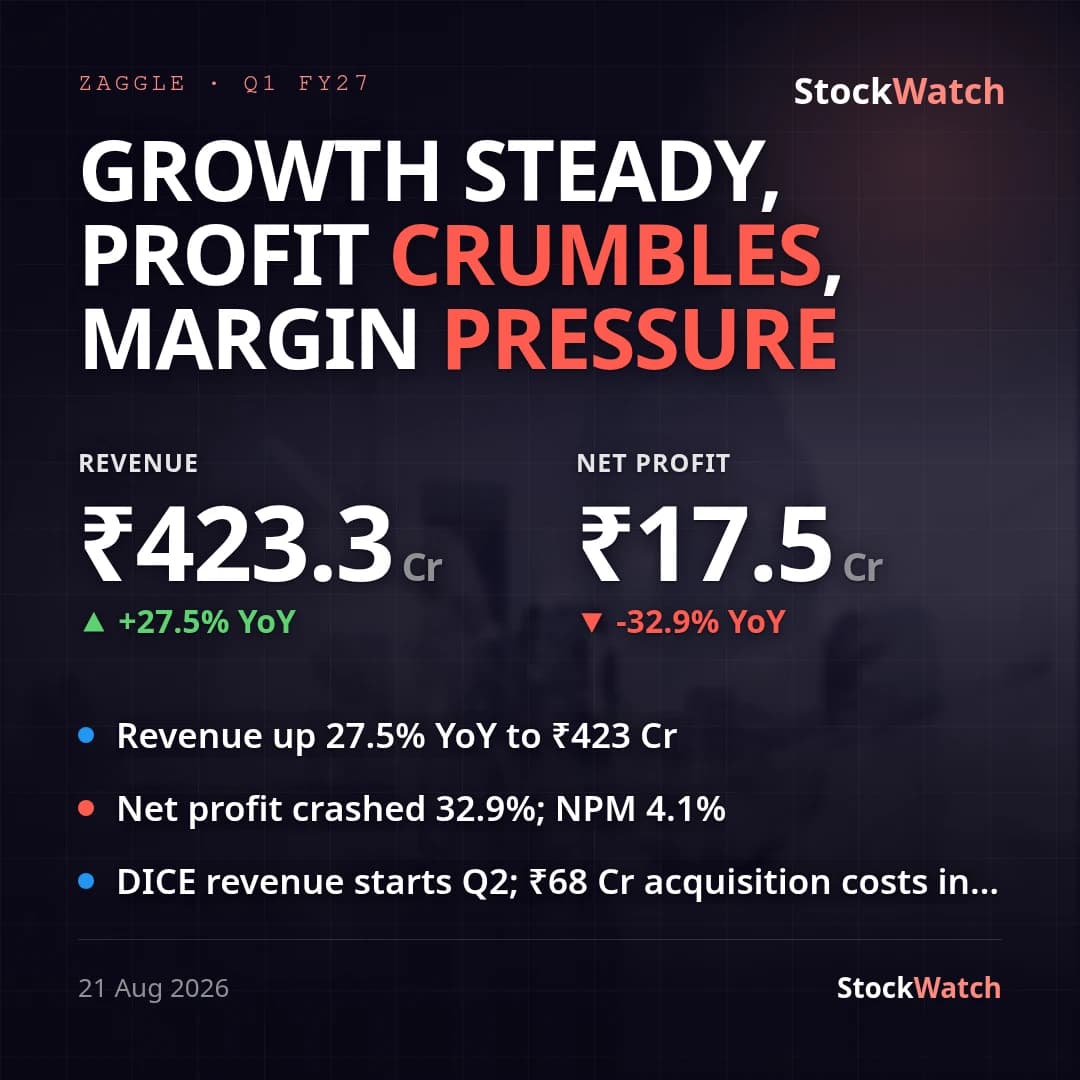
Zaggle's consolidated (primary basis) PAT came in at ₹17.53 Cr for Q1 FY27, down 32.9% YoY from ₹26.11 Cr and down 56.8% QoQ from ₹40.60 Cr, even as consolidated revenue rose 27.5% YoY to ₹423.27 Cr (down 31.5% QoQ from ₹617.92 Cr, largely a base effect since the Q4 FY26 print was itself a balancing figure between FY26 audited results and 9M FY26 reviewed numbers, and Q4 tends to carry seasonally heavier gift-card/incentive volumes). Standalone tells a softer growth story than consolidated: standalone revenue grew only 17.7% YoY to ₹390.17 Cr against 27.5% consolidated growth, a gap of roughly 10 points reflecting the contribution of newly consolidated subsidiaries (Rivpe Technology, Zaggle Payments IFSC, Greenedge) rather than organic acceleration; standalone PAT of ₹17.43 Cr was broadly in line with the consolidated figure.
The margin compression is the story of the quarter. Net profit margin fell to 4.08% of total income from 7.60% a year ago and 6.48% last quarter, while operating margin (EBITDA/revenue-from-operations) slipped to 7.30% from 9.19% YoY and 9.44% QoQ. Cost of point redemption/gift cards rose to 55.2% of consolidated revenue from 50.5% a year ago, driven by the Propel platform/gift-card revenue line growing 42.5% YoY to ₹250.70 Cr — faster and lower-margin than the Program fee (+10% YoY) and Platform/SaaS fee (+18.6% YoY) lines, shifting the revenue mix toward pass-through-heavy business. Depreciation and amortisation jumped 80.7% YoY to ₹12.69 Cr and finance costs rose 53.7% YoY to ₹1.66 Cr, both consistent with the newly consolidated subsidiaries and integration-related spend; other expenses also rose 61% YoY at the consolidated level.
Against our pre-result preview (expected consolidated revenue ~₹650-700 Cr, standalone ~₹500-550 Cr), the actual print missed on both counts by roughly 30-35% — revenue and PAT growth both undershoot, so this reads as a miss versus the Street setup rather than a beat or inline print; a broader web search turned up no formal analyst consensus revenue/PAT figure specifically for Q1 FY27, only the pre-result preview's range and general risk framing (macro slowdown, margin compression, FII selling) that flagged exactly this outcome as a risk. Against management's own FY27 guidance from the May 2026 concall — standalone revenue growth of 25-30% and consolidated growth of 40% — this quarter's 17.7% standalone and 27.5% consolidated growth both trail the guided pace, and EBITDA guidance remains formally suspended pending the DICE Enterprises asset purchase (₹67.9 Cr, still in process per note 5) integration, which management had already flagged would pressure near-term margins — a call this quarter's numbers corroborate. No standalone management press release accompanied this filing; the notes are the only management commentary available. Of the quarter's other disclosed developments, Rivpe Technology became a wholly owned subsidiary from June 11, 2026 (now consolidated for roughly three weeks of the quarter) and four subsidiaries whose interim results were not reviewed by the statutory auditor posted a combined net loss of ₹0.81 Cr; the Unobanc stake approval, APAC agreement amendment and Daimler partnership all fall after the June 30 quarter-end and are not reflected in these numbers.
Going into Q2, the quarter sets up a credibility test on the 40% consolidated FY27 growth guidance, which needs meaningfully faster growth in the remaining nine months after a 27.5% YoY start, alongside management's stated focus on turning operating cash flow positive even as D&A, finance costs and gift-card mix continue to pressure margins.