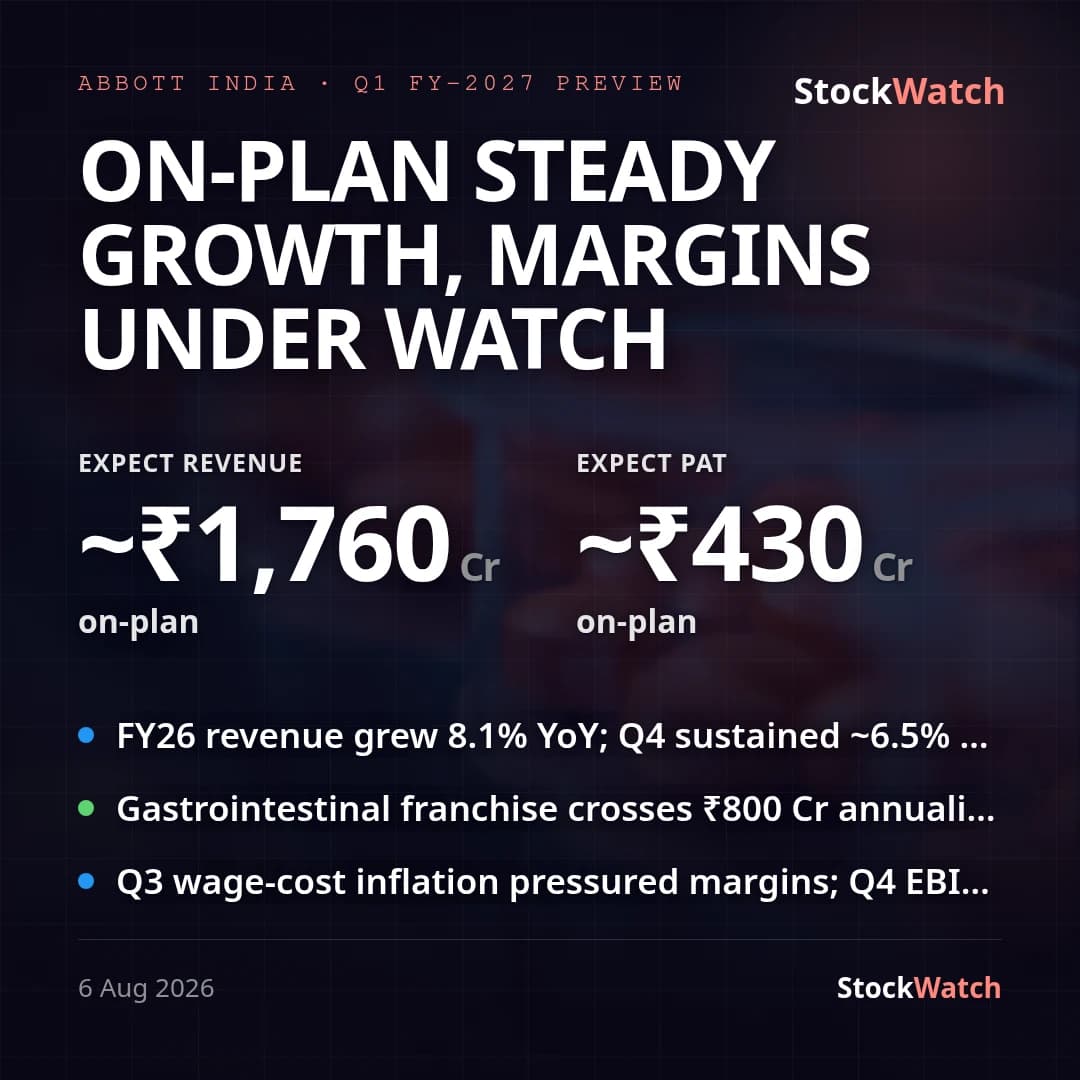
Abbott India Q1 FY27: standalone PAT up 17% YoY on margin expansion, revenue growth muted at 4%
Abbott India's standalone Q1 FY27 (quarter ended June 30, 2026) print was a margin-led beat: revenue from operations grew a modest 4.3% YoY to ₹1,813.68 Cr (up 6.1% QoQ from ₹1,709.51 Cr), while profit after tax rose a sharper 17.1% YoY to ₹428.52 Cr (up 8.5% QoQ from ₹394.93 Cr), with EPS at ₹201.65 versus ₹172.17 a year ago. No exceptional or one-off items are visible in either the current or comparison periods, so the growth is organic — there is no raw-vs-adjusted split to make here.
The gap between top-line and bottom-line growth is entirely a margin story. EBITDA-level operating margin (PBT + finance costs + depreciation, less other income, over revenue) expanded to 28.81% from 25.63% a year ago (+318 bps) and 28.13% last quarter (+68 bps); net margin on total income rose to 22.69% from 20.20% YoY (+249 bps). Cost of materials consumed fell to ₹150.63 Cr from ₹146.18 Cr a year ago as a share of a larger revenue base, and employee benefits expense actually declined YoY to ₹175.24 Cr from ₹168.01 Cr's prior-year base growing slower than revenue, while the tax rate held steady at 25.1% of PBT versus 25.7% a year ago — none of these individually stand out as one-offs, suggesting genuine operating leverage rather than a cost-line anomaly.
We have no prior guidance or concall commentary on record for this company to check the print against, and management's press release/results commentary was not available at extraction time, so neither can be graded here. A web search for Street consensus on this quarter turned up no specific analyst estimates for Abbott India's Q1 FY27 PAT or revenue, so the print cannot be benchmarked against consensus either — vsStreet is marked unknown rather than guessed. Alongside the results, the board also approved a leadership transition: Sudarshan Jain succeeds Munir Shaikh as Chairman effective August 13, 2026, a governance change that is unrelated to the quarter's numbers but was disclosed in the same filing.
Going into Q2 FY27, the key question is whether the ~29% OPM level holds as a new run-rate or reverts toward the 25-26% band seen a year ago, and whether revenue growth — running below double digits for two straight quarters — reaccelerates.