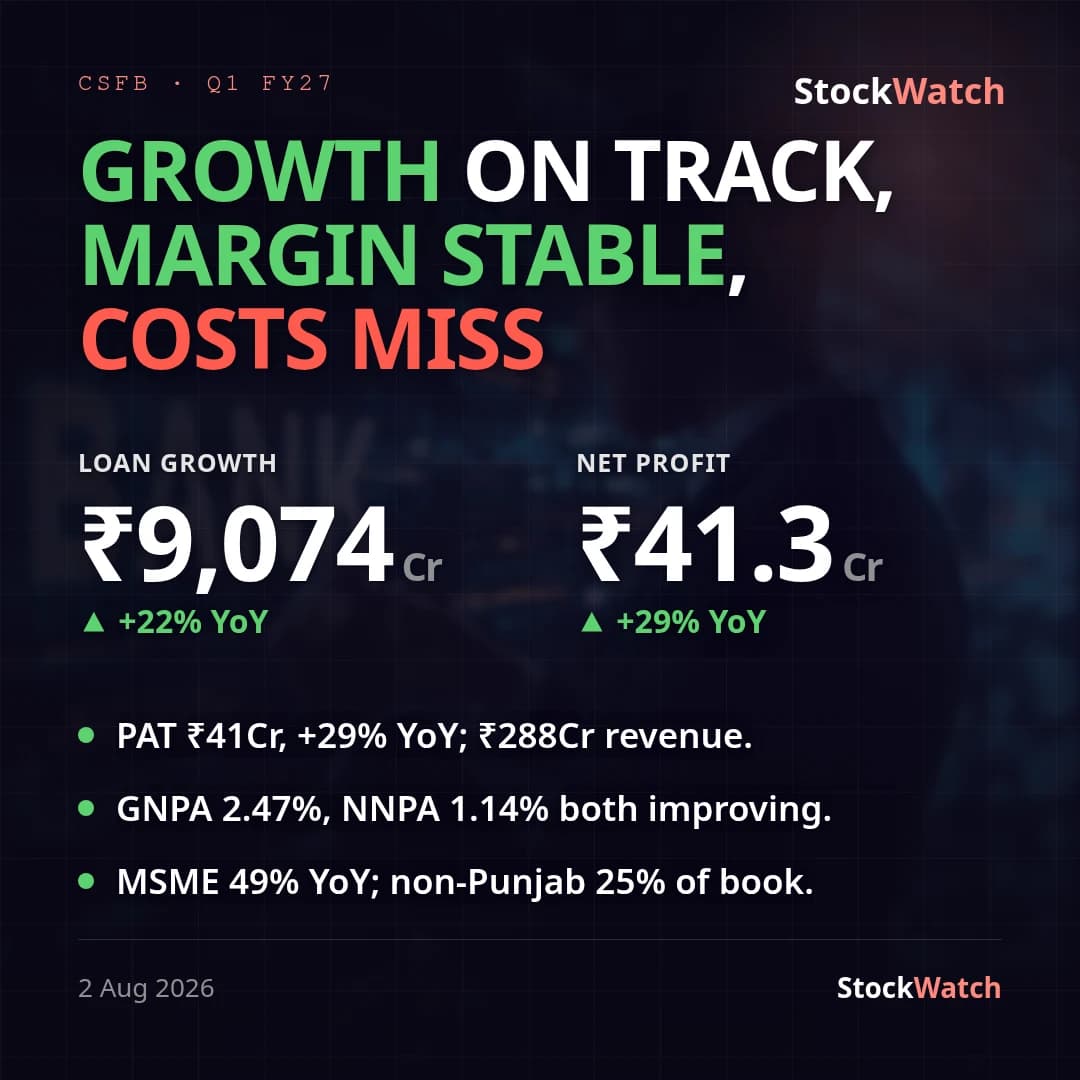
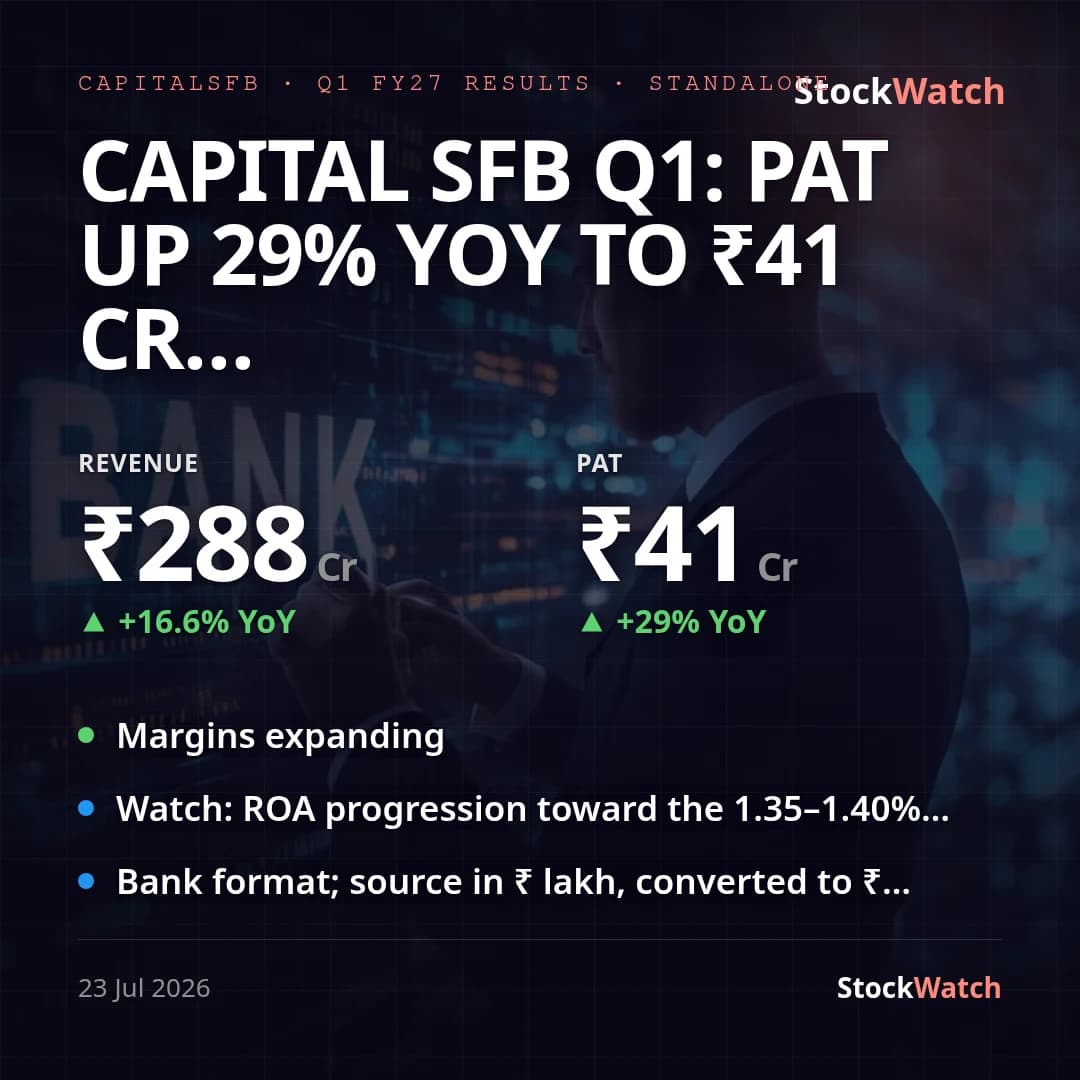
Capital Small Finance Bank opened FY27 with a clean, broad-based beat on its own operating trajectory: standalone Q1 PAT rose 29.0% YoY to ₹41.30 Cr (₹32.01 Cr a year ago), outpacing 16.6% growth in interest income to ₹288.18 Cr and lifting net profit margin to 13.14% from 11.86% a year earlier. There were no exceptional items on either side of the comparison, so the reported growth is the underlying growth — a straightforward operating result rather than an accounting artifact. Sequentially the print was steadier (PAT +3.0% over Q4FY26's ₹40.08 Cr), which is normal for a bank without seasonal quarters; the YoY line is the real signal here.
The margin story is the driver. NIM expanded to 4.21% (from 4.06% both a year ago and in Q4FY26) as cost of deposits fell to 5.6% from 5.9% YoY, consistent with management's Q4 concall guidance that repricing of high-cost term deposits and an improving credit-deposit ratio (avg CD ratio up to 83.0% from 80.9%) would lift margins. Net interest income grew 22% YoY to ₹134 Cr and pre-provision operating profit rose 23% to ₹65 Cr; operating margin improved to 2.04% from 1.94%. Fee/other income was the softer line, up only ~13% to ₹26.12 Cr, and the cost-to-income ratio ticked up to 59.5% from 58.2% in Q4, so the profit uplift is being carried by the spread, not by operating leverage or non-interest income.
On the balance sheet, gross advances grew 22.0% YoY to ₹9,074 Cr — squarely on the '22%+ FY27 loan-book' guidance — led by the MSME/business segment (+49% YoY, +11% QoQ), while deposits rose 16.3% to ₹10,596 Cr with CASA at 36.7%. Asset quality improved: GNPA 2.47% (from 2.75% YoY / 2.54% QoQ), NNPA 1.14%, PCR up to 54.51% from 51.89%, with credit cost contained at 0.31%. ROA at 1.30% (vs 1.18% YoY) is tracking toward but still short of the 1.35–1.40% FY27 target management set, and ROE improved to 11.20% from 9.43%. This was an unaudited result with an unmodified limited review by new statutory auditor GSA & Associates LLP; the board also paid the ₹5/share FY26 final dividend during the quarter. There is no meaningful street consensus for a bank this size, so the result is best read against management's own guidance — which it broadly met on growth, margins and asset quality.