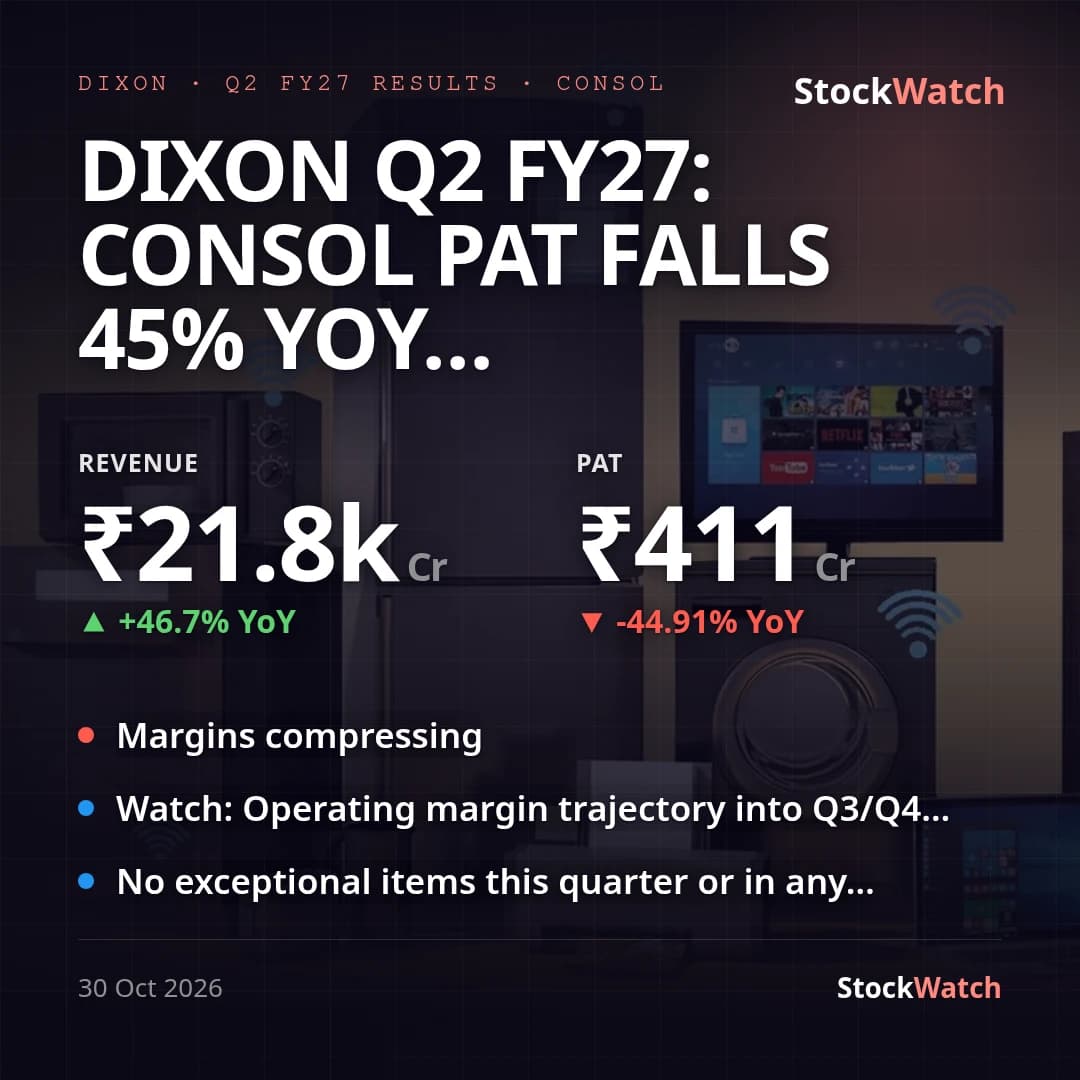
Dixon Q2 FY27: consol PAT falls 45% YoY to ₹411 Cr as margins compress on 47% revenue jump
Dixon Technologies' consolidated PAT fell 44.9% YoY to ₹410.87 Cr in Q2 FY27 (-42.8% QoQ) even as consolidated revenue from operations surged 46.7% YoY to ₹21,793.64 Cr (+40.2% QoQ) — a clean topline beat paired with a sharp bottom-line miss. Net profit margin compressed to 1.88% from 4.86% a year ago (4.47% last quarter), and core operating margin fell to roughly 2.75% from 3.78% YoY (2.98% QoQ). Basic consolidated EPS was ₹67.44 against ₹123.60 a year ago. No exceptional items appear in the current or comparison quarters, so these are raw, like-for-like swings, not accounting noise.
The compression traces to continuing mix shift toward lower-margin mobile/EMS manufacturing, which now drives the bulk of group growth — consolidated revenue grew more than three times faster than the parent entity's own book. Standalone (parent-only) revenue rose just 15.0% YoY to ₹1,593.15 Cr, while standalone PAT collapsed 74.2% YoY to ₹123.44 Cr, a far steeper drop than the consolidated figure. Readers comparing the two should treat consolidated as the primary number, since nearly all of Dixon's growth and margin dynamics now sit inside subsidiaries and joint ventures (Padget, Ismartu, and the newer telecom/display units).
Revenue is running well ahead of management's own FY27 guidance of roughly ₹56,000 Cr (15-17% growth) — H1 FY27 consolidated revenue of ₹37,341.30 Cr is already up 34.9% YoY. Margins, however, behaved largely as flagged on the Q1 FY27 call: management said explicitly that no margin recovery was expected in FY27, with improvement only from FY28 as display and camera-module production ramps — this quarter's margin decline is consistent with, if a touch sharper than, that warning. No reliable third-party consensus estimate specific to this quarter surfaced in available sources, so the print cannot be scored against Street with confidence; vsStreet is marked unknown rather than guessed. Management did not issue a separate results press release beyond the board-outcome filing, which itself flagged the quarter's headline swings (revenue +42% YoY on the company's own total-income basis, EBITDA -37%, PBT -42%, PAT -45%) without further commentary. Corporate activity this quarter leaned toward continued diversification rather than cost control: a new JV with Gemtek for telecom products (Oct 7), a subsidiary's licence for microwave-radio manufacturing IP (Sep 30), and a $7 million guarantee extended to subsidiary Padget Electronics (Oct 21) — all consistent with the stated FY27 telecom target of ₹6,700-7,000 Cr. The board also appointed Prithvi Vachani, the Executive Chairman's son, as Executive Director for five years alongside the results, a governance item unrelated to the quarter's financial performance.
Going into Q3 FY27, the key question is whether operating margin stabilizes near current levels (roughly 2.75-3%) or deteriorates further as mobile/EMS mix keeps rising, and whether the ₹1,110.06 Cr PLI incentive accrued by one subsidiary — still pending formal PMA determination per Note 6 — gets resolved, since it remains an unrecognised swing factor sitting outside this quarter's P&L.