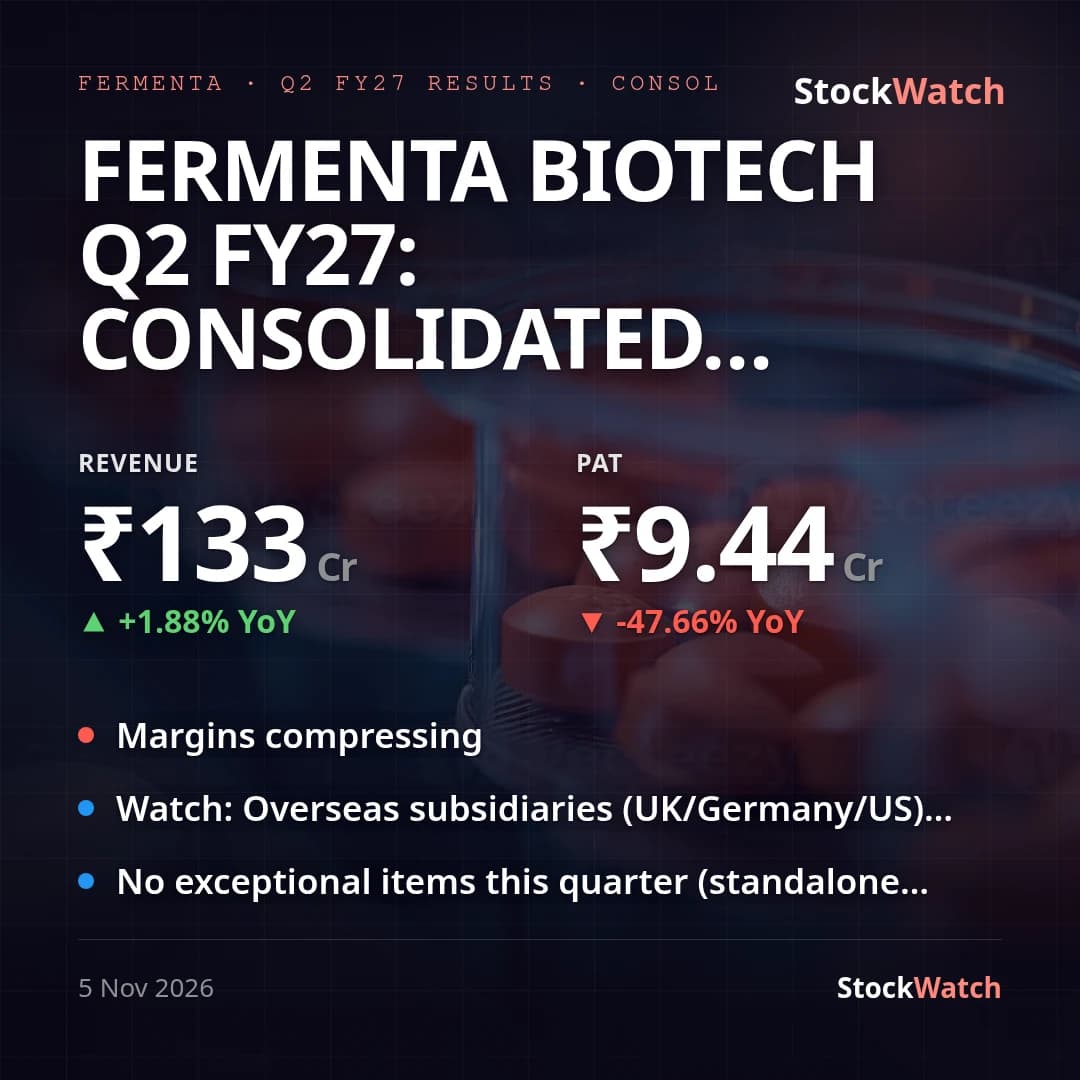
Fermenta Biotech's consolidated (primary basis) PAT fell 47.7% YoY to ₹9.44 Cr even as consolidated revenue was nearly flat, up just 1.9% YoY to ₹132.67 Cr from ₹130.22 Cr — profit growth trailed revenue growth by a wide margin, and NPM compressed to 6.95% from 13.29% a year ago (also down from 7.55% in Q1 FY27). Standalone (secondary basis) tells a materially milder story: standalone PAT fell only 5.2% YoY to ₹13.95 Cr on 9.2% YoY revenue growth to ₹116.94 Cr, a >40-percentage-point gap in PAT growth versus the consolidated print. Readers comparing the two numbers should not assume either is wrong — the divergence is explained below.
The margin squeeze sits mainly below the core operating line: the core bulk drugs/chemicals segment, which is the real operating engine, saw its segment profit fall 28.5% YoY to ₹18.98 Cr (from ₹26.55 Cr) even as segment revenue rose, implying cost pressure within the core business itself. On top of that, the company's three overseas units (UK, Germany, US) swung to a combined ₹2.71 Cr net loss this quarter per the statutory auditor's review note — a drag that doesn't show up in the standalone numbers — while the Environment segment (housed in subsidiary FESPL) added a further ₹1.76 Cr segment loss, narrower than Q1's ₹2.71 Cr loss but still a drag. Finance costs rose to ₹3.73 Cr from ₹2.58 Cr a year ago, adding to the pressure. Operating margin (profit before tax and finance cost over revenue from operations) eased to roughly 13.6% from about 20.5% YoY.
There is no formal management guidance on record for this quarter — neither in our database nor in the filing itself — and no management press release was available to extract commentary from, so there is nothing from the company to grade this print against. A web search for analyst/consensus estimates ahead of this result found none specific to Fermenta Biotech's Q2 FY27 (results were approved and released the same day as the search, and the stock has thin formal sell-side coverage), so vsStreet is unknown rather than assumed. Sequentially, revenue grew 8.9% QoQ to ₹132.67 Cr but PAT was essentially flat, down 1.0% QoQ to ₹9.44 Cr from ₹9.53 Cr, consistent with a business where topline recovery hasn't yet translated into profit recovery. Separately, during the quarter promoter-linked holder Preeti Thakkar sold a 3.96% stake (Sep 30, 2026) and the company licensed Vitamin B12 fortification technology from VIT (Sep 8, 2026) — a core-segment initiative with no quantifiable revenue impact yet disclosed — while subsidiary FESPL raised ₹21.53 lakh via a private placement and set up an ESOP pool, developments relevant to the Environment segment's capital base rather than this quarter's P&L.