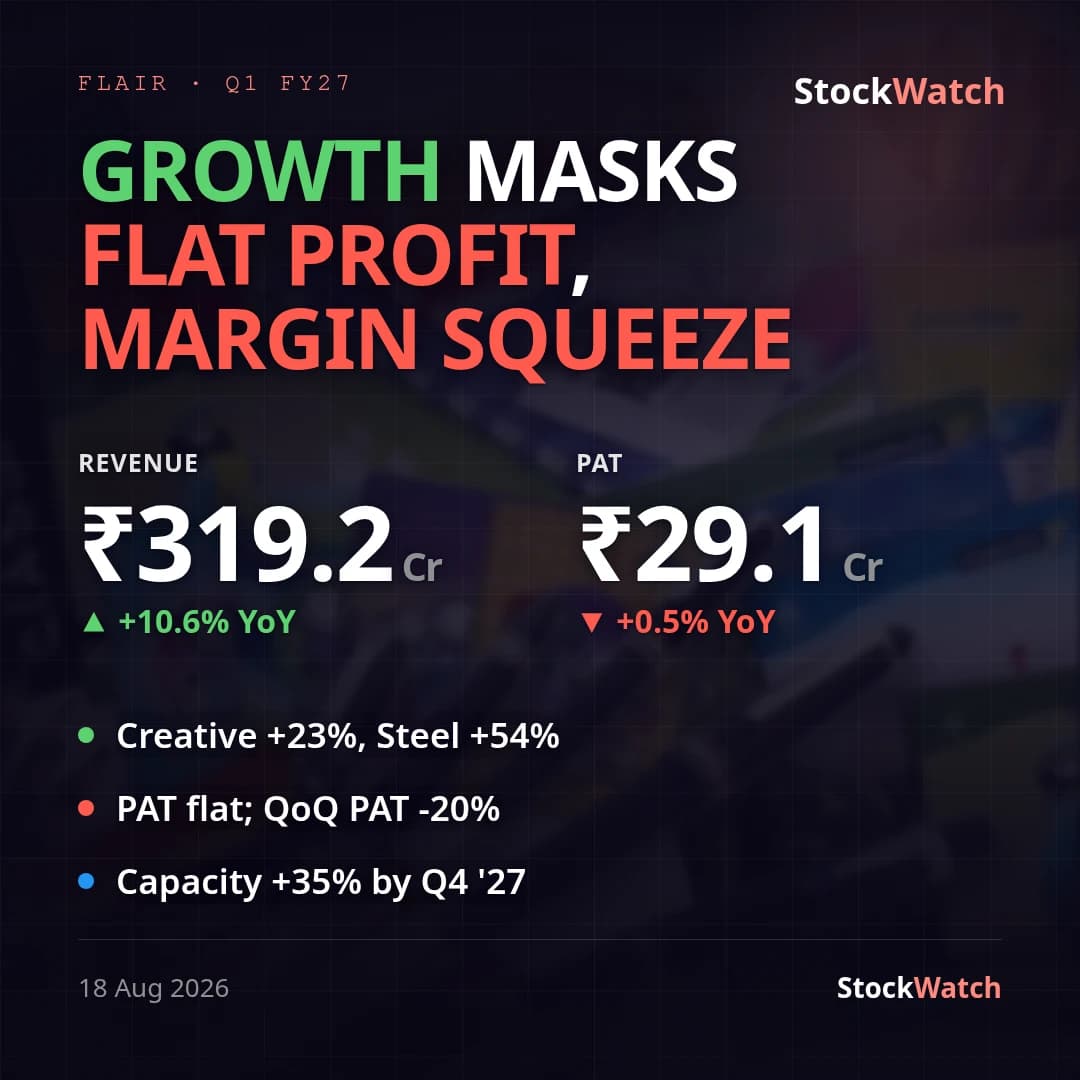
Flair Q1 FY27: consolidated PAT flat YoY at ₹29 Cr as RM-cost squeeze compresses margins
Flair Writing's consolidated Q1 FY27 revenue rose 10.6% YoY to ₹319.25 Cr, but PAT was effectively flat YoY at ₹29.08 Cr (+0.5%), and fell 20.4% QoQ from Q4 FY26's seasonally stronger ₹36.52 Cr. Consolidated basic EPS came in at ₹2.71, barely changed from ₹2.72 a year ago. There is no formal Street estimate available for this specific quarter in our records or via search, so vsStreet is unknown; broader FY27 sell-side commentary points to ~9-20% full-year PAT growth expectations (sources vary), against which a flat opening quarter is a soft start.
The squeeze sits on the cost-of-materials line, exactly where management flagged it on the Q4 FY26 call: consolidated OPM compressed to 16.71% from 17.17% YoY (and down from 17.87% QoQ), and NPM eased to 9.08% from 9.92% YoY, consistent with the ~13% raw-material cost increase (crude-linked) management had guided for this quarter. Revenue growth of 10.6% YoY also trails the company's stated FY27 topline guidance of ~15%, though three quarters remain to close that gap, and management's planned mitigation — price increases and scheme rationalisation, especially in Steelware — had not yet fully offset the hit in this print.
The basis matters here: standalone (parent-only) results were materially weaker than the consolidated number, a divergence beyond the 3% threshold worth flagging on its own. Standalone revenue grew a slower 6.5% YoY to ₹258.05 Cr, while standalone PAT fell 8.8% YoY to ₹24.76 Cr and standalone OPM dropped sharply to 14.02% from 15.67% YoY (-165 bps, versus -46 bps at the consolidated level). That gap indicates the parent entity absorbed most of the raw-material cost pressure while subsidiaries cushioned the group print — consistent with a subsidiary ordering a fourth stainless-steel bottle production line this quarter, tying to management's FY27 guidance of ~40% growth in the Steel Bottles segment as a newer, higher-growth offset to the core pens/stationery business. No management press release commentary was available in the context to cross-check against these numbers this cycle.
Going into Q2, the print sets up two things to watch: whether the guided price increases restore consolidated OPM toward the 17-19% (targeted ~18%) FY27 band, and whether the standalone-consolidated gap narrows as the steel-bottle capacity addition scales.