HDB Financial Q1: standalone PAT up 38% YoY to ₹785 Cr as credit costs ease, margins widen
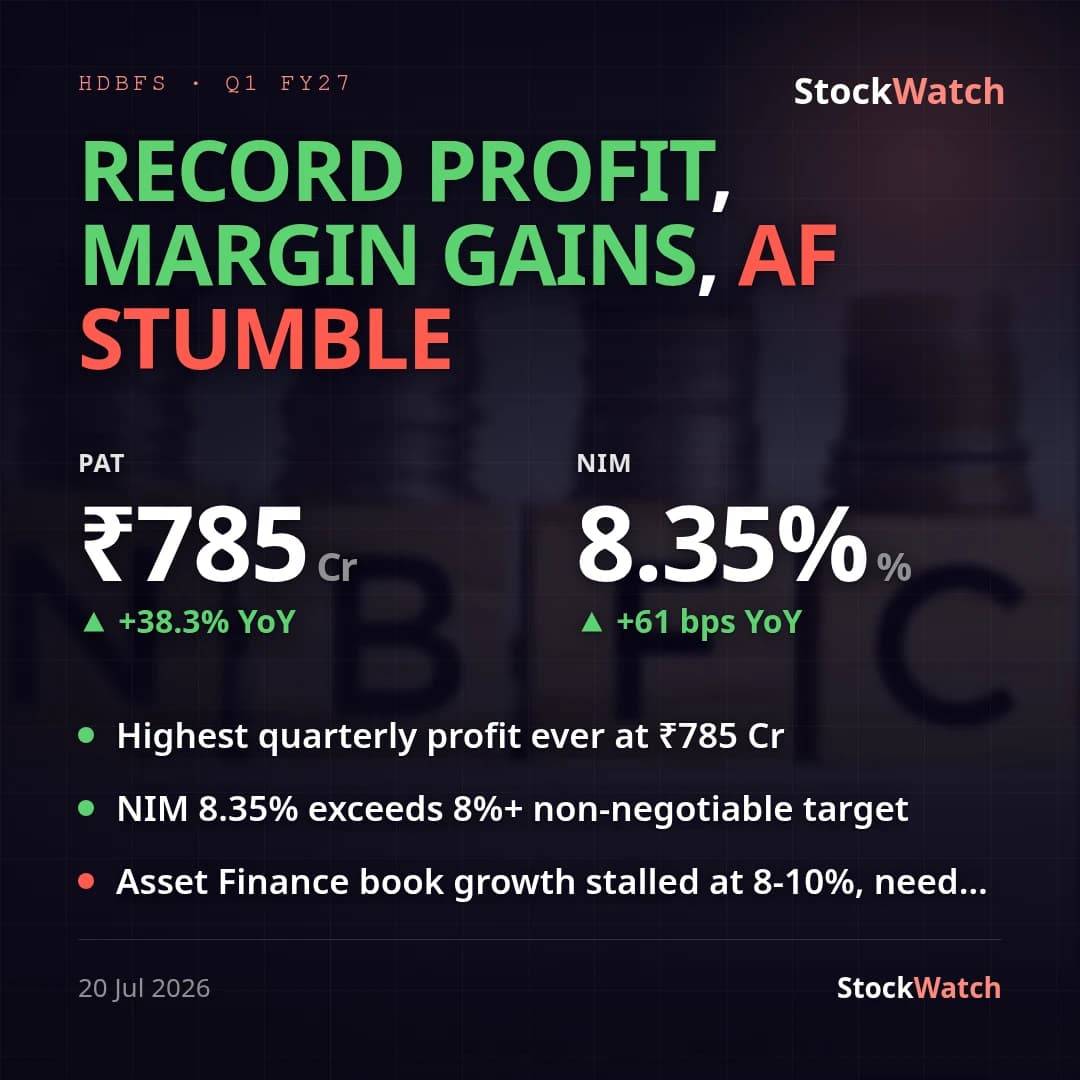
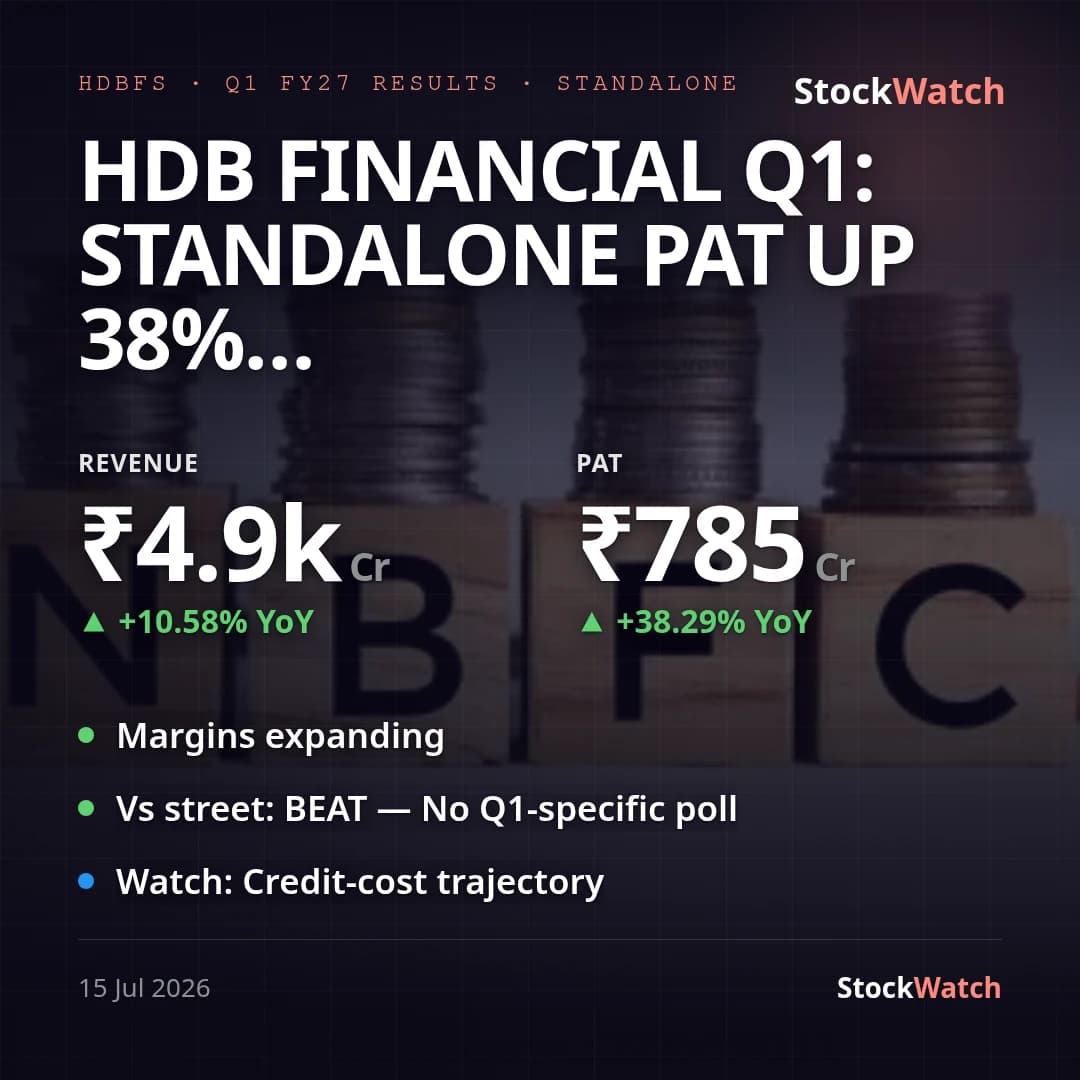
HDB Financial Services opened FY27 with a standalone net profit of ₹785.2 Cr, up 38.3% YoY (and 4.6% QoQ), on revenue from operations of ₹4,937.9 Cr that grew a more modest 10.6% YoY. The gap between the two is the entire story: this was a profitability quarter, not a growth quarter. Profit before tax rose 44% YoY to ₹1,055.1 Cr because total expenses climbed only 4% against the 10.6% topline, and net profit margin expanded to 15.90% from 12.72% a year ago (15.82% in Q4). The one-off worth flagging is on the base, not this quarter — Q1 FY26 tax carried a ₹26.7 Cr 'earlier-year' credit; strip it out and underlying PAT growth is nearer ~45% YoY, so the reported +38% if anything understates the operating improvement. EPS was ₹9.46 versus ₹7.13.
The margin bridge sits on two lines. Impairment of financial instruments — the credit-cost line for an NBFC — rose just 4% YoY to ₹697.1 Cr even as the loan book grew, and asset quality improved with Gross Stage 3 easing to 2.34% (from 2.56% YoY) and Net Stage 3 at 1.04%. Finance costs were essentially flat at ₹1,753.3 Cr despite the company allotting well over ₹2,000 Cr of NCDs during the quarter (and much larger tranches around it, including ₹15,500 Cr and ₹5,050 Cr issues in June per the event record), pointing to a stable-to-lower cost of funds. Segment results confirm the read: the lending business delivered PBT of ₹1,045.1 Cr (up from ₹733.6 Cr) while BPO services added ₹26.0 Cr.
Against management's own framing from the Q4 concall — credit costs moderating to ~2.3%, NIM held above 8% as 'non-negotiable', and AUM growth at nominal GDP + 6-7% — this print is on-track to confirmatory: the annualised credit-cost run-rate (~2.4%) and the improving Stage 3 ratios line up with the guidance, and margin expansion is consistent with the NIM stance, though the filing does not disclose NIM directly to verify the >8% claim. On the street, there is no published Q1-specific consensus for this recently-listed name; the available analyst view frames FY27 as 15-20% PAT growth, and a +38% (~45% adjusted) YoY start runs ahead of that pace. Capital and liquidity remain ample (CAR 21.29%, LCR 159%, net worth ₹20,332 Cr). The board also noted a director ceasing office on term completion (July 14) — governance housekeeping, not tied to the numbers.