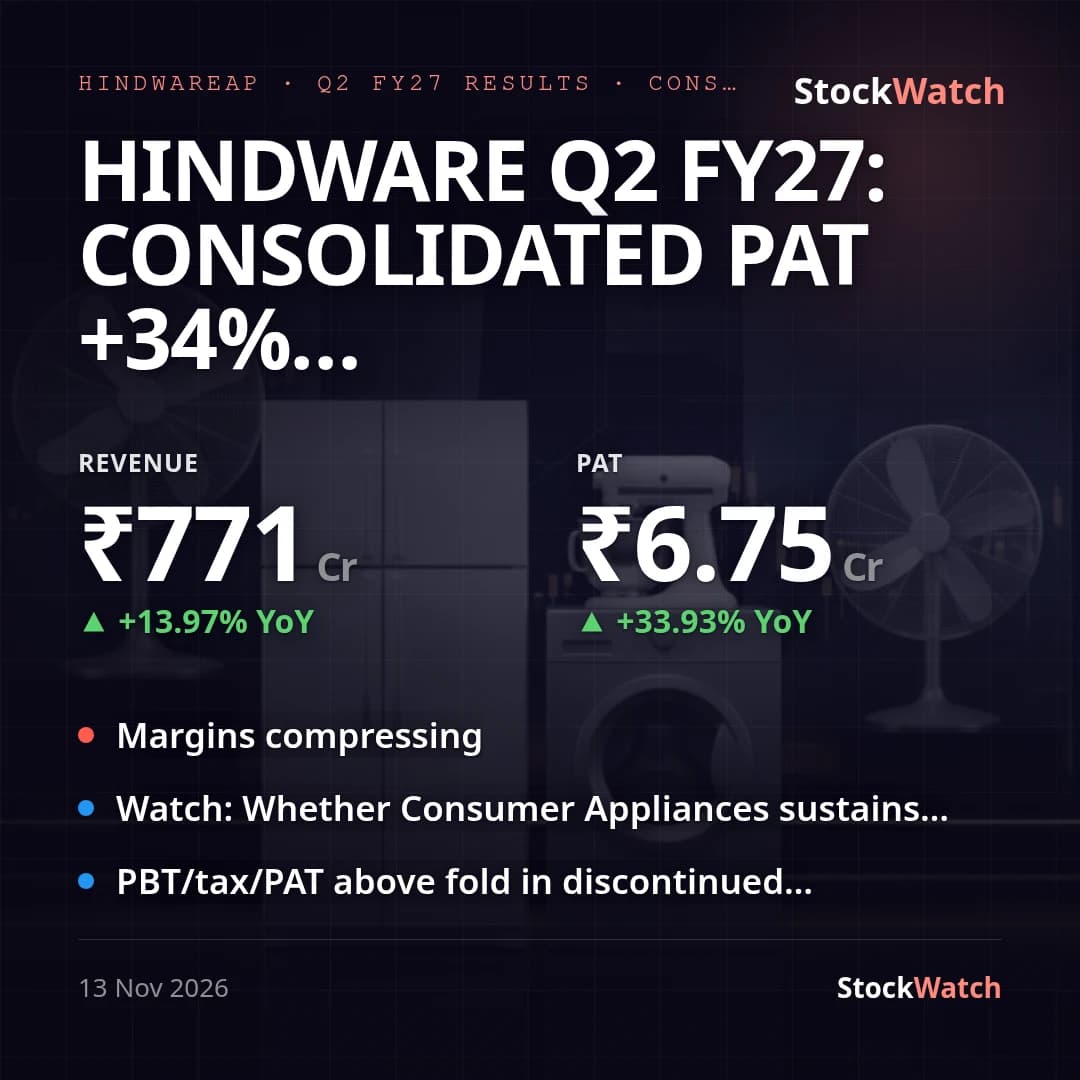
Hindware Q2 FY27: consolidated PAT +34% YoY, but core profit falls on margin squeeze
Hindware Home Innovation's consolidated Q2 FY27 (quarter ended 30 September 2026) results show revenue of ₹770.82 Cr, up 13.97% YoY (₹676.31 Cr) and 23.3% QoQ (₹625.25 Cr) — the QoQ jump is largely seasonal, as the second half is typically stronger for bathware/building products. Consolidated PAT came in at ₹6.75 Cr, up 33.9% YoY (₹5.04 Cr) and 54.5% QoQ (₹4.37 Cr), with EPS of ₹0.79 versus ₹0.59 a year ago. But the headline PAT growth overstates the quarter: core pre-exceptional PBT from continuing operations fell 37.5% YoY to ₹8.81 Cr from ₹14.10 Cr, and once one-off swings are stripped out — a prior-year ₹3.22 Cr joint-venture loss that didn't recur, plus the effective tax rate dropping to roughly 26% from 44% — adjusted PAT is actually down about 12% YoY, not up 34%.
The weakness sits on the EBITDA line: consolidated EBITDA margin compressed to about 7.3% from 8.9% a year ago and from roughly 8.6% last quarter. Segment-wise, Consumer Appliances slipped back into a ₹1.72 Cr segment loss (versus a ₹2.77 Cr profit a year ago) — just one quarter after narrowly turning EBITDA-positive in Q1 FY27 (segment result ₹0.34 Cr) — missing the trajectory management had set out toward an 8-10% EBITDA margin by FY27-28. Building Products, the segment closest to the guided "Bathware business," grew revenue 12.65% YoY (14.75% in H1) to ₹667.09 Cr, below the 15-20% FY27 growth management guided last concall, with segment result nearly flat (₹28.25 Cr vs ₹28.70 Cr) — margin compression rather than the "expected improvement" management had flagged. Hintastica (HPL), previously a 50:50 joint venture, became a wholly owned subsidiary on 4 June 2026 and is now fully consolidated, which is why the JV-loss volatility that hurt last year's quarter is absent this time; a ₹0.83 Cr reversal of an HPL impairment was booked as an exceptional gain in Q1 FY27, versus nil exceptional items this quarter.
No quarter-specific Street estimates for Q2 FY27 were found (results were announced same-day, 13 November 2026); pre-print FY27 consensus had pegged full-year revenue growth near 17% and EPS around ₹9.50 — H1 FY27 revenue growth of 15.6% YoY is tracking close to, but still below, that pace. Against management's own prior guidance (May 2026 concall: 15-20% Bathware revenue growth, Consumer Appliances EBITDA-positive in Q1 FY27 building to 8-10% margins by FY27-28, 14-15% Pipes volume growth, and 1.5-2% annual consolidated margin expansion alongside 30-40% debt reduction over two years), this quarter reads as a miss — margins compressed rather than expanded, and Consumer Appliances reversed its narrow Q1 turn to profitability. No management press release commentary was available alongside this filing. The quarter also coincided with a full leadership turnover — CEO, CFO and Company Secretary all resigned and transferred to a subsidiary on 4 November 2026, with the board promoting internal replacements (Nitesh Raj as CEO, Amit Bali as CFO, Kushal Jain as CS) effective the same day as this result, 13 November 2026 — alongside confirmation that the NCLT (Kolkata bench) sanctioned the Composite Scheme of Arrangement on 14 October 2026 (certified order received 6 November 2026, not yet effective), which will demerge the Consumer Products business into HHIL and amalgamate the Building Products business into Hindware Limited. These results do not yet reflect that scheme.