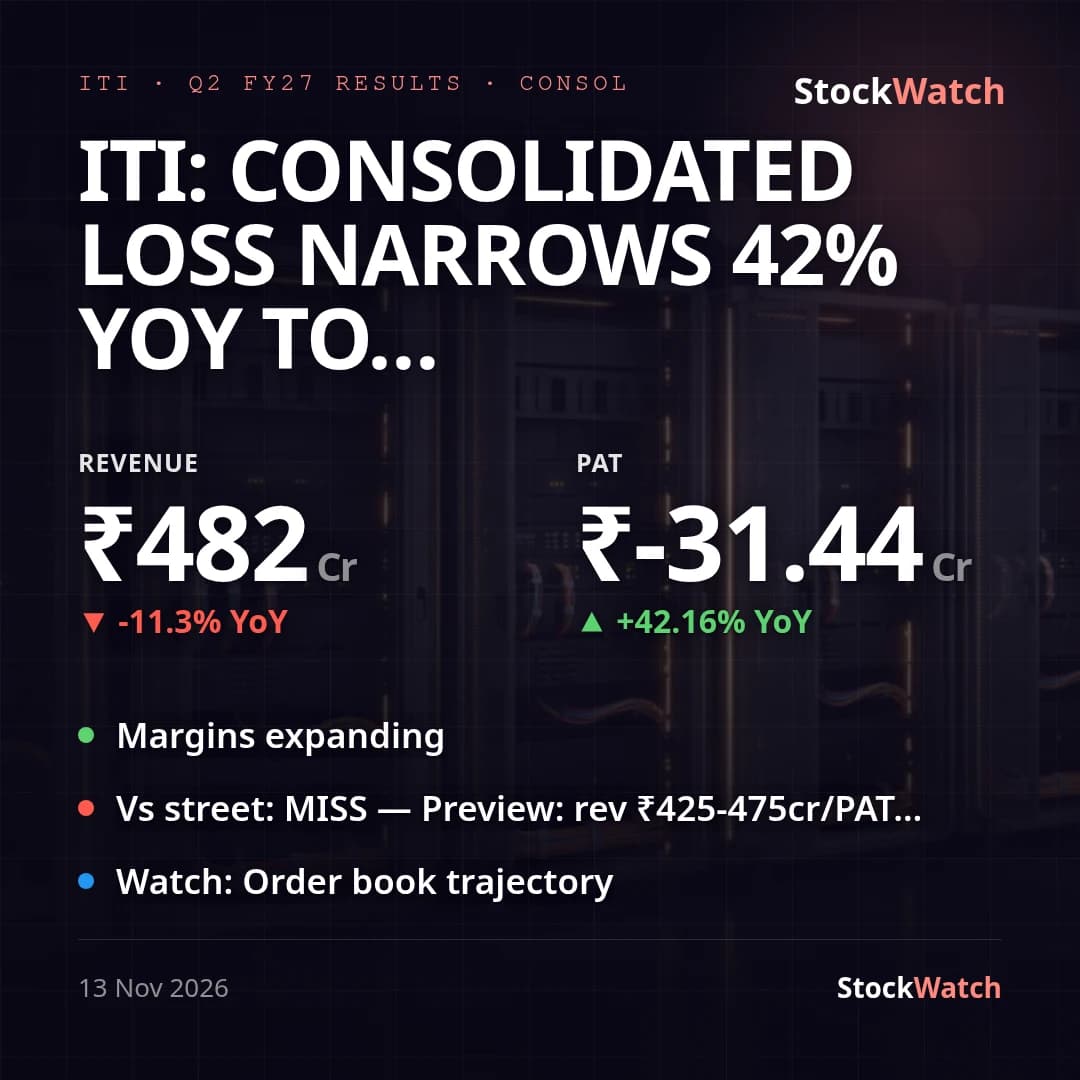
ITI: consolidated loss narrows 42% YoY to ₹31.4 Cr as revenue falls 11.3% to ₹482 Cr
ITI Limited's consolidated net loss narrowed to ₹31.44 Cr in Q2 FY27 from ₹54.35 Cr a year ago — a 42.2% YoY improvement — even as revenue fell 11.3% YoY to ₹481.99 Cr from ₹543.40 Cr. Our pre-result preview had flagged a Street consensus betting on FY27 PAT growth to ₹350+ Cr while bracing for a more modest ~₹20–50 Cr Q2 print and revenue of ₹425–475 Cr; the actual revenue of ₹481.99 Cr came in just above that band (a mild beat), but the quarter stayed a loss-making one, missing even the preview's cautious profit floor — vindicating the preview's skepticism of the Street's bullish framing over the raw YoY improvement. Sequentially, revenue rose 13.4% QoQ from ₹425.03 Cr (Q1 FY27), but the bottom line barely moved — the loss narrowed only 2.5% QoQ, from ₹32.25 Cr to ₹31.44 Cr — so the QoQ pickup in billing has not yet translated into a comparable profitability gain.
On margins, net loss as a share of revenue improved both YoY (-9.74% to -6.35% NPM, per our tracked metric) and QoQ (-7.44% to -6.35%), driven mainly by the lower revenue base a year ago rather than cost control: the pre-exceptional operating loss (total income ₹495.28 Cr less total expenses ₹527.83 Cr) was ₹32.55 Cr this quarter, actually ₹0.22 Cr wider than Q1 FY27's ₹32.33 Cr, even though it is ₹19.98 Cr narrower than Q2 FY26's ₹52.53 Cr. Adjusting for the small exceptional items on both sides (₹0.87 Cr gain now vs ₹1.71 Cr loss a year ago), the underlying YoY loss-narrowing works out to roughly 38.6%, close to the 42.2% reported figure — the exceptional items are immaterial to the overall picture. Management has not issued any formal guidance or outlook on record, so there is no guidance line to grade this print against; no management press release or commentary accompanying this filing was available to cross-check against the numbers.
Corporate context ties into the print: ITI continues to operate under its BIFR-era revival plan, having received ₹3,084.35 Cr of the CCEA-approved ₹4,156.79 Cr financial-assistance package to date (per the filing's note 3). The standalone order book stood at ₹18,220.53 Cr as of September 30, 2026 — below the ~₹18,600+ Cr level flagged pre-result — against unbilled revenue of ₹2,408.46 Cr, and the company continues to execute the ₹8,280.36 Cr ASCON Phase IV telecom-network contract signed with the Ministry of Defence in October 2020. The filing itself carries no disclosure on the BSNL 4G West Zone order flow that was a specific pre-result watch item, so that catalyst remains untested by this quarter's numbers.
Going into Q3 FY27, the setup is: a loss that is narrowing meaningfully YoY but essentially flat QoQ, a pre-exceptional operating loss that actually widened slightly sequentially, and an order book trending below the level the Street had priced in — all against a company still dependent on government revival funding rather than organic profitability.