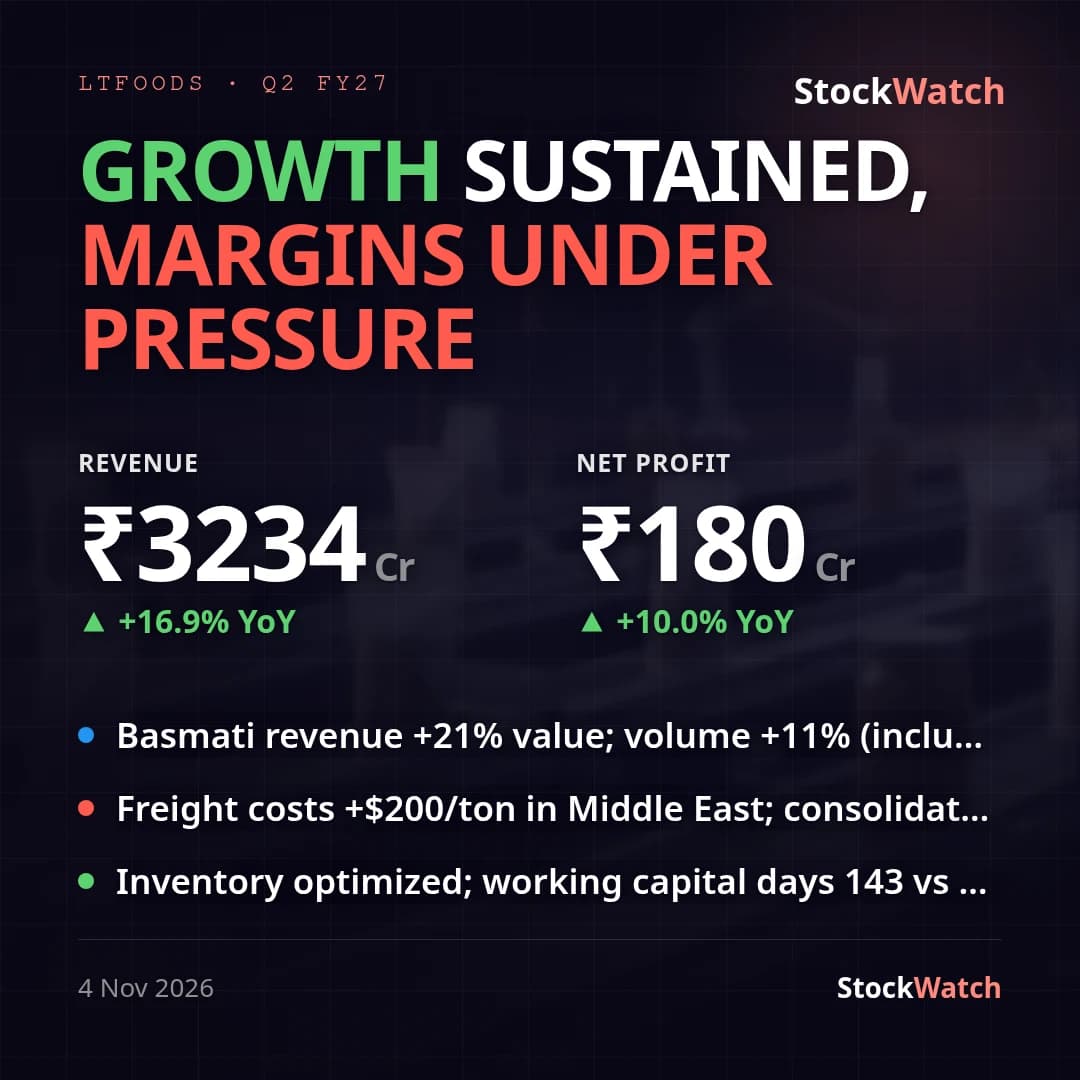
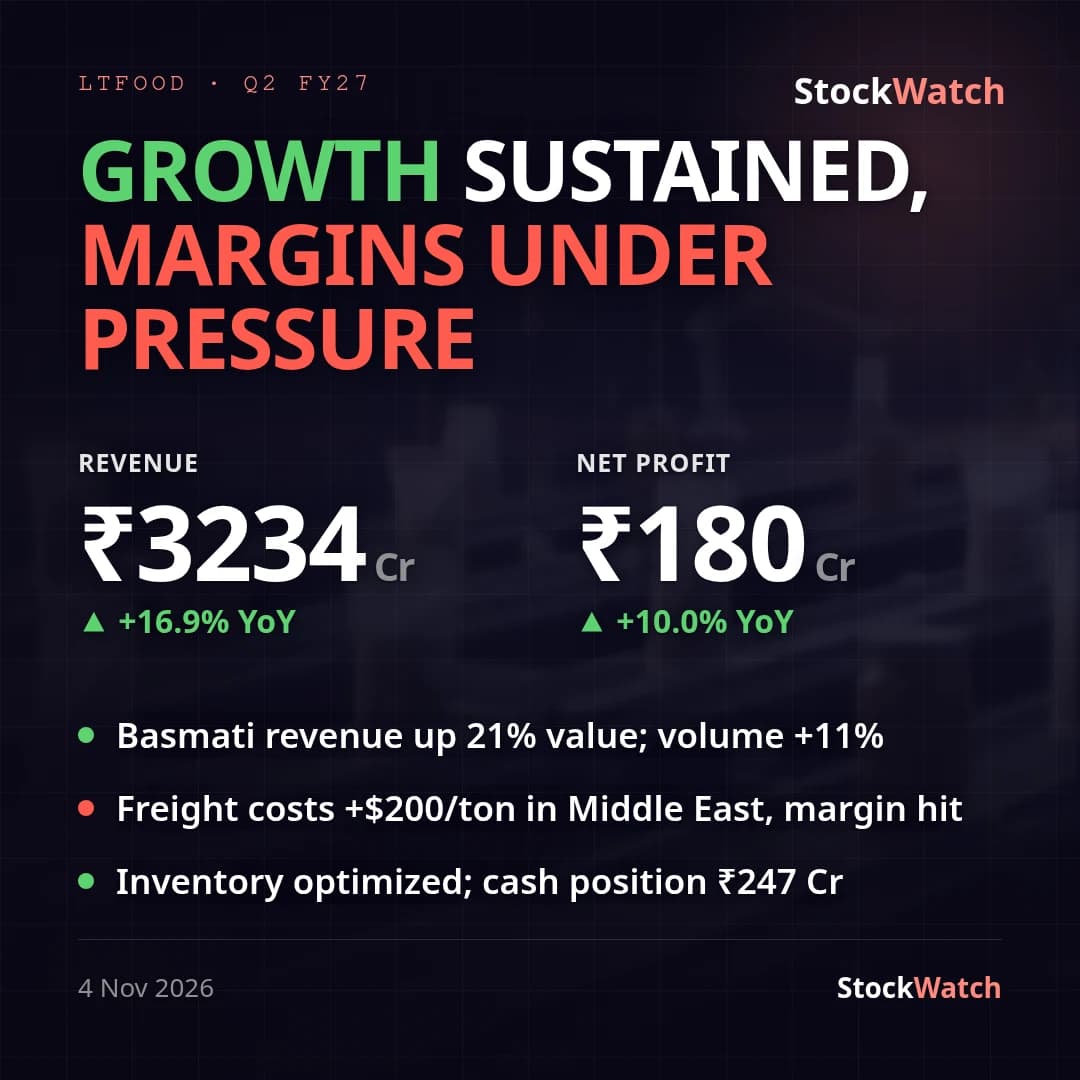
LT Foods Q2FY27: PAT +10% YoY to ₹180 Cr as margins compress on 17% revenue growth
LT Foods's consolidated (primary) PAT for Q2 FY27 rose 9.98% YoY to ₹180.20 Cr on revenue of ₹3,234.15 Cr, up 16.94% YoY — a quarter where topline growth held up but bottom-line growth lagged well behind it, the defining signal of the print. Sequentially, PAT actually slipped 1.77% QoQ (from ₹183.45 Cr) even as revenue rose 2.61% QoQ, reinforcing that this was a margin story rather than a demand one. No verified analyst consensus for this specific quarter turned up in a search of brokerage previews, so vs-Street is unknown; management gives no formal quarterly PAT/revenue guidance either — the closest reference points are the FY27 targets laid out on the August 2026 concall (core basmati 10–12% growth, RTH breakeven at ₹400 Cr revenue, organic EBITDA ₹70–80 Cr by FY27-end, Middle East +15%), none of which are verifiable against this filing since it carries no segment-level revenue or EBITDA breakout.
The compression sits on the cost-of-goods line. Combined material costs (raw material consumed, traded-goods purchases and inventory movement together) rose to 67.9% of consolidated revenue from 66.0% a year ago, pulling OPM down to 10.50% from 11.19% YoY (and from 11.23% last quarter) and NPM down to 5.57% from 5.91% YoY. Core operating profit — revenue less operating costs, stripped of other income and the associates/JV share — grew just 2.96% YoY versus 16.94% revenue growth, confirming the squeeze is real rather than a one-off; consolidated PBT (after the ₹0.80 Cr associates/JV share) grew 7.92% YoY to ₹247.26 Cr, with a slightly lower effective tax rate (27.1% vs 28.5% a year ago) supplying the extra points that got PAT to +9.98%.
The standalone (India) entity tells a sharper version of the same story with one added wrinkle: standalone PAT fell 10.15% YoY to ₹64.02 Cr and 8.75% QoQ, even though standalone revenue grew a healthy 19.13% YoY to ₹1,211.35 Cr. The decline is not an operating one — standalone operating profit (revenue less operating expenses, excluding other income) was actually up about 10% YoY — but other income, which includes dividend income from subsidiaries, dropped to ₹29.69 Cr from ₹40.32 Cr a year ago (H1 dividend income per the cash-flow statement fell to ₹21.90 Cr from ₹32.99 Cr), pulling standalone PBT down 7.23% YoY despite the operating improvement. Readers comparing standalone and consolidated prints should note this divergence — consolidated profit grew while standalone profit fell — almost entirely on dividend-income timing rather than the underlying India business weakening. Corporate developments this quarter include Leev.nu B.V. converting from joint venture to a first-time consolidated subsidiary (September 29, 2026) and the ongoing ₹134.10 Cr insurance-claim litigation at Daawat Foods, both disclosed in the notes but neither material to this quarter's P&L.
Against the confident, optimistic tone management struck on the August 2026 concall, the quarter delivers on the growth half (16.9% consolidated revenue growth sits at or above the ranges flagged then) but not on margins, which moved the wrong way both YoY and QoQ. The RTH breakeven and organic-EBITDA guidance checkpoints remain unverifiable from this filing pending segment disclosure, leaving material-cost pass-through as the clearest open question heading into H2 FY27.