StockWatch
·

NOCIL LTD.

BSE: 500730

P/L Snapshot

Q1 FY27 · standalone

vs Q4 FY26·vs Q1 FY26
Revenue
408.79
+18.3%+19.3%
Expenditure
372.31
+15.0%+16.2%
Net Profit
27.32
+51.4%+64.8%
OPM %
11.02%
+4.89pp+2.22pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
0.00114.46228.92343.38457.84Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27
Price Chart
Reports

Strong Beat Masks Volume Miss; Margin Moderation Flagged Ahead

earnings review · pricing power · volume miss

Result verdictFollow-upQ1 FY2717 Aug 20266 minMetals & Mining

Strong beat masks volume miss; margin moderation flagged ahead

EBITDA margin expansion · volume growth slowing · pricing power
TranscriptDeep diveQ1 FY2717 Aug 20266 minMetals & Mining

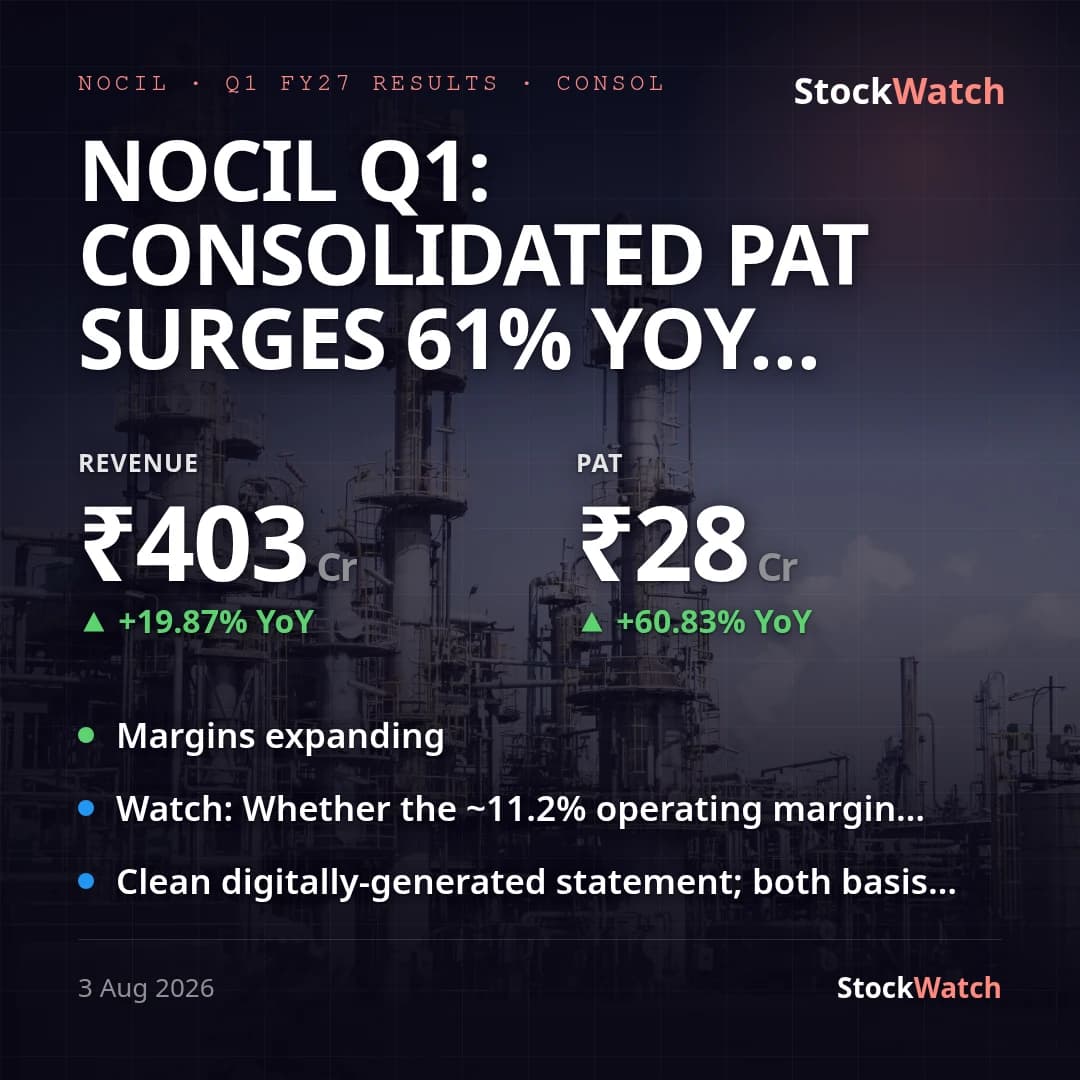
NOCIL Q1: consolidated PAT surges 61% YoY to ₹27.8 Cr on 20% revenue growth, margins widen

rubber chemicals · specialty chemicals · margin expansion

ResultsQ1 FY2703 Aug 20263 minMetals & Mining
Latest
Board Meeting3 Aug, 2:20 pm

NOCIL Q1: consolidated PAT surges 61% YoY to ₹27.8 Cr on 20% revenue growth, margins widen

NOCIL opened FY27 with a materially stronger print: consolidated revenue rose ~19.9% YoY to ₹403.02 Cr and net profit jumped ~60.8% to ₹27.76 Cr (EPS ₹1.66 vs ₹1.03), comfortably outpacing topline as operating margins expanded. Operating margin (OPM) widened to ~11.2% from ~9.1% a year ago and ~6.4% in the seasonally soft March quarter, driven by operating leverage on higher volumes and contained overheads (other expenses ₹102.66 Cr grew far slower than revenue). The profit growth is fully underlying — neither this quarter nor the year-ago Q1 carried any exceptional item, so the reported and adjusted YoY PAT growth are the same ~61%; the eye-catching +63% QoQ profit is flattered by a weak Q4 FY26 base and is supporting detail, not the headline. Standalone tells the same story (PAT ₹27.32 Cr, +64.8% YoY), with no material divergence from consolidated. Against management's own guidance from the Q4 concall — double-digit volume growth, Q4 treated as the new base, and ~150 bps EBITDA-margin improvement off FY26 — this quarter runs ahead: revenue is up ~22% on that Q4 base and margin expansion already exceeds the 150 bps target, suggesting the operating-leverage and price-hike thesis is playing through even as the final anti-dumping-duty decision remains pending. No formal Street consensus is on record for a company of this size, so the print cannot be graded against a published estimate. Note the concurrent corporate signals: a promoter pledge of 9 lakh shares (Aug 1) and the 64th AGM held alongside these results (Aug 3); a Q1 concall is scheduled for Aug 4, which should clarify volume trajectory and the margin outlook. No management press release accompanied the numbers.

3 Aug 2026, 02:20 pm

Corporate Events

Board MeetingNOCIL
2026
1Sep

Board Meeting

The Board of Directors approved the appointment of M/s Deloi…

BSE Filing
Board MeetingNOCIL
2026
3Aug

Board Meeting

The meeting of the Board of Directors is scheduled to consid…

BSE Filing
Board MeetingNOCIL
2026
7May

Board Meeting

To consider and approve audited standalone and consolidated …

BSE Filing
Board MeetingNOCIL
2026
11Feb

Board Meeting

Consider and approve Financial Results for the Quarter and n…

BSE Filing
Board MeetingNOCIL
2024
28Oct

Board Meeting

consider, approve and take on record the Un-Audited Standalo…

BSE Filing
Board MeetingNOCIL
2024
29May

Board Meeting

Consideration, Approval and Taking on record of Audited Stan…

BSE Filing
Board MeetingNOCIL
2024
7Feb

Board Meeting

Consider and approve un-audited standalone and consolidated …

BSE Filing
Board MeetingNOCIL
2023
2Nov

Board Meeting

Consideration and approval of Un-Audited Standalone and Cons…

BSE Filing