StockWatch
·

ORIENT GREEN POWER COMPANY LTD.

BSE: 533263

P/L Snapshot

Q1 FY27 · standalone

vs Q4 FY26·vs Q1 FY26
Revenue
8.69
-10.5%+0.1%
Expenditure
8.28
-13.9%+36.9%
Net Profit
0.40
+344.4%+114.4%
OPM %
-39.86%
+23.75pp-30.46pp

Shareholding

Pattern breakdown

P/L Trends

(in crores)

RevenueExpenditureNet Profit
-6.65-0.555.5511.6617.76Q2 FY25Q3 FY25Q4 FY25Q1 FY26Q2 FY26Q3 FY26Q4 FY26Q1 FY27
Price Chart
Reports

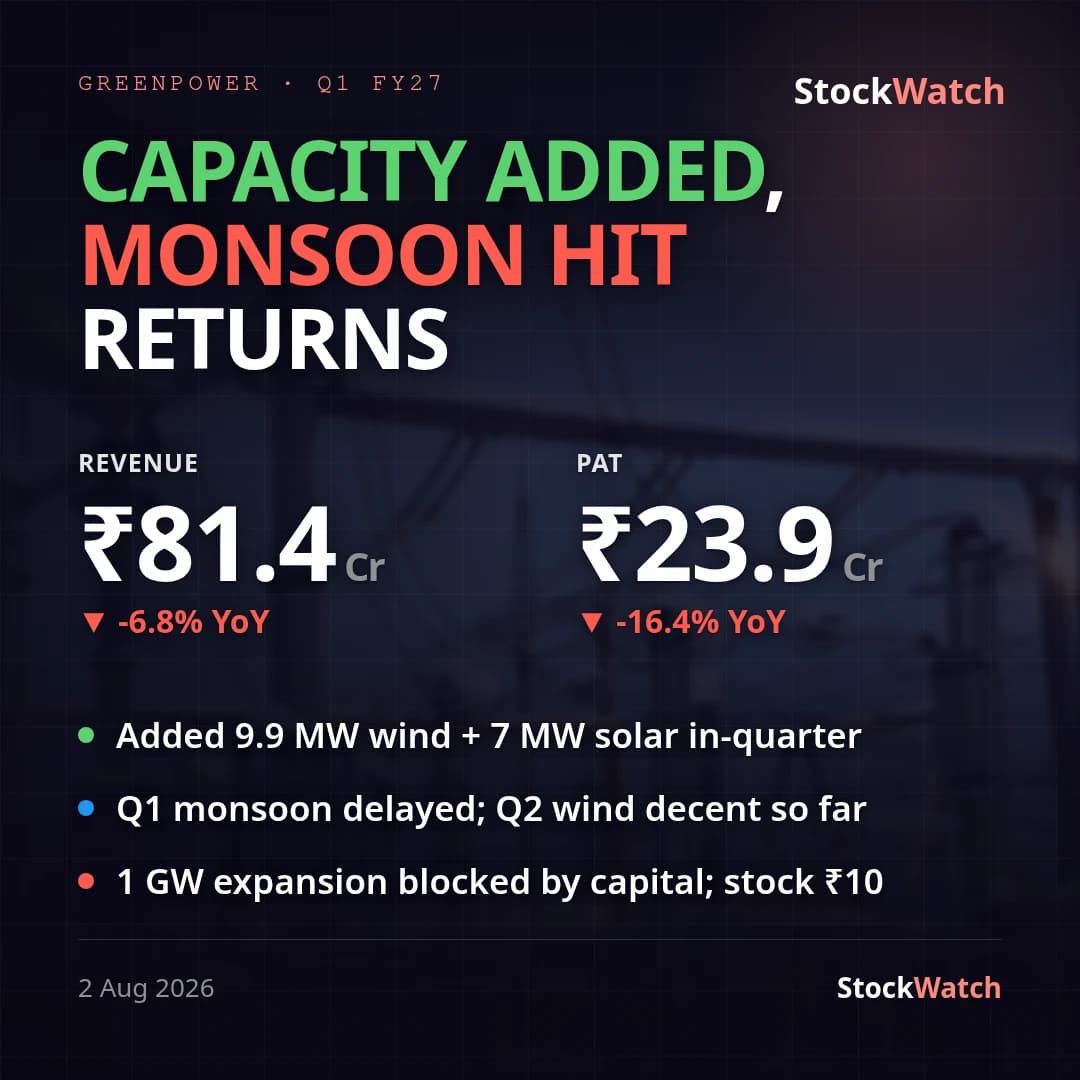
Capacity Added, Revenue Fell—Monsoon Risk Priced In

monsoon risk · capital constraint · 1GW stalled
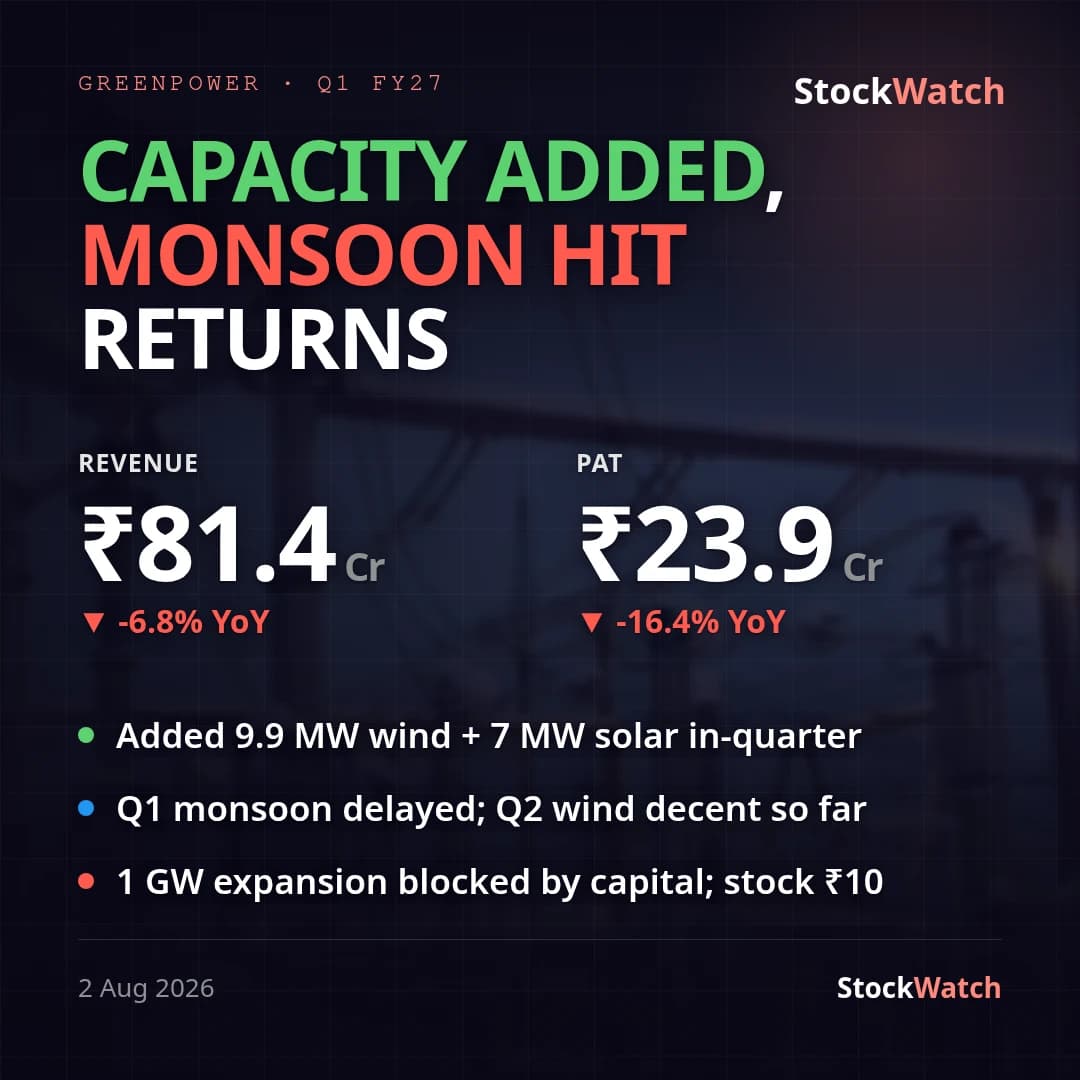
Result verdictFollow-upQ1 FY2702 Aug 20266 minEnergy & Oil/Gas

Capacity doubled yet revenue slid; wind wager dominates FY27

wind_dependency · capital_constrained · repowering_pipeline
TranscriptDeep diveQ1 FY2702 Aug 20266 minEnergy & Oil/Gas

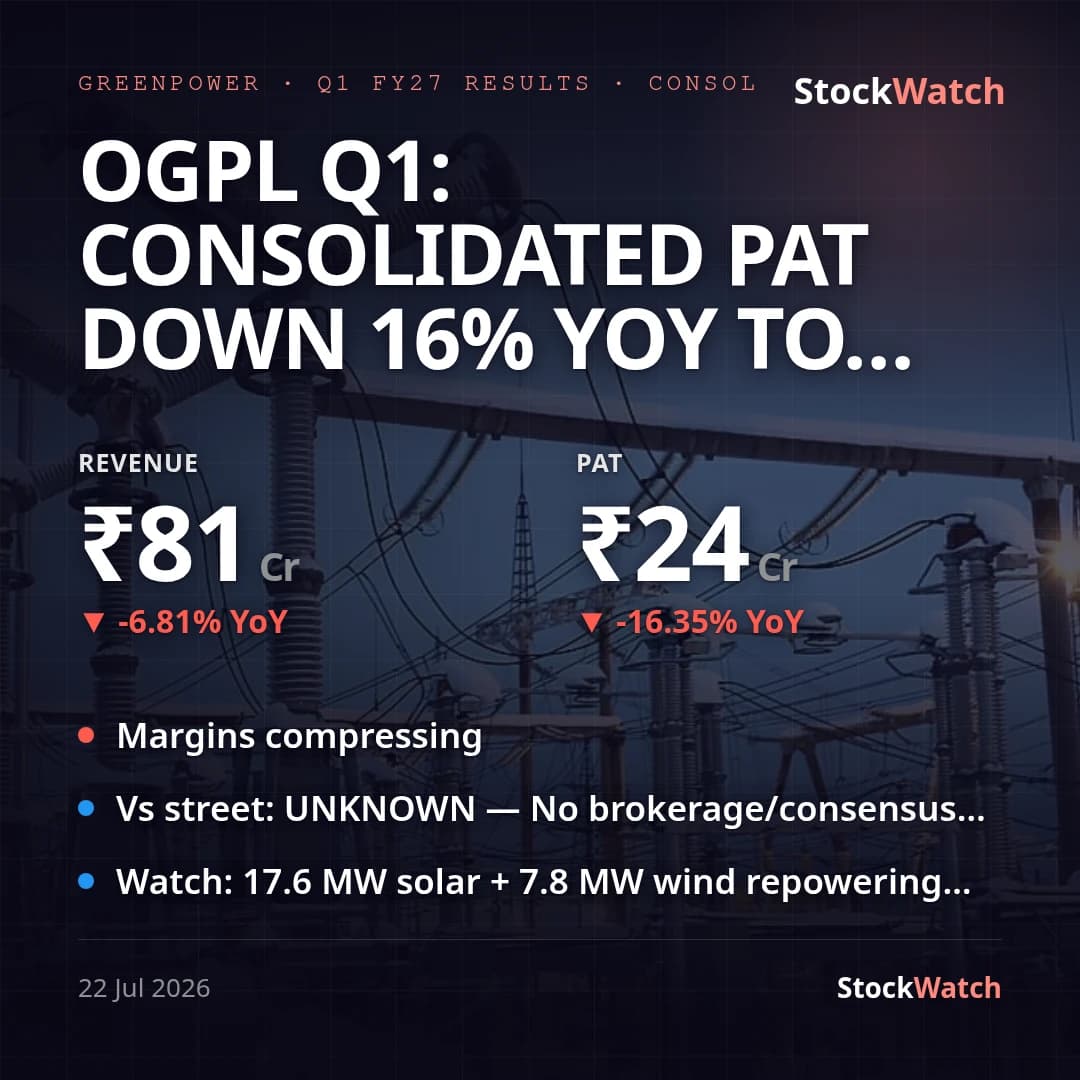
OGPL Q1: consolidated PAT down 16% YoY to ₹23.9 Cr as moderate wind softens topline

renewable power · wind energy · seasonal generation

ResultsQ1 FY2722 Jul 20263 minEnergy & Oil/Gas
Latest
Board Meeting22 Jul, 5:50 pm

Orient Green Power Q1 PAT falls 16% YoY to ₹23.9 Cr as softer wind, lower interest income bite

Orient Green Power reported a weaker year-on-year June quarter on a consolidated basis: revenue from operations fell ~7% YoY to ₹81.43 Cr (from ₹87.38 Cr) and net profit dropped ~16% to ₹23.94 Cr (from ₹28.62 Cr), with net margin compressing to ~29% from ~31%. The large sequential jump (revenue +111%, PAT swinging from a ₹16.6 Cr loss in Q4) is a seasonality artefact — this is a wind-heavy IPP whose June quarter is the monsoon-wind peak — and is not the story; YoY is. Management attributes the profit decline to two specifics: lower interest income after the previously deposited rights-issue proceeds were deployed into projects, and higher depreciation from recently commissioned capacity. EBITDA was ₹60.01 Cr (margin ~70% vs ~71%), so the squeeze sits below the operating line rather than in generation economics; wind availability was 'moderate' this quarter versus an exceptionally strong year-ago base, partly offset by output from new turbines. Against management's own prior guidance the print reads as a near-term miss on timing: the 17.6 MW solar addition and 7.8 MW wind repowering earlier flagged for Q1 have been pushed to a revised commissioning date of September 30, 2026, so the anticipated FY27 profitability uplift is now an H2 event. During the quarter the group commissioned one 3.3 MW turbine (after two in Q4), and separately the board withdrew the proposed merger of Netherlands subsidiary OGPE in favour of a faster voluntary liquidation to repatriate assets. No formal revenue/EPS guidance is given, and no brokerage Q1 consensus is on record for this small-cap, so the result cannot be benchmarked to a street number. The exceptional gain (₹0.21 Cr asset sale) is immaterial, leaving reported and underlying YoY declines effectively identical at ~16-17%.

22 Jul 2026, 05:50 pm

Corporate Events

Board MeetingGREENPOWER
2026
17Sep

Board Meeting

The Investment / Borrowing / Banking Committee of the Board …

BSE Filing
Board MeetingGREENPOWER
2026
22Jul

Board Meeting

The company will hold its 19th Annual General Meeting on Jul…

BSE Filing
Board MeetingGREENPOWER
2024
14Nov

Board Meeting

Intimation under Regulation 29 Of The SEBI (Listing Obligati…

BSE Filing
Board MeetingGREENPOWER
2024
11Nov

Board Meeting

Consider and approve the Un-Audited Standalone and Consolida…

BSE Filing
Board MeetingGREENPOWER
2024
23Oct

Board Meeting

Consider and approve the Un-Audited Standalone and Consolida…

BSE Filing
Board MeetingGREENPOWER
2024
24May

Board Meeting

Consider and approve Audited Standalone and Consolidated Fin…

BSE Filing
Board MeetingGREENPOWER
2024
14Feb

Board Meeting

Consider and approve the Unaudited Standalone and Consolidat…

BSE Filing
Board MeetingGREENPOWER
2023
1Nov

Board Meeting

Consider and approve Unaudited Standalone and Consolidated F…

BSE Filing
Board MeetingGREENPOWER
2023
11Aug

Board Meeting

Consider and approve the Unaudited Standalone and Consolidat…

BSE Filing