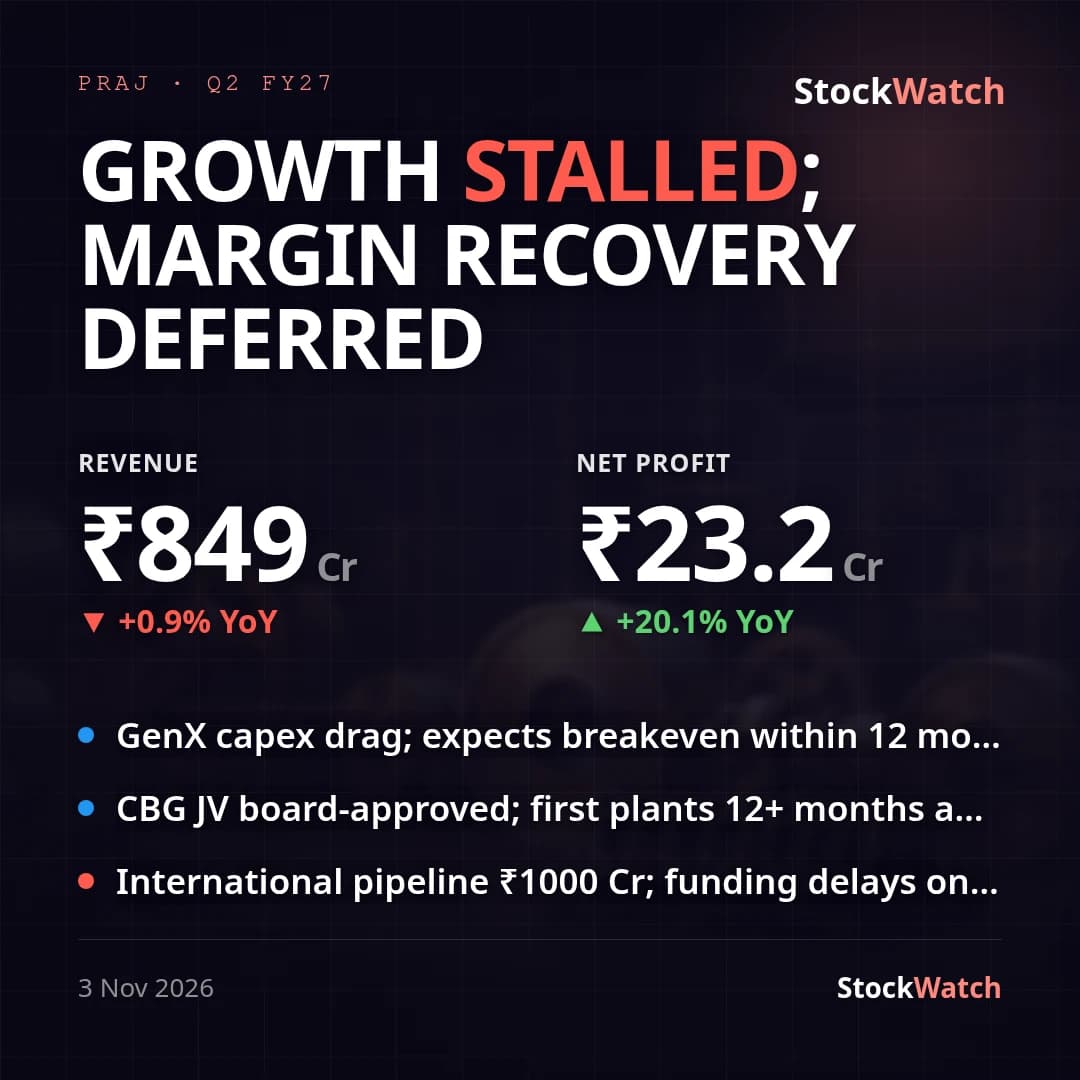
Praj Q2 FY27: consolidated PAT +20% YoY to ₹23 Cr, core margin eases on flat revenue
Praj Industries' consolidated (primary basis) Q2 FY27 revenue was ₹849.0 Cr, up a marginal 0.9% YoY from ₹841.6 Cr — essentially flat, not a growth quarter. Consolidated PAT rose 20.1% YoY to ₹23.2 Cr from ₹19.3 Cr, with EPS at ₹1.26 versus ₹1.05 a year ago. Sequentially both lines look stronger (revenue +18.6% QoQ, PAT roughly doubling QoQ) but that is a weak-base effect off a soft Q1 FY27 (₹11.6 Cr PAT) rather than a trend, and YoY is the number that should anchor the read. Standalone tells a materially different story: standalone revenue actually fell 5.0% YoY to ₹651.9 Cr even as standalone PAT grew a slower 9.1% YoY to ₹45.4 Cr — more than a 10-point gap versus the consolidated PAT growth rate, meaning subsidiaries and export operations, not the parent's core India business, drove the better group-level profit growth.
The headline PAT growth also masks a core-margin squeeze. Operating margin (EBITDA excluding other income, on revenue) eased to roughly 6.2% from 6.6% a year ago — even though it improved sequentially from Q1's 4.2% — as material and purchased-goods costs rose to about 56.7% of revenue from 45.6% a year ago, pointing to a costlier project mix this quarter. That squeeze was more than offset below the operating line: other income nearly doubled YoY to ₹12.2 Cr from ₹5.4 Cr, and finance costs fell to ₹3.4 Cr from ₹5.0 Cr, which is what lifted net margin to 2.7% from 2.3% YoY even as core profitability softened. None of this is flagged as exceptional in the filing, so the reported +20.1% YoY PAT growth needs no one-off adjustment — but its quality sits below the operating line, not in it.
On the August Q1 FY27 call, management gave no numeric guidance but said international orders (43% of intake) would convert to revenue through Q2–Q4 FY27, and that Praj GenX was targeted for EBITDA breakeven by FY27-end. This quarter is broadly consistent with the first point: overseas revenue jumped to ₹323.8 Cr from ₹177.2 Cr in Q1 (+82.7% QoQ); the GenX breakeven timeline isn't separately disclosed in this filing and remains unverified. No quarter-specific street consensus could be found in available previews, so the print can't be graded against a Street number; full-year FY27 consensus (per market trackers) implies EPS growth near 12%, which this quarter alone neither confirms nor contradicts. No separate management press release accompanied the filing, so there is no company framing to reconcile against the numbers. The quarter's other disclosed development, the mid-September Bio-IBA tie-up with Gevo, remains a developmental initiative per management's own prior characterization with no visible revenue contribution yet.