Shyam Metalics Q2: PAT ₹511 Cr (+96% YoY, ~45% adjusted) on strong volumes, margin gains
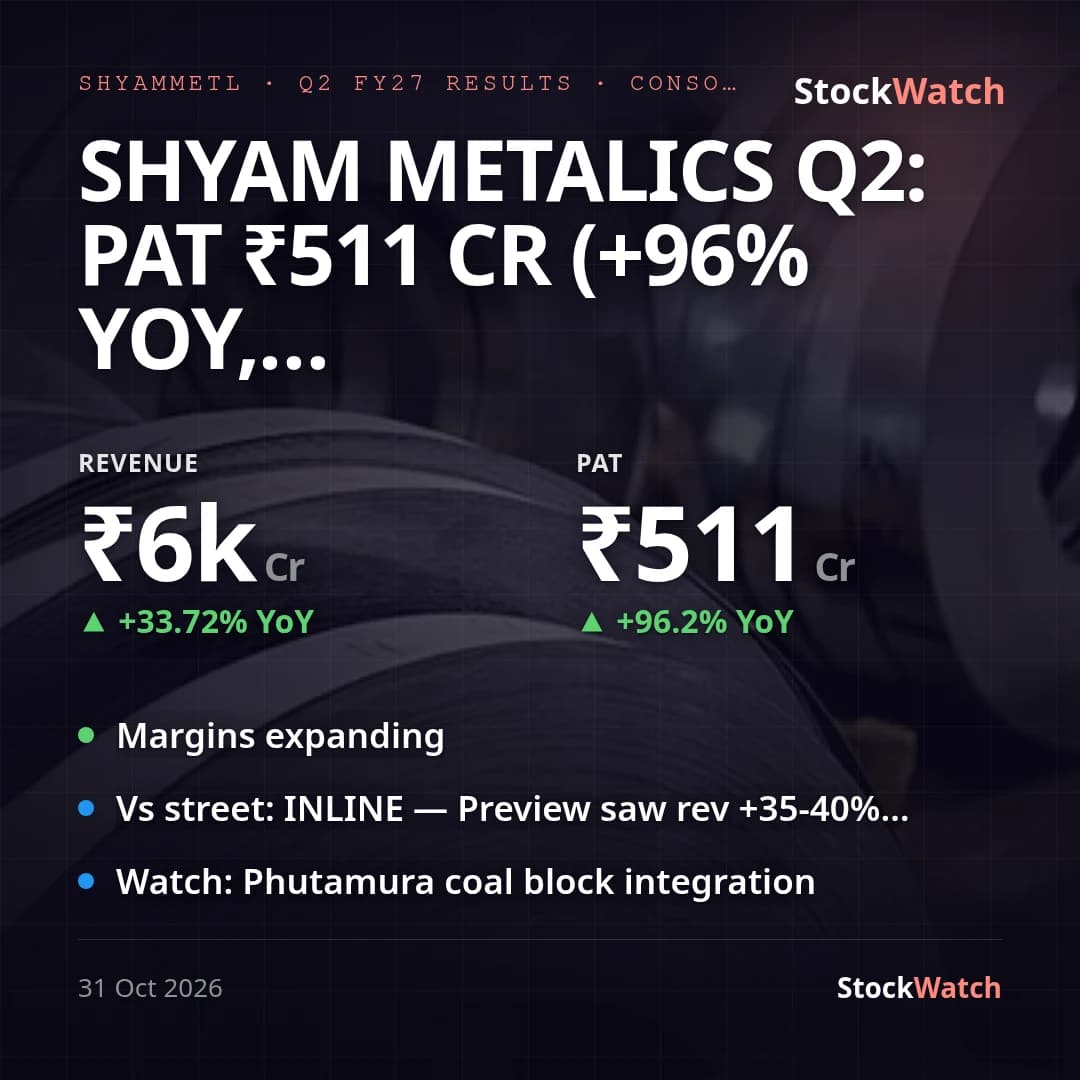
Shyam Metalics' consolidated PAT came in at ₹510.99 Cr (owners' share ₹493.35 Cr) for Q2 FY27, up 96.2% YoY and 45.7% QoQ, on revenue from operations of ₹5,960.19 Cr (+33.7% YoY, +9.3% QoQ). YoY is the primary read here, and on that basis the headline PAT number is flattered: effective 1 July 2026 the company switched its depreciation method from Written Down Value to Straight-Line, cutting consolidated Q2 D&A by ₹171.77 Cr versus what the old method would have charged. Stripping that one-off out, adjusted PAT growth is closer to ~45% YoY (~8% QoQ) — still strong, but roughly half the reported figure. The underlying operating print, which isn't touched by the depreciation change, was genuinely solid: EBITDA rose 40.9% YoY to ₹857.17 Cr, with OPM (EBITDA ex-other income/revenue) expanding to 13.81% from 12.10% a year ago, though it eased slightly from 14.03% last quarter.
Revenue growth was volume-led — company data shows 26% YoY volume growth for the quarter, matching the volume target embedded in management's FY27 guidance (20%+ EBITDA growth on a 25% volume target). H1 FY27 EBITDA of ₹1,669.55 Cr is up 34.5% YoY, running ahead of that 20%+ guidance, so the quarter is tracking on or ahead of plan on an operating basis even after backing out the depreciation tailwind. Consolidated and standalone results diverge sharply, however: standalone revenue grew just 13.2% YoY to ₹1,894.77 Cr and standalone PAT 46.1% YoY to ₹198.13 Cr, both well below the group numbers — the bulk of this quarter's growth is coming from subsidiaries and JVs, not the parent entity, so readers comparing the standalone print will see a materially slower-growing company.
Our pre-result preview had flagged ~26% volume growth and 35–40% revenue growth YoY as the bar, alongside Street consensus (Goldman Sachs Buy, target ₹1,120; Jefferies Buy, target ₹1,250) framing this as a volume story with execution risk around the Maharashtra greenfield plant. The print lands essentially in line: volume growth matched the 26% watch figure exactly, while revenue growth of 33.7% YoY came in just under the lower end of the expected 35–40% band. Nuvama's pre-quarter caution that steel profitability would soften in Q2 amid lower market prices showed up mildly in the sequential OPM dip (14.03%→13.81%) even as YoY margins still expanded. On corporate developments, the board on 31 October approved the Alom Solar acquisition (51% stake, SMEL's ₹183.6 Cr share of a ₹360 Cr capex budget) for the Phutamura coal block backward-integration project, alongside the previously NCLT-approved subsidiary merger and the induction of an LIC nominee director — none of which are yet reflected in this quarter's numbers.
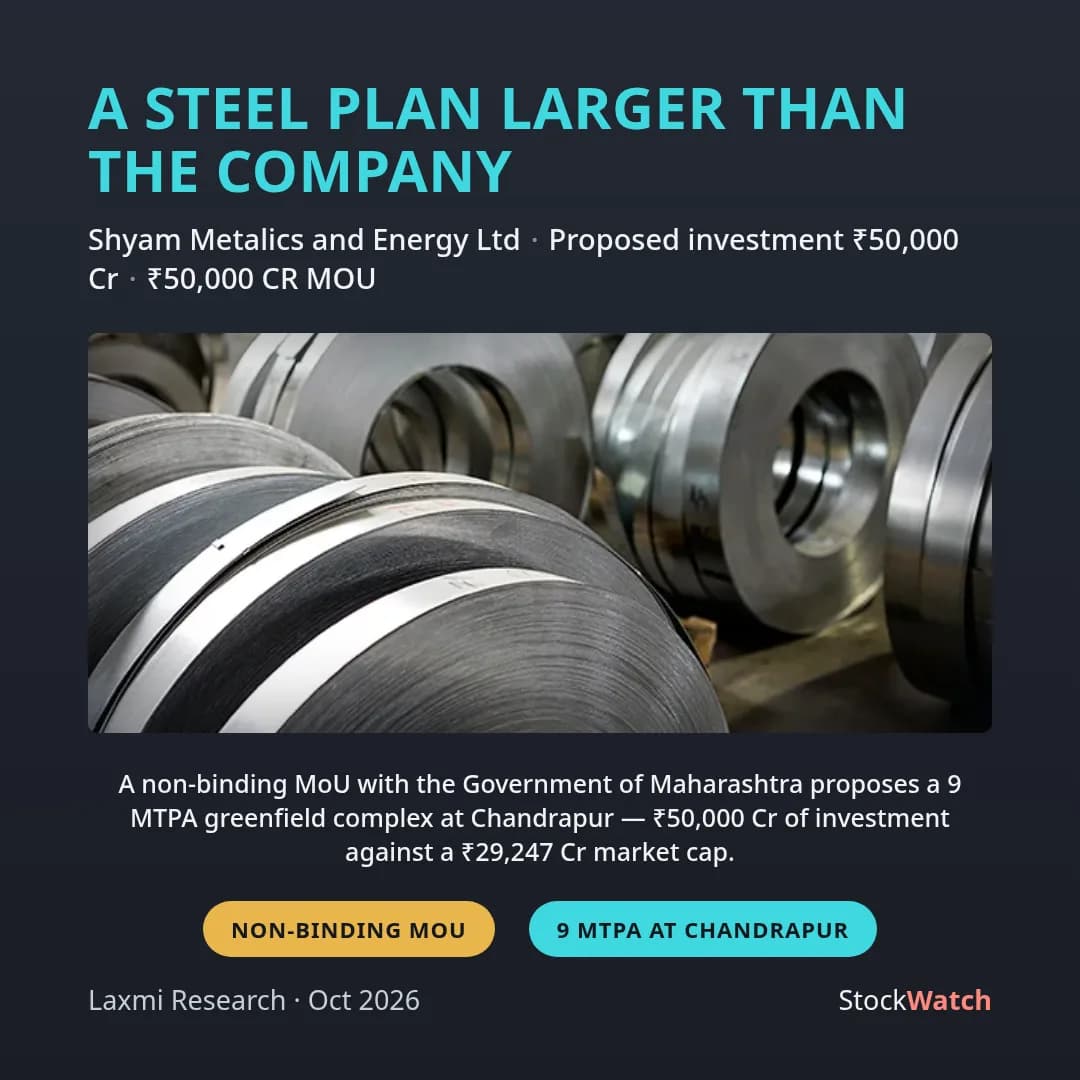
Going into Q3, the two things to track are whether the OPM softening seen this quarter extends further as the depreciation tailwind fades (it only applied from 1 July, so a full quarter's benefit shows up in Q3 as well, before normalizing), and how the ₹50,000 Cr Maharashtra steel-complex MoU and the coal-block integration translate into disclosed capex phasing.