Vedanta Aluminium Q2: consol. PAT more than doubles YoY to ₹6,187 Cr despite bauxite hit
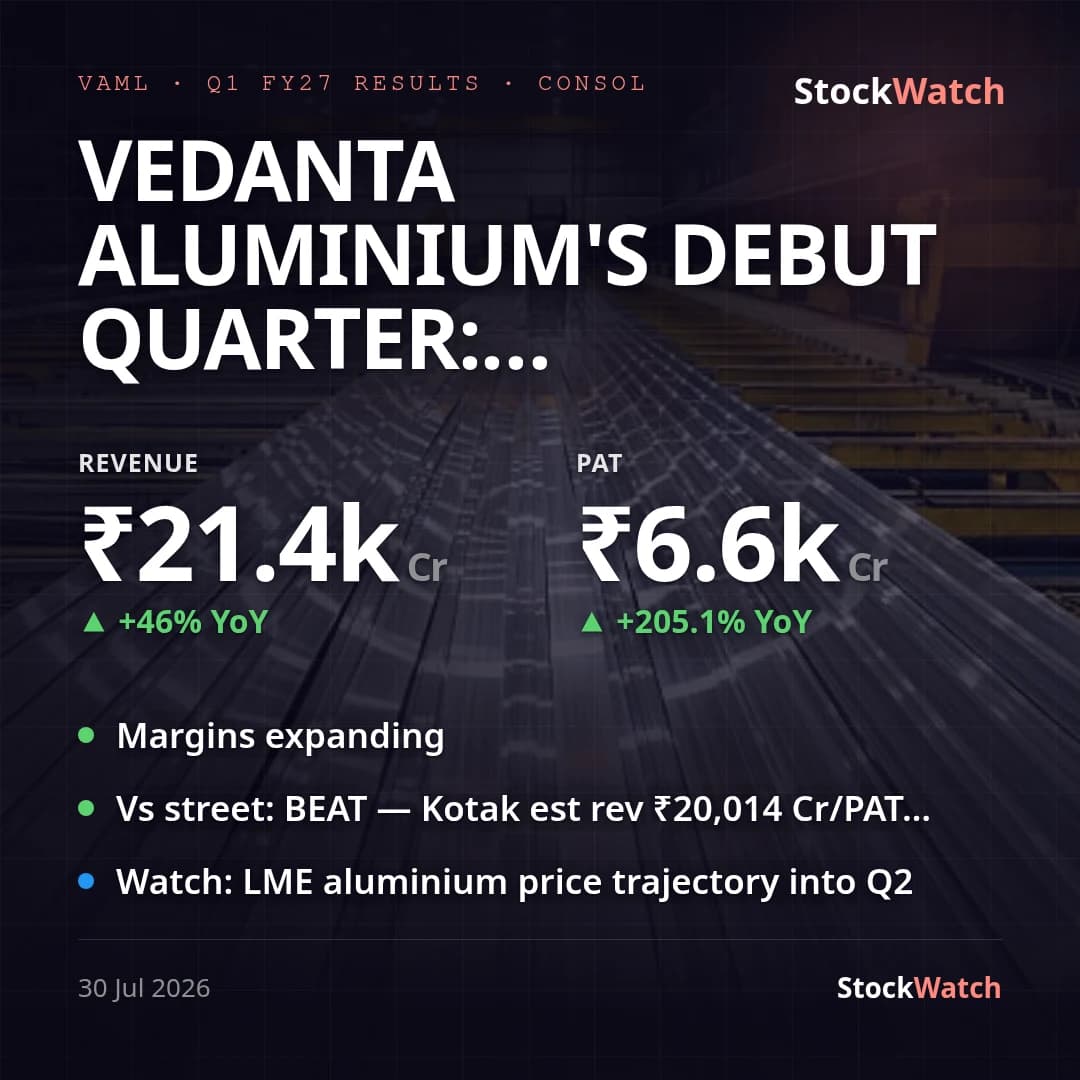
Vedanta Aluminium Metal's consolidated (primary basis) PAT for Q2 FY27 came in at ₹6,187 Cr, more than doubling year-on-year from ₹3,012 Cr (+105.4% reported, +117.5% adjusted for this quarter's ₹485 Cr exceptional charge), on consolidated revenue from operations of ₹22,324 Cr, up 40.0% YoY from ₹15,943 Cr. Sequentially the print cooled from Q1 FY27's record ₹6,597 Cr PAT and ₹21,393 Cr revenue — PAT down 6.2% QoQ and revenue up a modest 4.3% QoQ — a normalisation after an unusually strong debut quarter rather than a deterioration in the underlying business. Standalone PAT grew faster YoY (+142.5%, to ₹4,106 Cr from ₹1,693 Cr) than consolidated; the gap comes from BALCO, the 51%-owned subsidiary consolidated into Group accounts with non-controlling interests of ₹1,020 Cr this quarter, diluting headline growth versus the standalone aluminium business alone. No management press release was available to cross-check framing of these numbers. No analyst consensus figure for this specific quarter surfaced in a web search (results were filed same-day); the pre-result Street read was broadly bullish — nine analysts rated the stock Strong Buy with an average target of ₹553.89, implying ~21% upside from the pre-result price of ₹344.5.
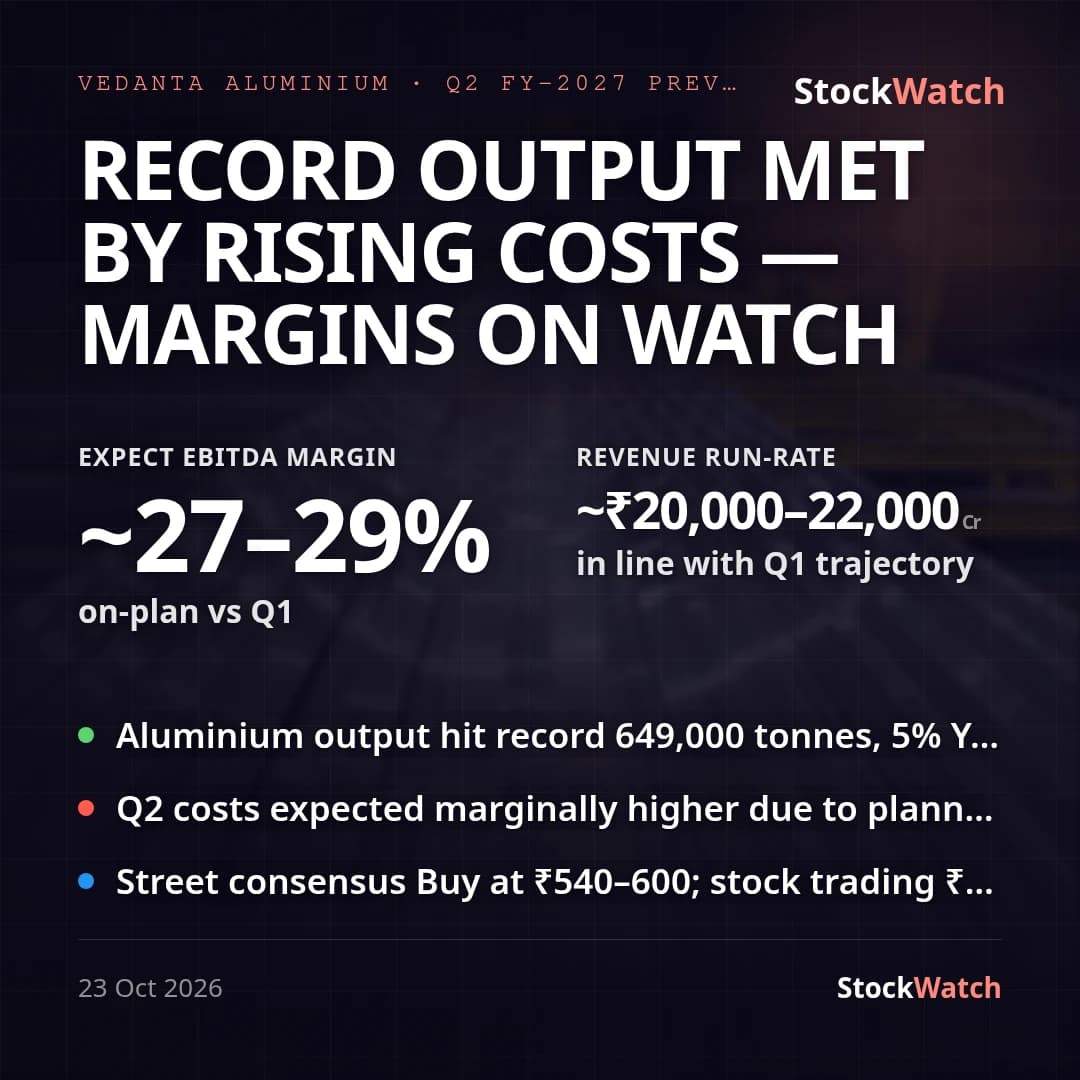
Margins expanded sharply YoY: EBIT margin (EBITDA less depreciation, over revenue from operations, per the company's own ratio disclosure) rose to 42% from 31% a year ago, and net margin (profit before exceptional items over revenue) rose to 29% from 19%. Both eased modestly from Q1 FY27's 45%/31% as costs normalised after an exceptionally strong opening quarter — EBITDA was ₹10,192 Cr against ₹10,499 Cr in Q1 and ₹5,582 Cr a year ago. Management has placed no formal profit guidance on our record for this quarter; the pre-result preview we published flagged a cost trajectory of $1,650–$1,700/t for FY27 with Q2 costs expected marginally higher on planned shutdowns — the sequential (not YoY) margin give-back is consistent with that cost step-up, though the filing does not break out an all-in cost-per-tonne figure to confirm the exact level.
The quarter's ₹485 Cr exceptional charge (₹363 Cr net of tax) resolves one of our flagged pre-result watch items: ₹400 Cr of it is an additional provision for bauxite supplied by Odisha Mining Corporation under the Long-Term Linkage arrangement, booked after the Orissa High Court dismissed the company's writ petition on the bauxite-pricing dispute on October 1, 2026. The remaining ₹85 Cr is stamp duty on the demerger-related transfer of land and mining rights. Beyond the amount already provided, OMC has raised a further consequential demand of ₹3,539 Cr plus interest and GST, which the company is contesting before the Supreme Court and does not believe will succeed, per management's note. Separately, the quarter saw record aluminium output of 649 kt (+5% YoY), as flagged in the October 3 production update, and the board declared a total FY27 dividend of ₹8 per ₹1 face-value share, resolving the dividend watch item from our preview.
Going into H2 FY27, the two swing factors flagged pre-result remain live: the Supreme Court outcome on the OMC bauxite demand, and whether costs hold near the $1,650–$1,700/t guided range as BALCO's integration (51% stake, consolidated since April 2026 under the demerger scheme) progresses. The sequential margin and PAT moderation this quarter is attributable to the one-off charge and normalising costs rather than a demand or volume issue — volumes hit a fresh record — so the YoY trend of expanding margins and more-than-doubled profit is the cleaner read on underlying performance.