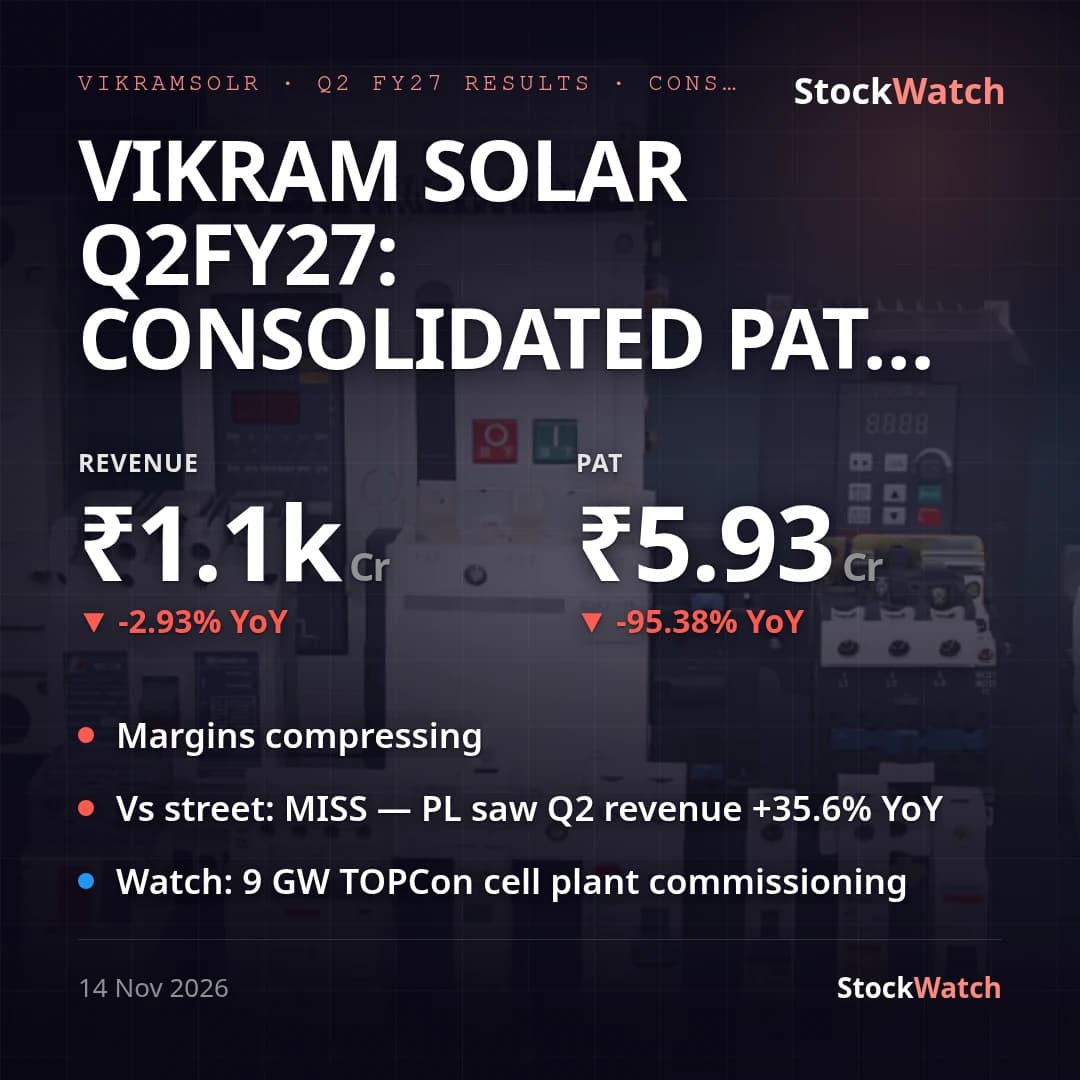
Vikram Solar Q2FY27: consolidated PAT crashes 95% YoY to ₹5.9 Cr as margins compress
Vikram Solar's consolidated PAT for Q2FY27 (quarter ended September 30, 2026) collapsed 95.4% year-on-year to ₹5.9 Cr, down from ₹128.5 Cr in Q2FY26, even as consolidated revenue held roughly flat at ₹1,077.4 Cr (-2.9% YoY). The decline is also sequential: PAT fell 70% from Q1FY27's already-weak ₹19.8 Cr, while revenue dropped 31% from ₹1,563.1 Cr, undercutting Prabhudas Lilladher's pre-quarter estimate of roughly +35.6% YoY revenue growth (October 7, 2026 sector preview) by a wide margin — a clear miss against Street's growth expectation, not just a margin story.
The margin bridge explains most of the damage: consolidated operating margin (EBITDA/revenue) fell to 9.4% from 21.2% a year ago, even though it edged up from Q1's 8.1%, and net margin shrank to 0.5% from 11.4% YoY. Finance costs rose 35% YoY to ₹42.7 Cr and depreciation jumped 89% YoY to ₹65.8 Cr as the 9 GW TOPCon cell-plant capex lands on the balance sheet — consolidated borrowings have risen more than 6x since March 2026 to ₹631.8 Cr, and H1FY27 capex on property, plant and CWIP reached ₹981.6 Cr, consistent with management's cited ₹5,000 Cr FY27-28 capex plan. No exceptional items appear in either the standalone or consolidated statement this quarter, so the swing is operating, not a one-off.
Management did not reaffirm the FY27 EBITDA target of ₹1,500-1,600 Cr flagged at the Q1 call; H1FY27 consolidated EBITDA of roughly ₹227 Cr tracks far below the run-rate that target implies, and no formal FY27 guidance is on record — consistent with the prior call's cautious tone and the deferral pending clarity on DCR pricing, distribution penetration and ALMM 2 policy. The one concrete positive on record is the 9 GW TOPCon cell plant, reported on track for December 2026 commissioning (October 23 project update), which management has tied to 40-50% utilisation in FY28. The quarter's order wins — a 289.87 MWp module order from NLC India (Oct 27) and a 187 MW supply order (Oct 15) — add to the book but aren't large enough to move this quarter's print. No management press release accompanied this filing, so there is no company commentary to reconcile against the numbers beyond the notes to the financial statements.
Standalone results tell the same story at a similar magnitude — standalone PAT fell 97.1% YoY to ₹3.7 Cr on revenue of ₹1,073.3 Cr — so the group-level numbers aren't being flattered by subsidiaries. Going into Q3FY27, the quarter sets up a test of whether the TOPCon ramp (December target) can arrest further margin erosion before FY28, with the EVP Sales & BD departure (Sept 29) and new CBO appointment adding execution-risk attention alongside the capex-driven debt build.