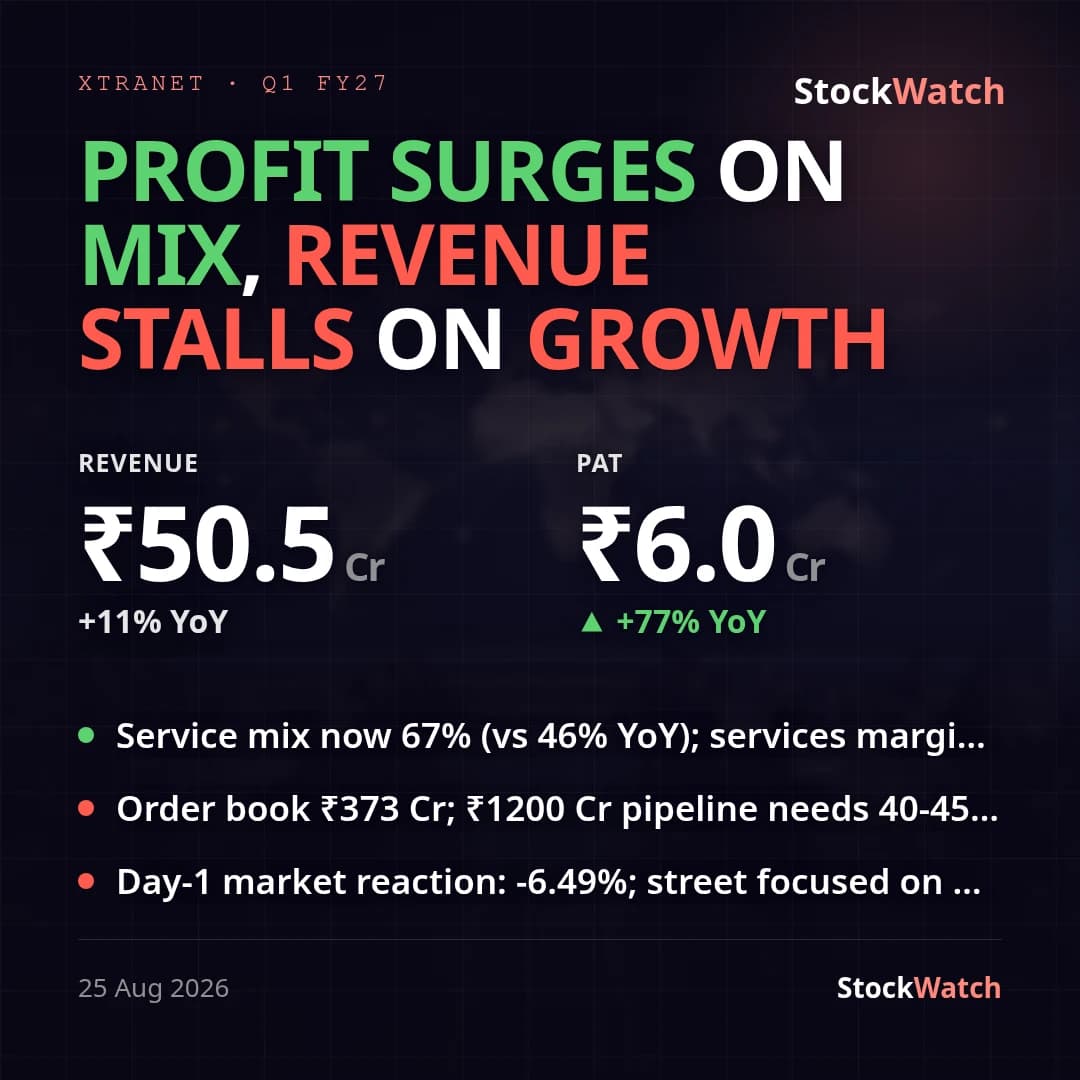
XtraNet Technologies' consolidated PAT rose 77.9% YoY to ₹6.04 Cr (₹3.39 Cr in Q1 FY26) on revenue of ₹50.46 Cr, up 10.5% YoY (standalone: PAT ₹5.38 Cr, +79.6% YoY, on revenue ₹43.38 Cr, +9.6% YoY). Consolidated net margin expanded to ~12.0% from ~7.4% a year ago. There is no street/brokerage coverage available for this stock to benchmark the print against, and management has issued no formal guidance on record, so neither vs-street nor vs-guidance can be assessed here.
The margin gain came almost entirely from a lower cost of trading goods: purchase of stock-in-trade plus inventory movement fell to ~51.6% of consolidated revenue from ~59.8% a year ago, which more than offset a heavier cost base elsewhere — finance costs (₹1.72 Cr vs ₹0.72 Cr) and depreciation (₹1.68 Cr vs ₹0.74 Cr) both more than doubled YoY. That rise lines up with the company's ₹15.25 Cr investment in subsidiary Xtratrust Digisign announced August 7, which likely added debt and amortisable assets to the consolidated base this quarter. Profit attributable to owners was slightly higher, at ₹6.07 Cr (basic EPS ₹1.55 vs ₹0.90 a year ago), as non-controlling interest posted a small loss. No exceptional items were reported in either statement, and the company has not issued a separate press release with management commentary on the results.
Sequentially, revenue fell 68.6% and PAT 75.1% from Q4 FY26 (₹160.96 Cr revenue, ₹24.23 Cr PAT) — a seasonal step-down rather than a deterioration: billing at this company is heavily back-loaded into the March quarter, so the QoQ drop mirrors the same pattern seen in the year-ago comparatives and is not informative about underlying trend.