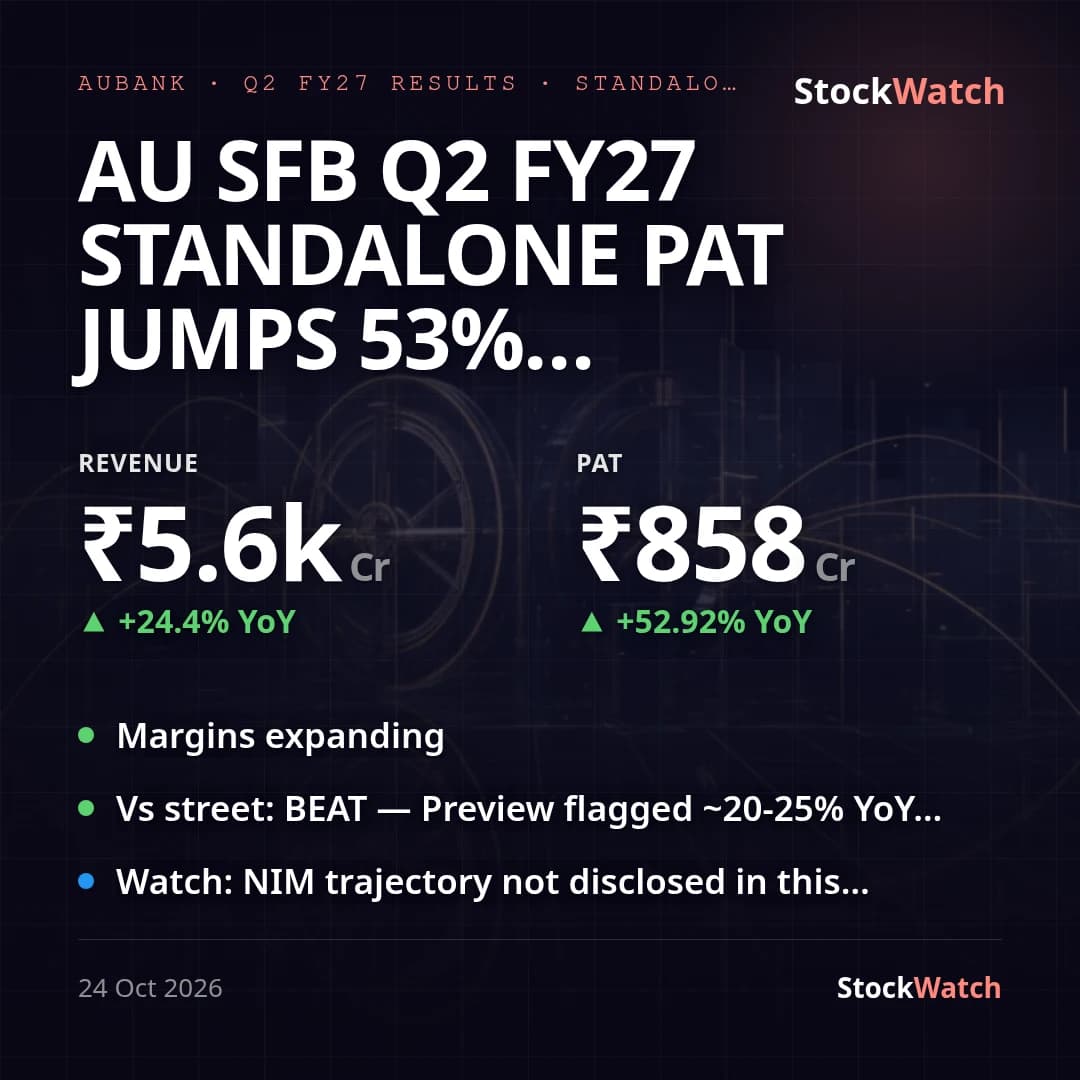
AU SFB Q2 FY27 standalone PAT jumps 53% YoY to ₹858 Cr, tops Street's 20-25% growth call
AU Small Finance Bank's standalone net profit for Q2 FY27 came in at ₹857.69 Cr, up 52.9% year-on-year from ₹560.87 Cr and up 7.8% sequentially from ₹795.95 Cr in Q1 FY27. This decisively clears the ~20-25% YoY PAT growth our pre-result preview flagged as the Street's bar going in — the quarter is a clear beat on profit growth, not a marginal one. Total income rose 22.2% YoY to ₹6,381.99 Cr, with interest earned up 24.4% YoY to ₹5,611.81 Cr; net interest income (interest earned less interest expended) grew faster still, up 31.5% YoY to ₹2,820.08 Cr, which is the primary driver of the profit beat. No exceptional items sit in either the current or year-ago quarter, so the 52.9% YoY PAT growth is a clean, unadjusted number.
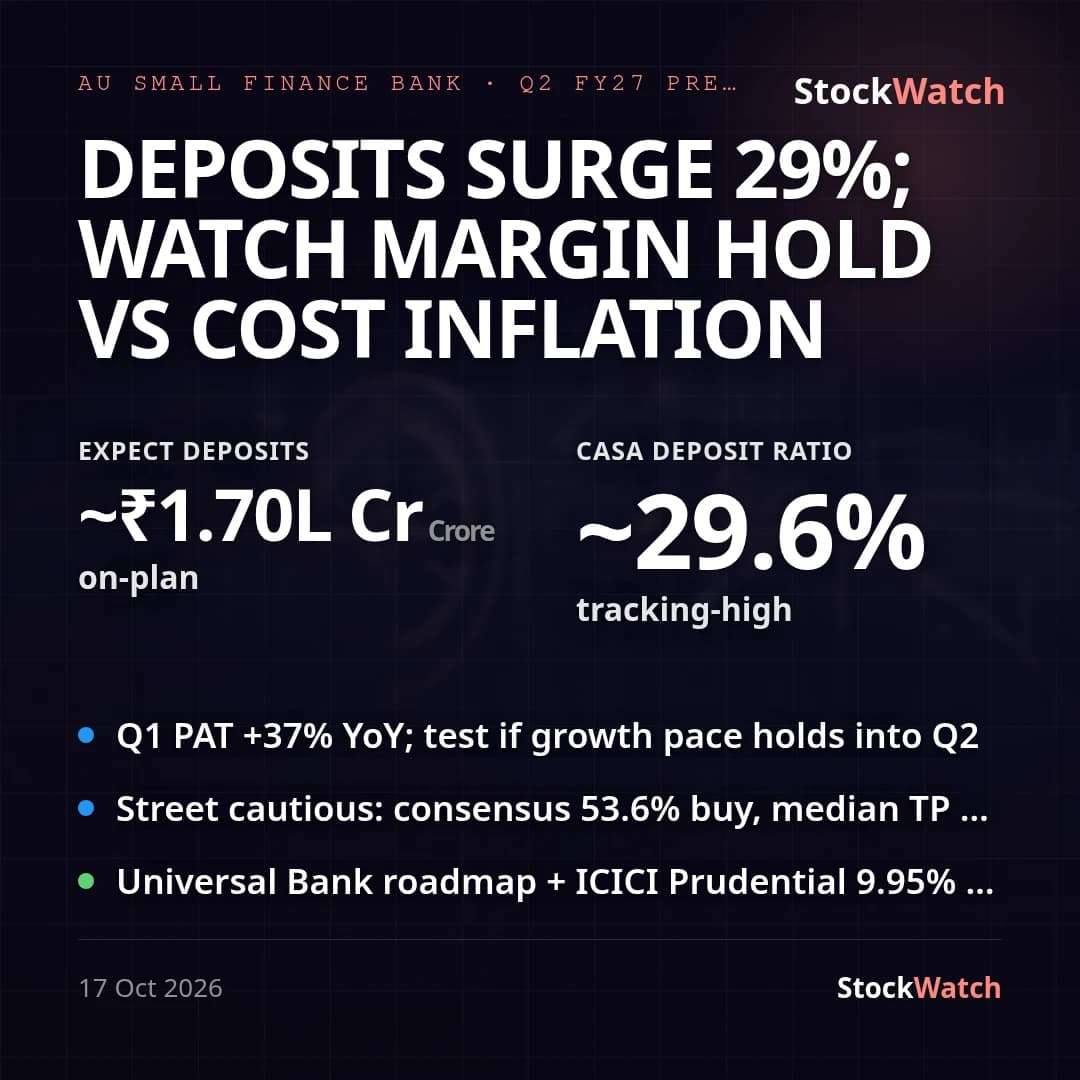
Margins expanded on the bottom line: net profit margin (PAT/total income) rose to 13.44% from 10.74% a year ago and 13.28% last quarter. Operating profit margin (operating profit/interest earned) was roughly flat at 26.97%, against 26.82% a year ago and 27.07% in Q1 — the NPM expansion is coming from controlled provisioning and tax, not a wider operating spread. Provisions fell to ₹359.40 Cr from ₹480.83 Cr a year ago even as the book grew, and asset quality improved on a YoY basis: gross NPA eased to 1.99% from 2.41% a year ago (and from 2.10% in Q1), while net NPA improved YoY to 0.81% from 0.88%, though it ticked up 5bps from Q1's 0.76%. Deposits grew 28.6% YoY to ₹1,70,460 Cr — matching exactly the provisional deposit figure the bank pre-announced on October 3 — and advances grew 28.4% YoY to ₹1,48,508 Cr, putting the loan-to-deposit ratio near 87%. All three reporting segments grew profit before tax strongly YoY: wholesale banking +94.5%, treasury +76.3%, retail banking +69.3%, indicating the growth is broad-based rather than concentrated in one book.
Against management's own prior guidance (from the Q1 FY27 concall), the picture is more mixed than the headline PAT beat suggests. Return on assets (quarterly, un-annualized) was 0.41%, essentially flat with Q1's 0.42% — on a simple annualized basis that puts the run-rate near 1.6-1.7%, which has not closed the gap to the stated full-year 1.8% ROA target that required a 10bps lift from opex and credit cost; if anything the sequential trend moved slightly away from target rather than toward it. An approximate read on opex against average assets puts the cost ratio close to the ~4% Q1 level, keeping the sub-4% full-year cost-to-assets goal in reach but not showing visible improvement yet. No press release or management commentary was available beyond the regulatory outcome letter, which only confirms board approval of the results — there is no qualitative framing from management in this filing to cross-check against the numbers.
The quarter's other disclosed developments — the RBI's September 9 nod for ICICI Prudential AMC to hold up to 9.95% of the bank, the September appointments of a new senior executive and reappointment of the head of internal audit, and the ongoing Universal Bank license transition (NOFHC requirement now deferred to transition rather than upfront, per Note 5) — are governance/structural items that don't directly move this quarter's P&L. Going into H2 FY27, the ₹1,653.64 Cr H1 PAT is tracking at roughly 46-48% of brokerage FY27E full-year PAT estimates in the ₹3,000-3,600 Cr range (Arihant Capital, YES Securities), implying H2 would need to run close to or modestly above H1's pace to meet full-year consensus — a reasonable ask given this quarter's growth, but NIM trajectory and the ROA-to-target gap remain the open questions.