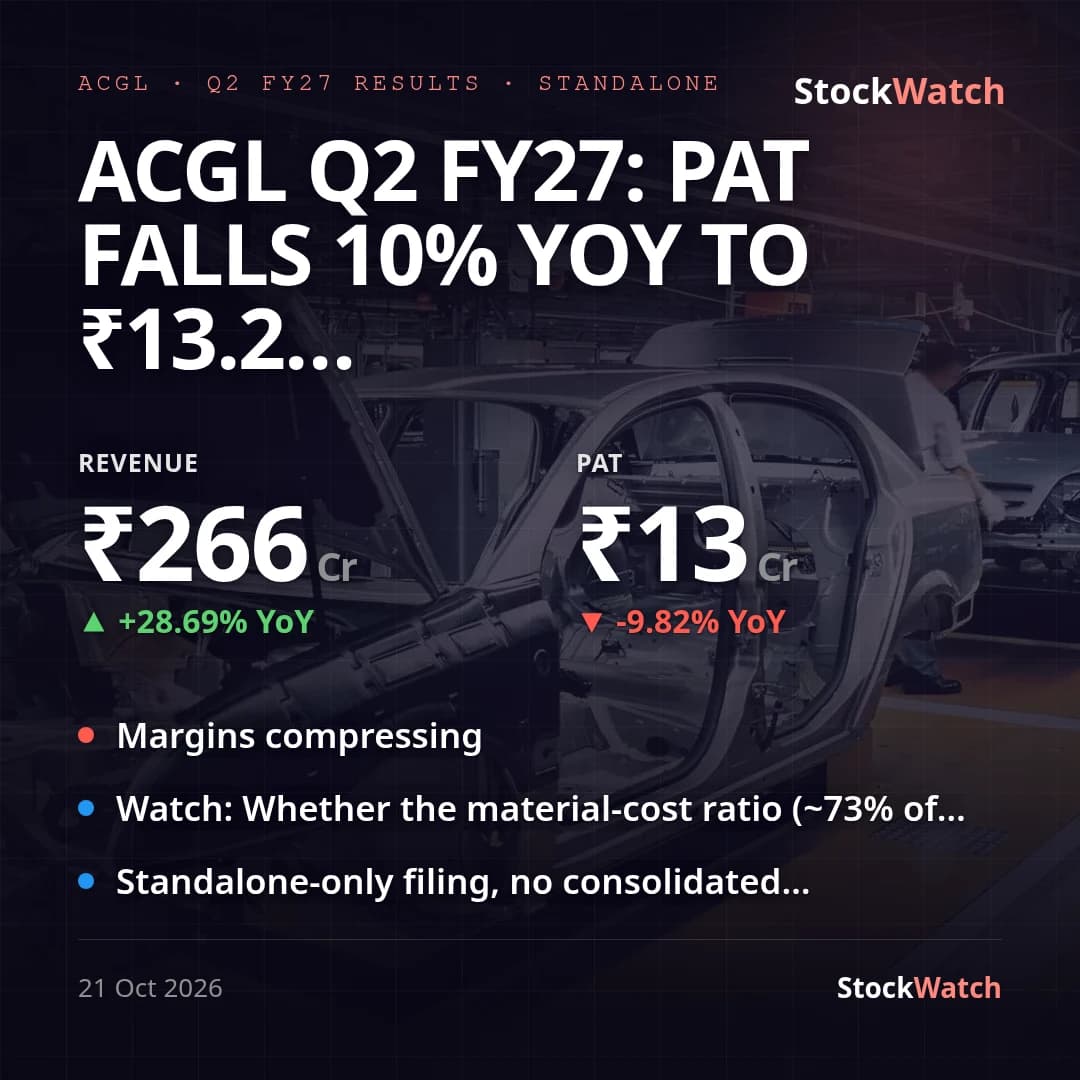
ACGL Q2 FY27: PAT down 9.8% YoY on margin compression despite 28.7% revenue growth
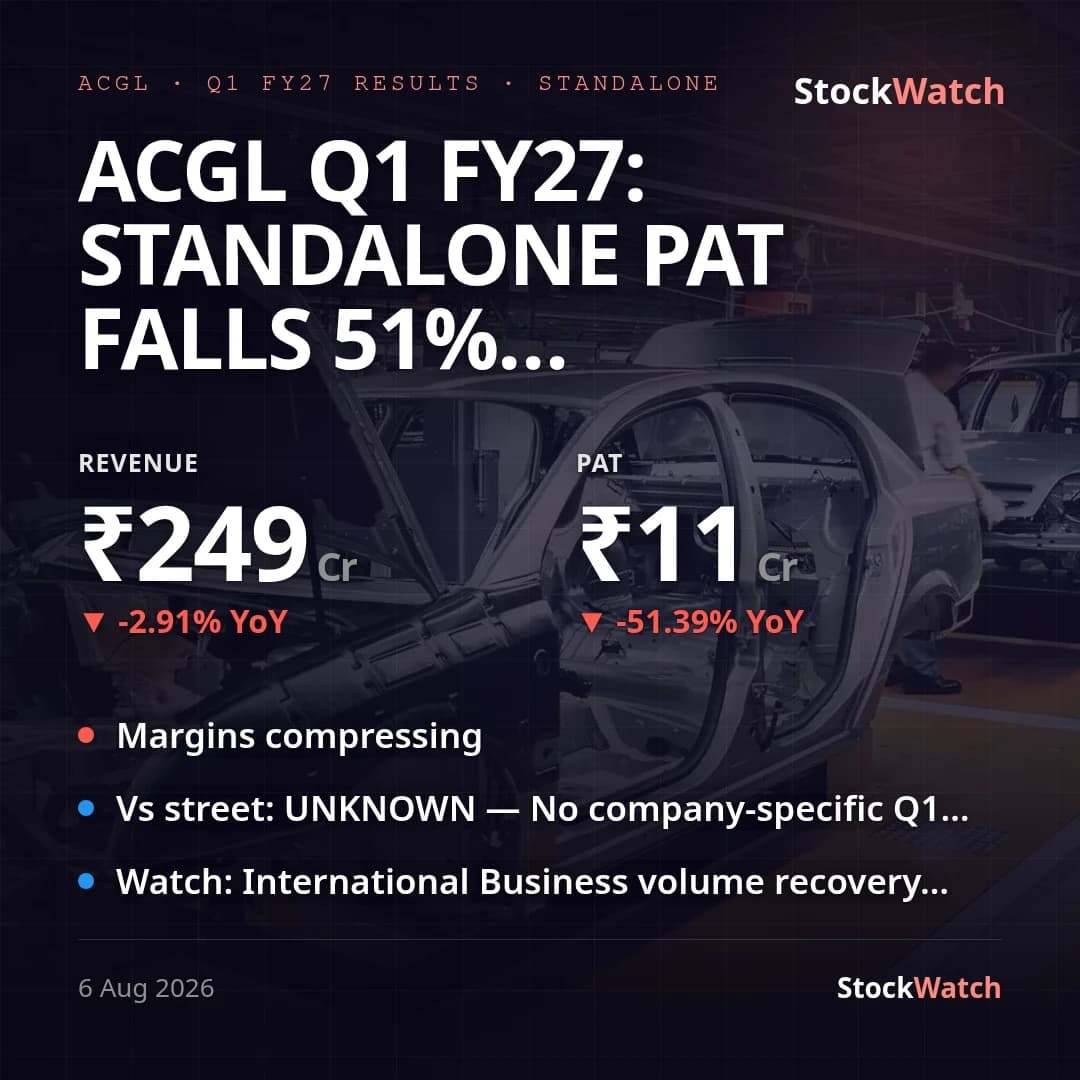
Automobile Corporation of Goa (standalone — the company files no consolidated results) reported Q2 FY27 revenue from operations of ₹265.59 Cr, up a strong 28.7% YoY and 6.7% sequentially. But profit after tax fell 9.8% YoY to ₹13.20 Cr even as it recovered 17.7% QoQ off a weak Q1 FY27 base (which had itself fallen 51% YoY). There is no analyst consensus or brokerage preview on record for this micro-cap (public float of ~31 lakh shares), so vsStreet is unknown; the company also carries no formal prior guidance, and management's own "Looking Ahead" commentary here is generic (continued focus on operational excellence and cost optimisation) rather than a quantified target, so vsGuidance is unknown too.
The profit decline despite double-digit revenue growth is a margin story. EBITDA margin compressed to 7.26% from 10.02% a year ago, and PBT margin fell to 6.55% from 9.34%. The squeeze traces to the cost line: cost of materials consumed rose to 73.2% of total income from 72.2% in Q2 FY26, pushing total expenses to 93.5% of total income from 90.7%. Employee costs and other expenses were actually a smaller share of revenue than a year ago, so the compression is concentrated in input costs, not overheads.
No exceptional items hit either this quarter or the year-ago quarter, so the YoY profit decline is a clean comparison. Separately, the same board meeting approved a ₹29 Cr tender-offer buyback (144,639 shares, 2.38% of equity, at ₹2,005/share, record date October 28, 2026) and a chairmanship transition — Ms. Swati Shivanand Salgaocar succeeds Mr. Yatin Kakodkar effective December 7, 2026 — neither of which bears on this quarter's operating numbers. On operations, management flagged 2,336 bus bodies delivered versus 1,966 a year ago, while the IB (export) business continued to face headwinds from the Middle East geopolitical situation; domestic business stayed stable.
Heading into Q3, the two things to track are whether the materials-cost pressure behind the YoY margin compression eases, and whether the sequential PBT-margin recovery (6.01% in Q1 FY27 to 6.55% now) continues.