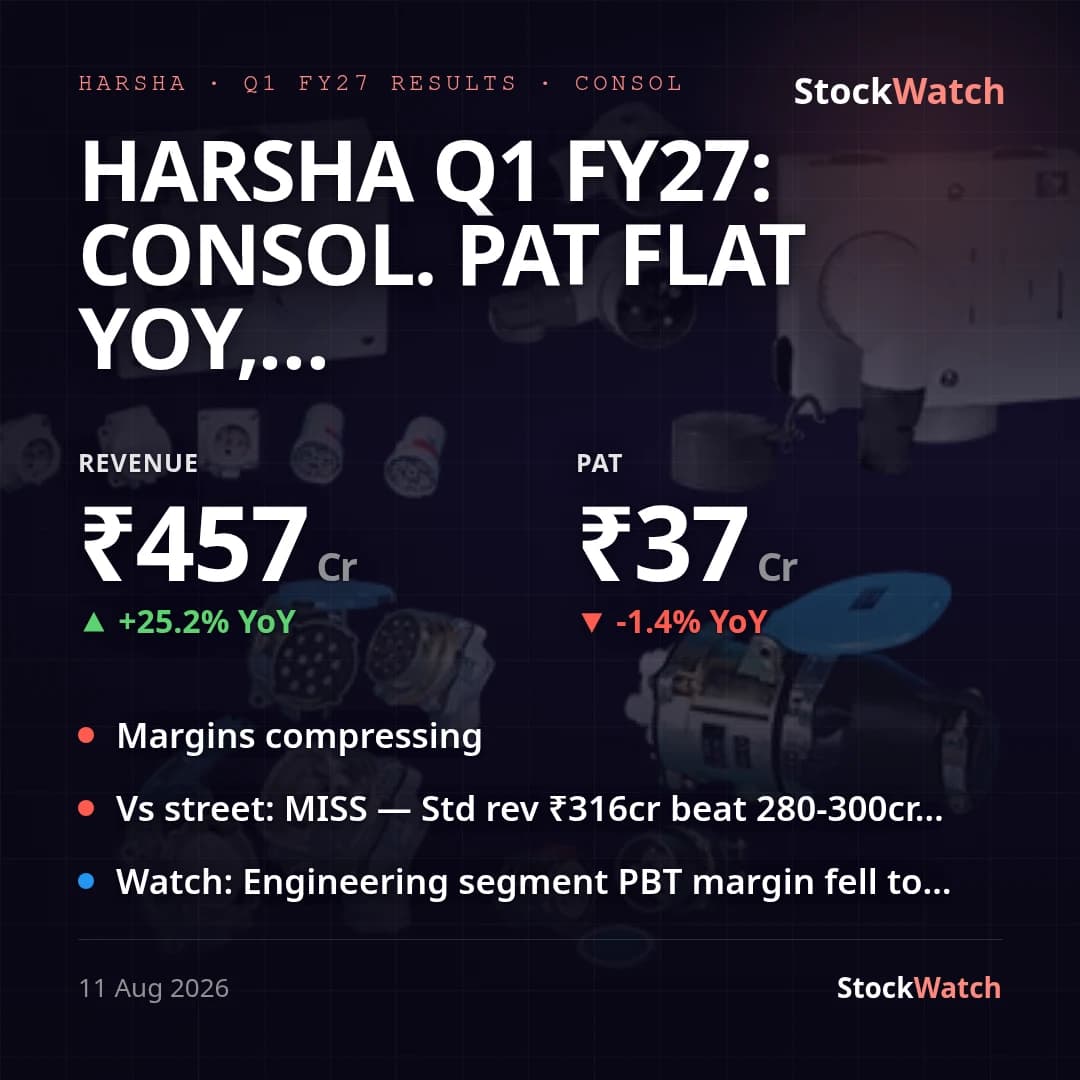
Harsha Q1 FY27: consol. PAT flat YoY, capex squeezes margin despite 25% revenue growth
Harsha Engineers International's consolidated Q1 FY27 (quarter ended June 30, 2026) revenue rose 25.2% YoY to ₹457.4 Cr (from ₹365.3 Cr), well ahead of management's double-digit FY27 topline guidance and above the ₹280-300 Cr standalone revenue band flagged in our pre-result preview (standalone revenue came in at ₹316.3 Cr). But profit did not scale with revenue: consolidated PAT was ₹37.4 Cr, down 1.4% YoY (₹37.9 Cr) and down 20.9% sequentially from ₹47.2 Cr in Q4 FY26, with EPS at ₹4.11 versus ₹4.17 a year ago — inside the preview's ₹3.8-4.2 range, but only because margin gave way. Net profit margin compressed to 8.1% of total income from 10.1% (YoY) and 9.8% (QoQ). Full-year FY27 street consensus (Simply Wall St, 3 analysts) pegs revenue near ₹1,870 Cr and EPS at ₹21.00; this quarter's ₹4.11 EPS is roughly 20% of that annual target, a plausible pace for a seasonally lighter Q1 but not conclusive on its own.
The compression is concentrated in the core Engineering & Others segment: its PBT margin fell to ~11.9% of segment revenue from ~15.0% a year ago and ~15.3% last quarter, with segment PBT (₹50.2 Cr) down 3.9% YoY and 14.3% QoQ even as segment revenue grew 20.7% YoY and 10.2% QoQ to ₹421.1 Cr — cost growth outpaced the topline in the business itself. That's compounded at the consolidated level by capex-linked financing costs: finance costs jumped 126.8% YoY to ₹5.83 Cr and depreciation rose 30.9% YoY to ₹13.78 Cr, consistent with the ₹110-crore China and Advantek-phase-2 build-out our preview flagged. This is the direct answer to that preview's "can margins hold through capex" question — no, they didn't: margin ended the quarter at ~11.9%, at or slightly below the 12-13% bear case the preview itself called out, and below management's own guidance of "at least maintaining the current margin profile." The revenue-growth leg of guidance was beaten; the margin leg was missed.
The ₹457.4 Cr headline also masks a mix effect: Solar-EPC & O&M segment revenue, which is lumpy and project-timing driven, fell 60.4% sequentially to ₹36.4 Cr from ₹91.8 Cr in Q4 (still up 120.8% YoY from ₹16.5 Cr), accounting for most of the -3.5% QoQ consolidated revenue decline — the core Engineering business did not slow sequentially. This quarter's limited review was the first conducted by newly appointed statutory auditor Mukesh M. Shah & Co. (appointed July 23, 2026, replacing the predecessor auditor), a routine rotation rather than a governance flag. No standalone management press release or commentary was available in the filing to cross-check against these numbers. Standalone and consolidated tell a consistent story — standalone PAT ₹45.7 Cr on ₹316.3 Cr revenue, EPS ₹5.02 — with no material divergence in growth trend between the two bases.