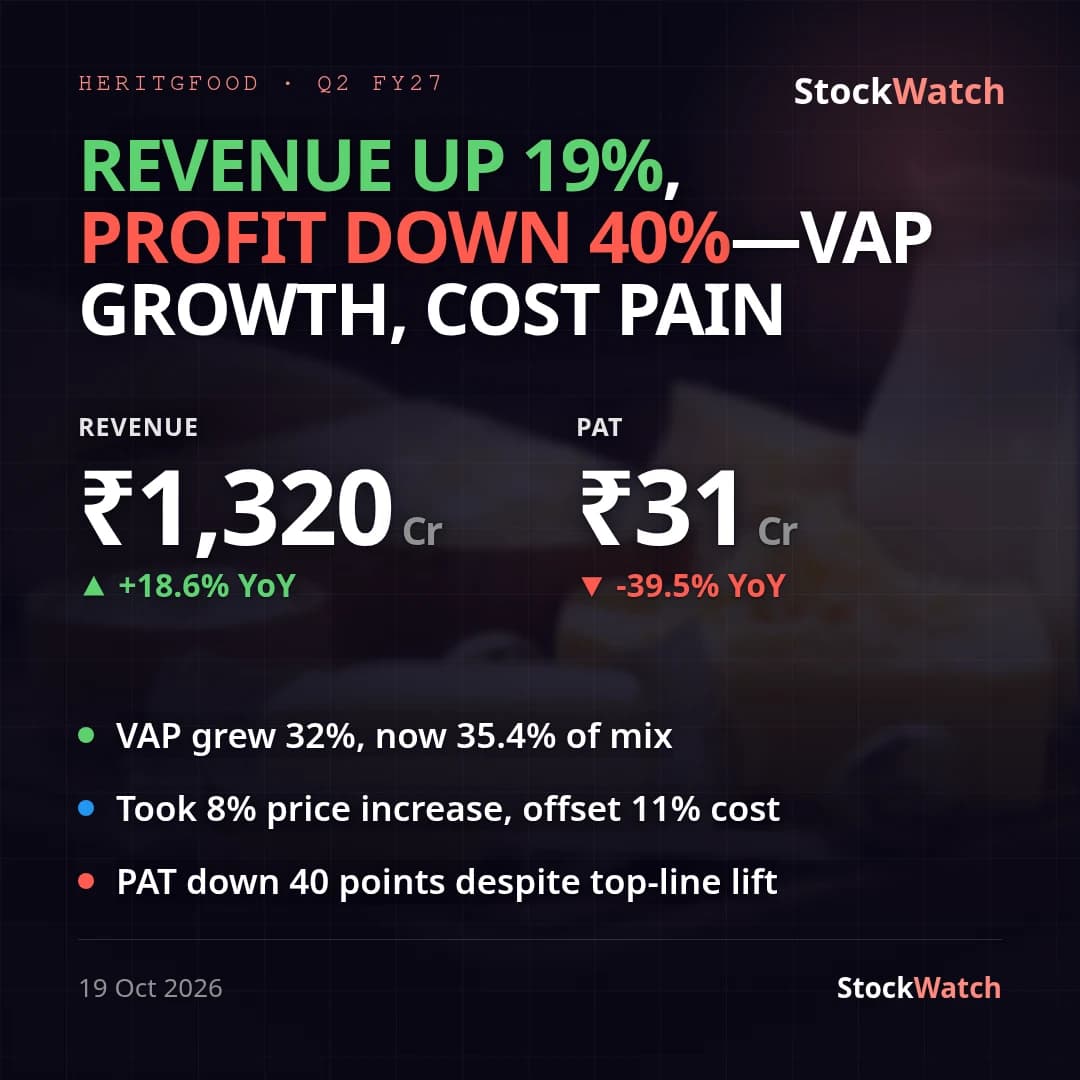
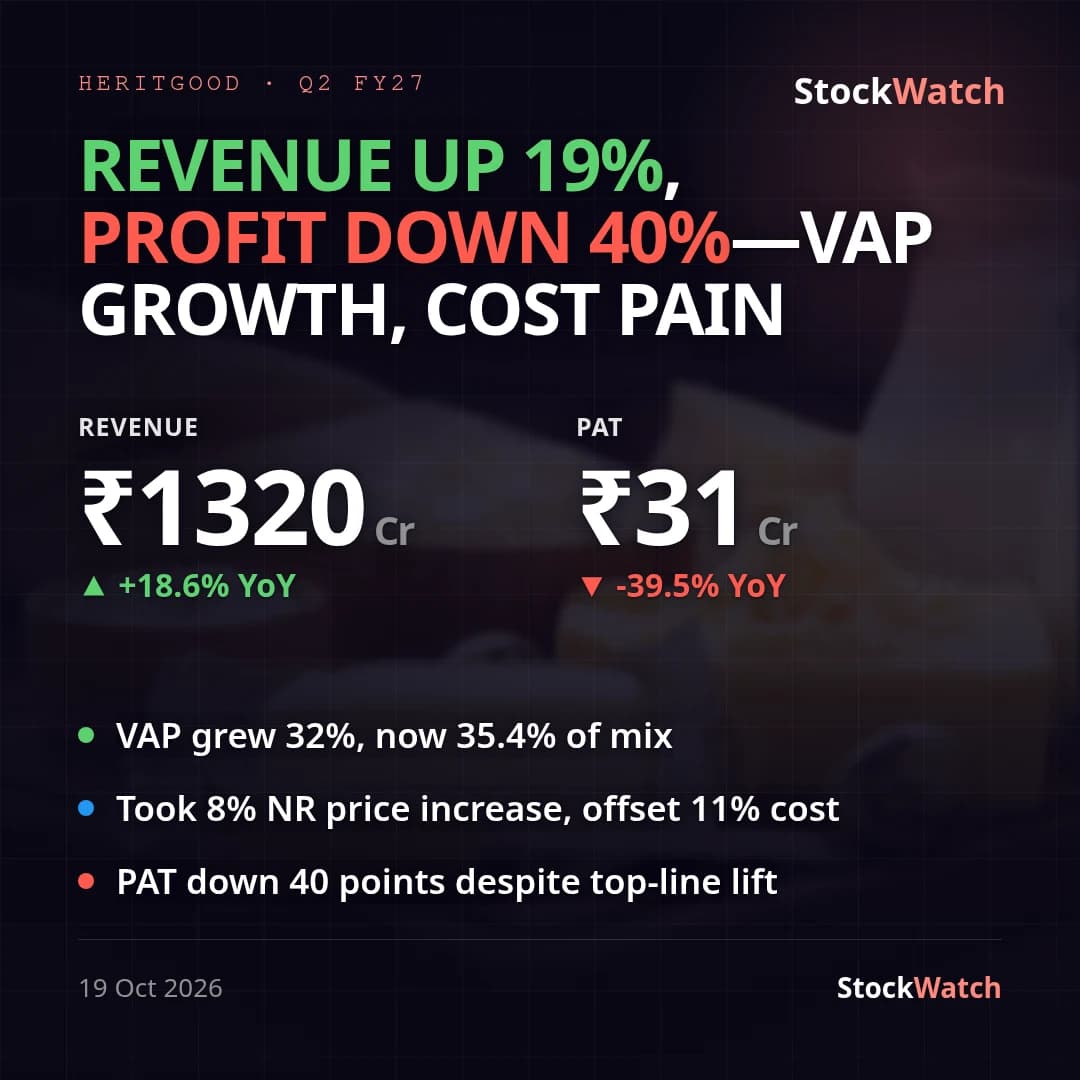
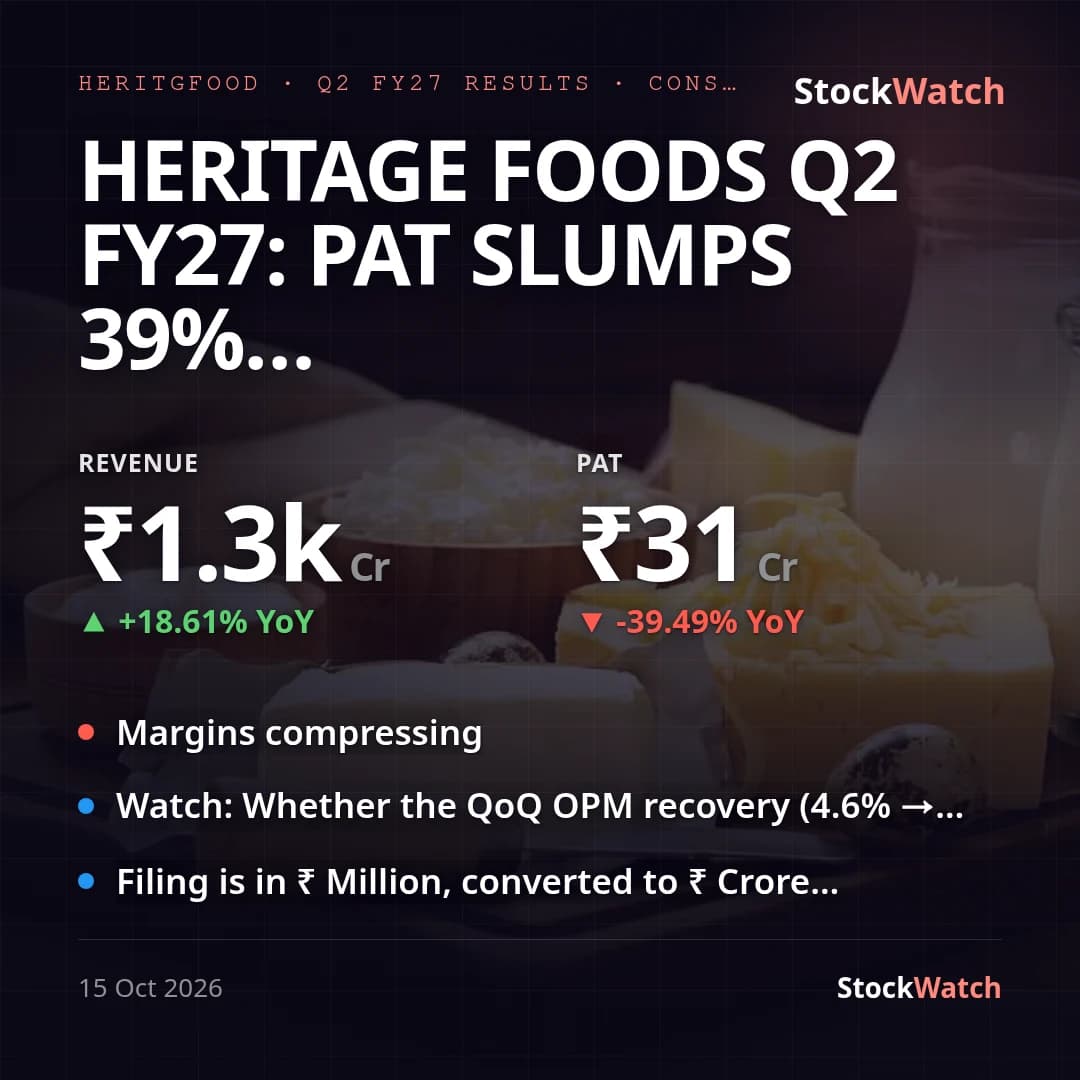
Heritage Foods Q2 FY27: PAT slumps 39% YoY on milk costs even as revenue grows 19%
Heritage Foods' consolidated PAT fell 39% YoY to ₹30.86 Cr even as revenue grew 18.6% YoY to ₹1,319.58 Cr, a divergence that marks this as a margin story, not a growth one. On an adjusted basis — stripping out a ₹9.36 Cr one-off gain (GST refund plus an interest-liability reversal) booked in the year-ago quarter — PAT still fell ~26% YoY, confirming the underlying pressure is real rather than a base-effect artifact. NPM compressed to 2.34% from 4.56% a year ago, a ~2.2 percentage-point hit consistent with the elevated milk procurement costs management flagged on the Q1 FY27 call as the dominant margin headwind.
Sequentially, the picture is better: PAT rose 23.6% QoQ and OPM improved to roughly 5.6% from ~4.6% in Q1 FY27, as the calibrated pricing actions and value-added-product (VAP) mix shift management described last quarter begin showing through. That still leaves the company short of the 'high single-digit EBITDA margin' target set out in the prior concall — this quarter's print should be read as on-track but not yet met, with the QoQ trend the key evidence either way. No management press release was available in the context for this result, so there is no quote to set against the numbers; that framing gap itself is worth flagging rather than guessed at.
No brokerage-specific consensus for this quarter's PAT or revenue could be confirmed via web search, so vsStreet is unknown rather than inferred. Segment data shows Dairy — still ~98% of revenue — grew 18.1% YoY to ₹1,288.77 Cr, in line with the group number. The quarter also carried corporate activity: the board approved the results on October 15, 2026, days after completing the acquisition of an additional 5.60% stake in subsidiary Heritage Novandie Foods Ltd (HNFL) on October 10, 2026, tightening control ahead of the ₹250 Cr FY27 capex earmarked for paneer and ghee capacity. Standalone PAT of ₹30.52 Cr and EPS of ₹3.29 track the consolidated numbers closely, with no material divergence between the two bases this quarter.