ICICI Bank Q2FY27: PAT +14.6% YoY to ₹16,333 Cr (consolidated), loan growth surges 30%
ICICI Bank's consolidated net profit for Q2 FY27 (quarter ended September 30, 2026) rose 14.6% YoY to ₹16,333.18 Cr, from ₹14,256.40 Cr a year ago, on consolidated total income of ₹88,161.18 Cr (interest earned ₹55,991.91 Cr, +16.2% YoY). Sequentially growth was far more muted — PAT was up just 0.8% QoQ from ₹16,209.74 Cr, even as interest earned rose 7.2% QoQ, pointing to some margin give-back within the quarter. Standalone (bank-only) PAT came in stronger at ₹14,843.03 Cr, +20.1% YoY (vs ₹12,358.89 Cr) — nearly 5.5 percentage points ahead of consolidated's 14.6% YoY growth. That gap is explained by minority interest, not bank-level weakness: insurance subsidiaries grew faster and a larger slice of their profit now sits with minority holders, pulling the consolidated YoY rate below standalone's.
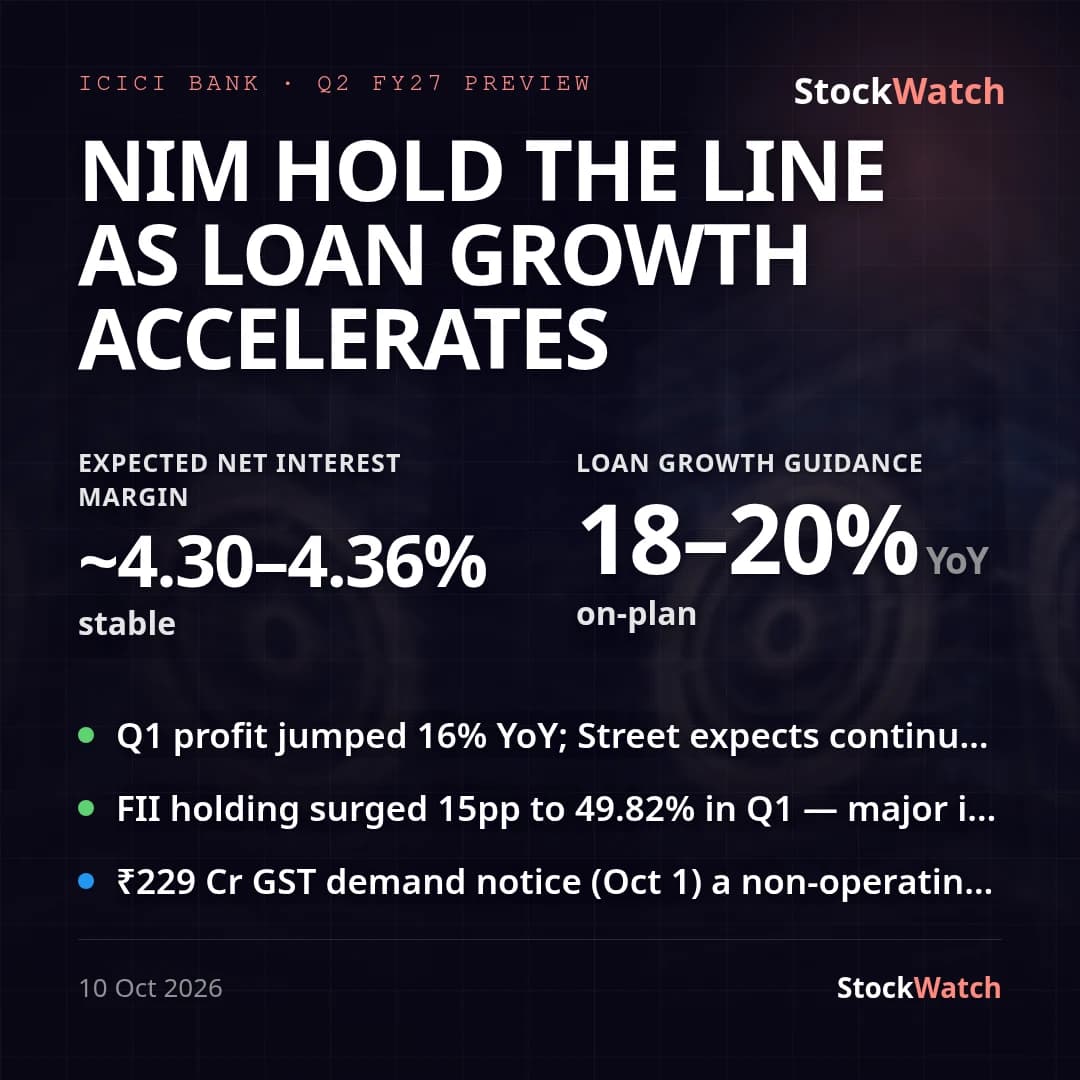
Net interest income (interest earned less interest expended) came in at ₹30,335.64 Cr consolidated, landing within the ₹30,200–31,000 Cr band flagged in our pre-result preview. Operating margin (operating profit before provisions ÷ total income) expanded to 27.2% from 26.2% a year ago, but eased from 28.4% in Q1 FY27 — a sequential moderation consistent with the QoQ profit slowdown. Provisions stayed benign: standalone provisions (other than tax) of ₹850.69 Cr were lower than ₹914.11 Cr a year ago, and asset quality improved across the board — gross NPA ratio fell to 1.20% (from 1.58% YoY and 1.38% in Q1 FY27) and net NPA ratio to 0.30% (from 0.39% YoY). Loan growth was the standout: consolidated advances rose ~29.7% YoY to ₹19,35,385 Cr (standalone +30.0% YoY to ₹18,31,580 Cr), well ahead of the 18–20% band the Street was pricing in pre-result. No exceptional items appear in either statement this quarter or a year ago, so no reported-vs-adjusted PAT gap arises.
Against our pre-result preview — which pegged PAT at ₹15,500–16,200 Cr and flagged NIM durability, loan growth and credit costs as the three watch items — the print beat on profit (above the top of range), beat decisively on loan growth, and credit costs stayed healthy, consistent with what management indicated on the prior concall (no formal quantitative FY27 targets were given, citing geopolitical uncertainty, but it guided to range-bound NIMs and 'risk-calibrated' loan growth — a stance the 30% YoY advances growth tests but doesn't contradict, since asset quality improved rather than deteriorated alongside it). This quarter's corporate developments add two threads: the Bank raised its stake in ICICI Life Insurance by 2.0% via stock exchange, recognizing ₹1,178.39 Cr of goodwill, even as Life Insurance's CEO Anup Bagchi resigned and was replaced by Sidharatha Mishra (October 2, 2026) — at a subsidiary now posting segment PBT up 25.5% YoY to ₹435.55 Cr. Separately, the Bank disclosed a ₹229 Cr GST demand notice received October 1, 2026, not reflected as an exceptional item in this result. No standalone press-release text was available in the context to cross-check against the filed numbers.
Heading into Q3 FY27, the key markers are whether NII holds near the ₹30,000+ Cr run-rate as deposit costs normalize, whether the ~30% YoY loan growth pace is sustainable without diluting underwriting quality, and whether the larger stake in ICICI Life Insurance begins to shrink the ₹1,055.68 Cr minority-interest drag on consolidated PAT.