Kaveri Seed Q1 FY27: consolidated PAT down 14% YoY on 13% revenue decline, margins flat
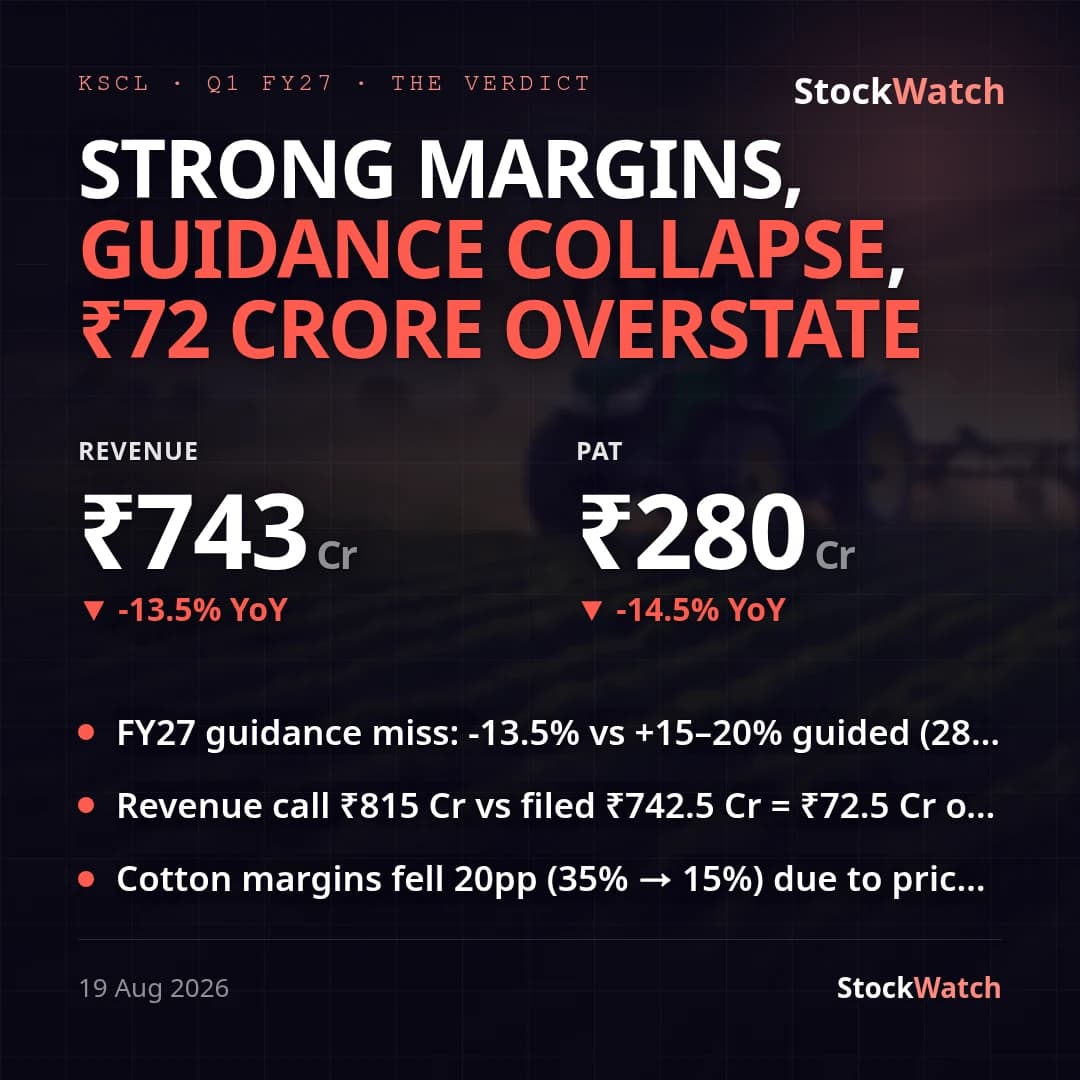
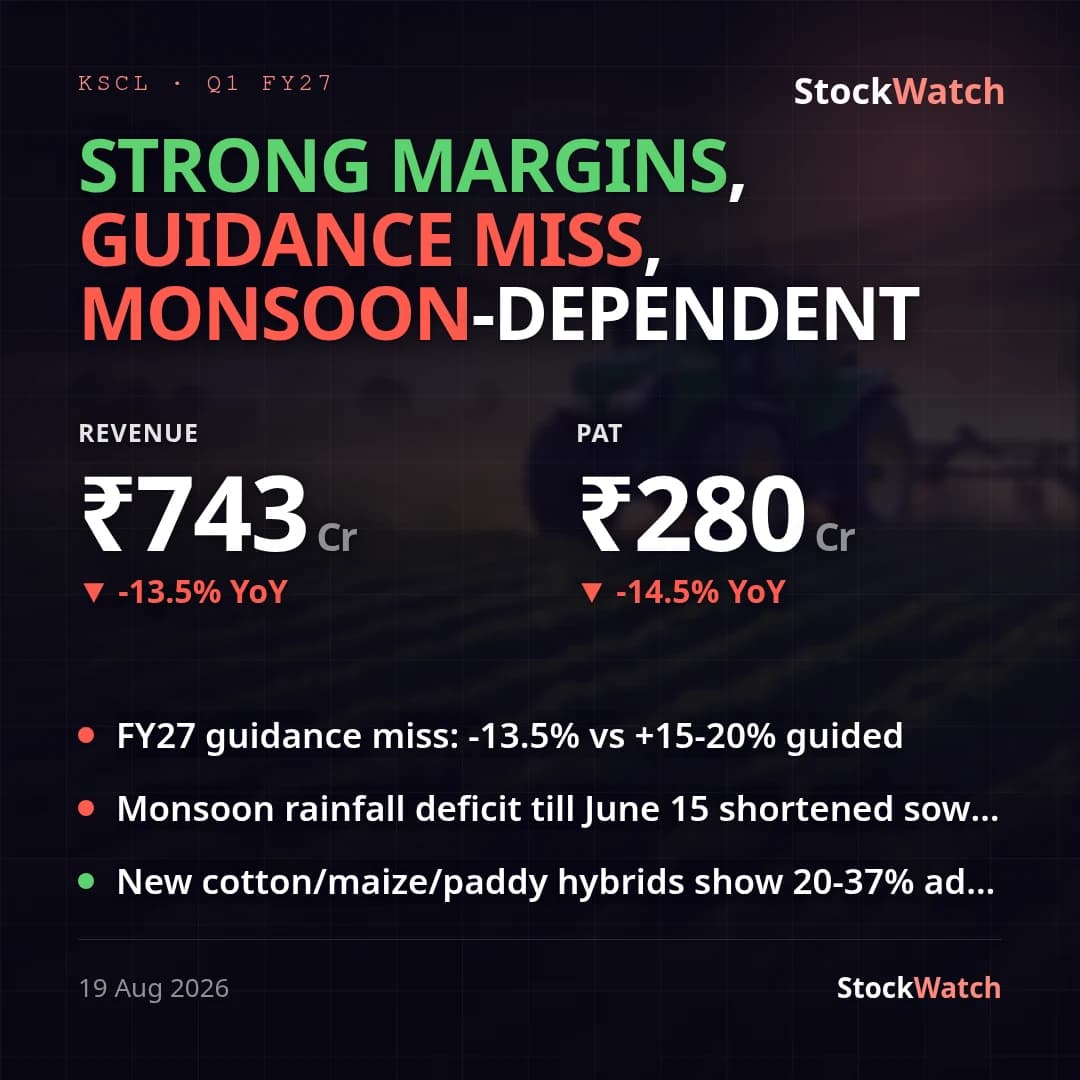
Kaveri Seed's consolidated Q1 FY27 revenue came in at ₹742.50 Cr, down 13.5% YoY from ₹858.53 Cr, with consolidated PAT of ₹279.84 Cr, down 14.5% YoY from ₹327.16 Cr (basic EPS ₹54.40 vs ₹63.76). Standalone tells the same story — revenue ₹815.00 Cr (-13.8% YoY) and PAT ₹271.30 Cr (-14.3% YoY) — so the two statements are directionally aligned, and neither period carries an exceptional item, keeping the comparison clean.
Margins held up despite the topline drop: consolidated OPM was ~39.6% versus 39.4% a year ago, and NPM slipped only marginally to ~37.5% from 37.7%, because cost of materials consumed and the inventory-change line fell roughly in step with revenue. The one cost pressure was employee benefits expense, up 21.9% YoY to ₹44.64 Cr (₹36.62 Cr a year ago), which the company has absorbed without denting margins so far. Sequentially, consolidated PAT swung from a ₹27.81 Cr loss in Q4 FY26 to this quarter's ₹279.84 Cr profit, but that reflects the normal kharif-season concentration of sales in Q1 for a seed company rather than an operational turnaround, and should not be read as momentum.
No numeric street consensus for the quarter turned up in a search; pre-print commentary (scanx.trade) had flagged expectations of robust growth from cotton, millet and hybrid-rice sales plus export strength, which the actual 13.5% YoY revenue decline runs counter to. Against management's own guidance from the May 2026 (Q4 FY26) concall — 15-20% FY27 revenue growth, cotton outperforming at over 20%, no price hikes, and margin gains from lower costs — this quarter's decline puts the full-year revenue target off-track one quarter in, even as the margin side of the guidance held roughly true. No company press release accompanying this filing was available to check management's own framing of the number against these figures. Corporate developments alongside the print include the CFO's retirement effective July 31, 2026, and a pending ITAT hearing (disclosed August 6, 2026) over a ₹69.5 Cr tax demand, a litigation item not yet reflected in the P&L.
With three quarters left in FY27, the company needs a sharp acceleration in Q2-Q4 to reach the guided 15-20% full-year growth band after this double-digit YoY decline in Q1; the ITAT outcome and whether employee-cost growth keeps outpacing revenue are the near-term markers to track.