Lotus Developers: consolidated PAT up 91% YoY to ₹88.5 Cr as margins expand past guidance
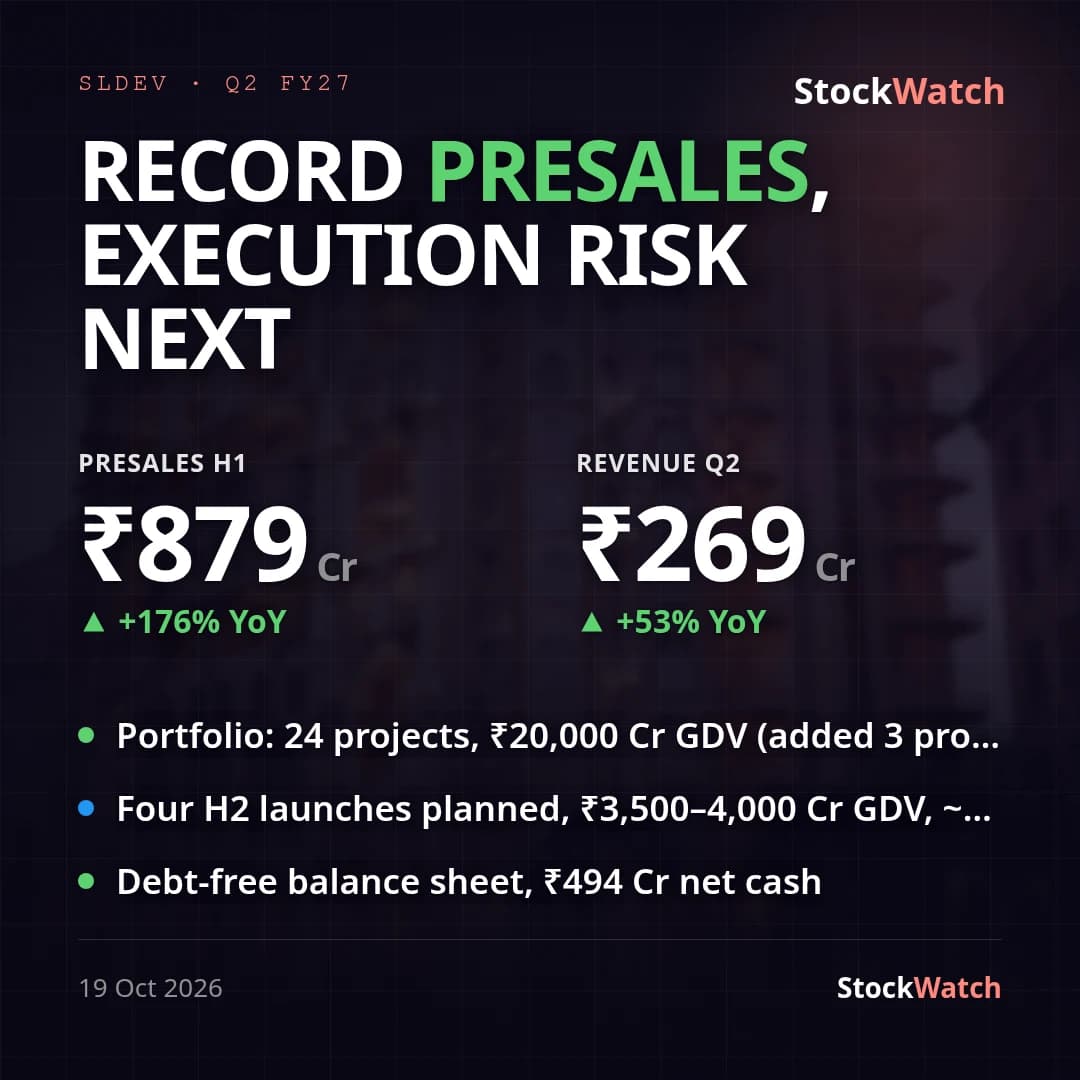
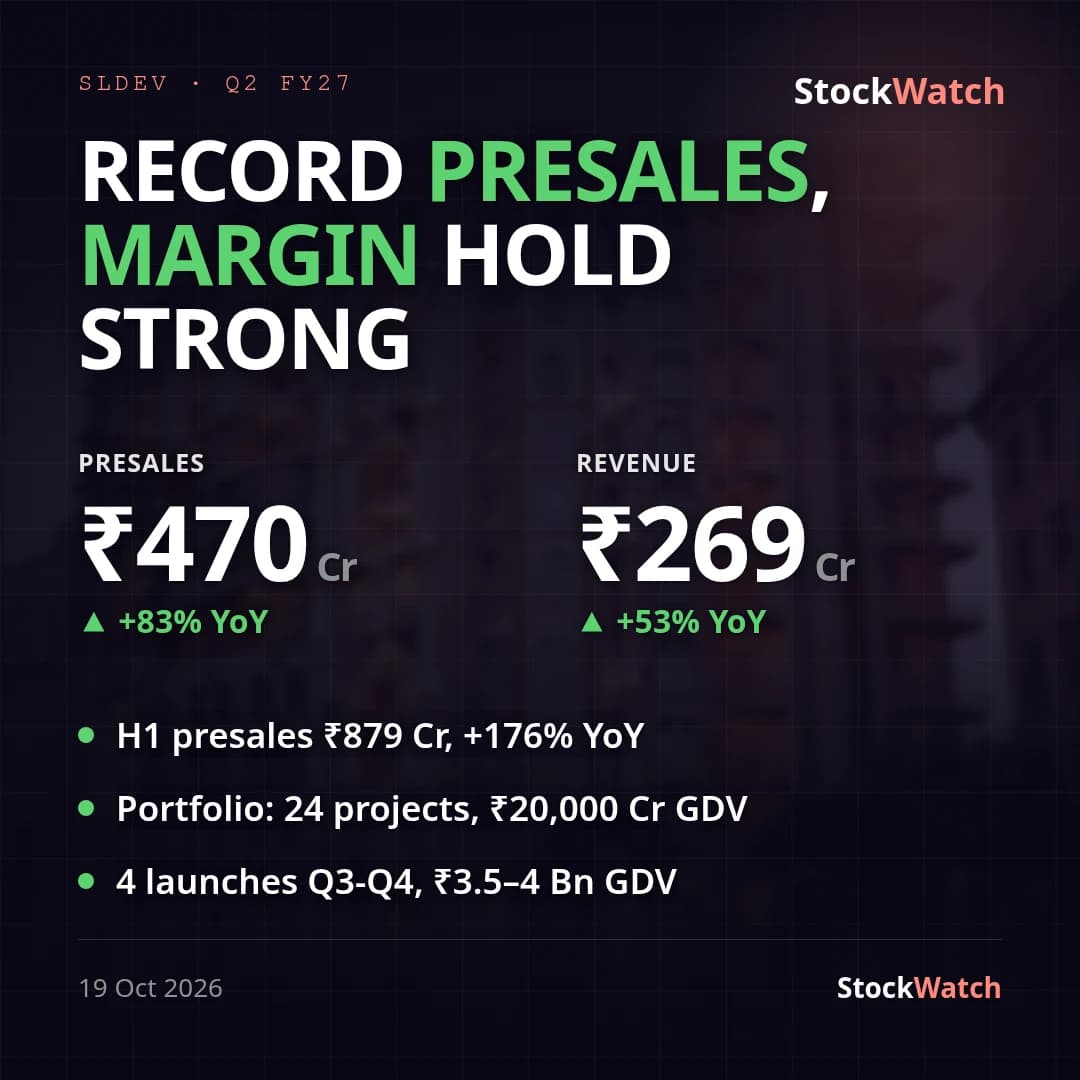
Sri Lotus Developers posted consolidated revenue from operations of ₹268.6 Cr, up 52.5% YoY (and up 102.9% QoQ from ₹132.3 Cr), with PAT of ₹88.5 Cr, up 90.9% YoY (up 93.6% QoQ from ₹45.7 Cr). Basic EPS came in at ₹1.68 against ₹0.98 a year ago and ₹0.93 last quarter. Net profit margin expanded to 31.5% of total income (from 24.6% YoY, 31.3% QoQ) and operating margin to roughly 39.9% of operating revenue (from 28.6% YoY, 36.4% QoQ), both on the back of cost of construction and development falling as a share of revenue once inventory movements are netted off.
The sharp QoQ jump reflects revenue recognition catching up on projects — Lotus Trident and Lotus Aquaria were launched near the end of Q1 FY27 and appear to be contributing meaningfully in Q2 — rather than any seasonal effect; the standalone entity itself booked almost no revenue (₹0.27 Cr PAT on ₹9.7 Cr of mostly other income), underscoring that all project economics sit at the subsidiary level.
Against management's own FY27 guidance (revenue/PAT growth of 55-60% YoY, EBITDA margin 35-40% — clarified to 33-36% in the last Q&A — and PAT margin 25-30%), this quarter's YoY revenue growth of 52.5% came in just under the guided floor, but PAT growth of 90.9% YoY and both margins (OPM ~39.9%, NPM 31.5%) beat their respective bands. Pre-result Street consensus (per our preview, uniformly bullish with Buy ratings and ₹230-270 targets) had pencilled in the same 50-60% revenue growth and 35-40%/25-30% margin ranges — this print lands at the low end on revenue and at or above the top end on margins and profit, so it reads as a margin-led beat rather than a volume beat; no company press release accompanied the filing to cross-check management's own framing, and presales for the quarter specifically are not disclosed in this financial statement, only the standing FY27 guidance of ₹1,800-2,000 Cr.
Corporate developments this quarter — a new Executive Director appointed October 1 (with a director resigning), a 2% promoter stake sale completed in early September to meet public shareholding norms, and a 30% (₹0.30/share) interim dividend approved September 1 and paid during the quarter with promoters voluntarily waiving their entitlement — are disclosed in the filing notes but don't move the P&L.