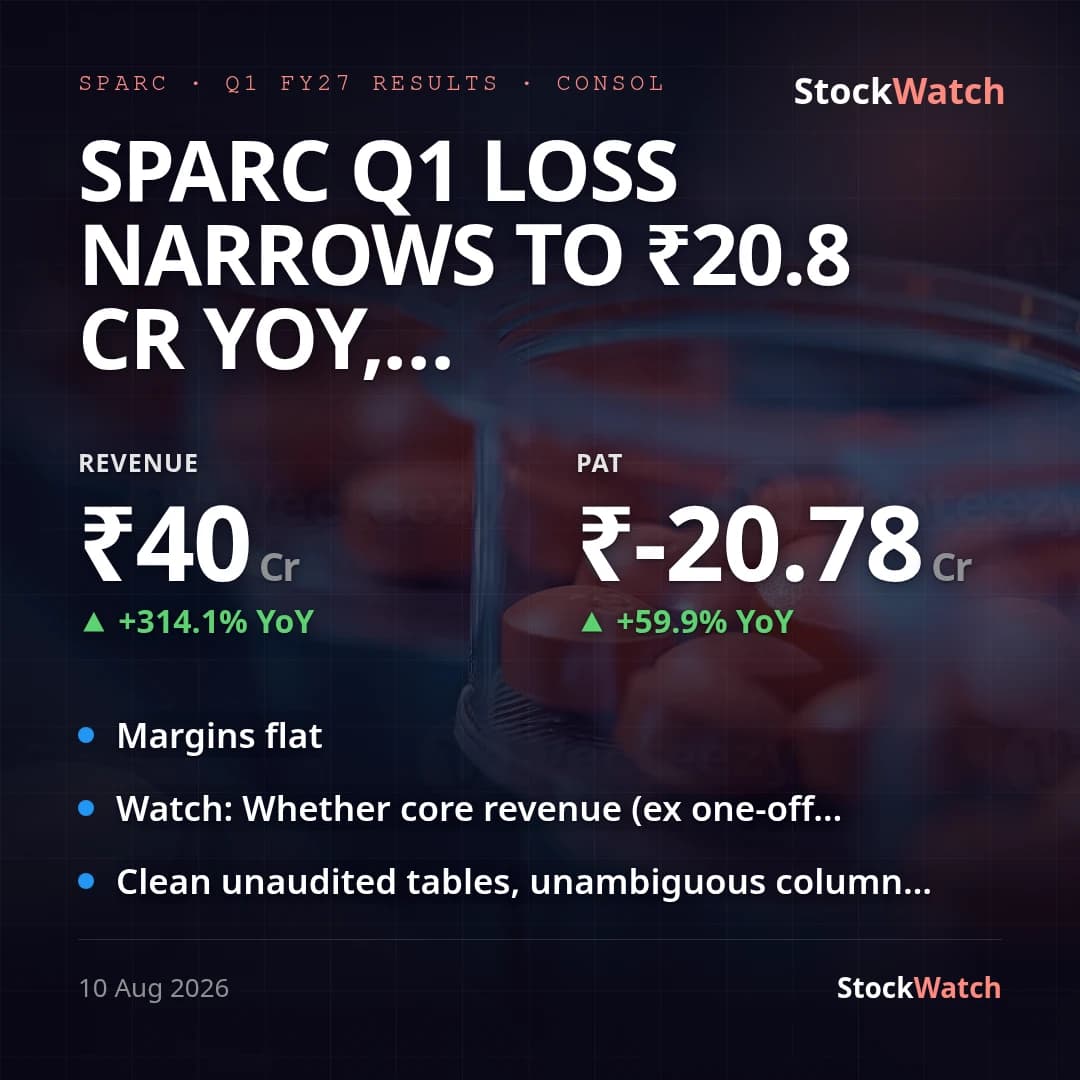
Sun Pharma Advanced Research Company (SPARC) posted a consolidated net loss of ₹20.78 Cr for Q1 FY27, narrower than the ₹51.87 Cr loss a year ago and the standalone loss of ₹20.98 Cr (basis divergence is immaterial — standalone and consolidated both show reported loss narrowing near 60% YoY). Revenue from operations jumped to ₹39.92 Cr from ₹9.64 Cr YoY (+314%), but ₹29.21 Cr of that — nearly three-quarters — is a one-off non-refundable consideration recognised on the mutual termination of the company's licensing agreement with CMS Bridging DMCC, alongside a USD 2 million (₹18.89 Cr) refund paid to CMS as part of the same settlement. Strip that item out and core revenue was ~₹10.7 Cr, essentially flat on last year's ₹9.64 Cr.
The margin/driver bridge follows directly from that one-off: reported consolidated PAT improved 59.9% YoY (standalone 59.7%), but adjusting both PBT and PAT for the ₹29.21 Cr termination revenue leaves an adjusted loss of roughly ₹49.99 Cr, only ~3.6% narrower than the year-ago ₹51.87 Cr loss. On an adjusted basis this is a flat, still deeply loss-making R&D-stage business, not the turnaround the headline number implies. Operating cost lines (employee benefits, clinical trial/product-development expense, professional charges, finance costs) were broadly stable to lower YoY at the standalone level, so the swing sits entirely on the revenue line, not on cost control.
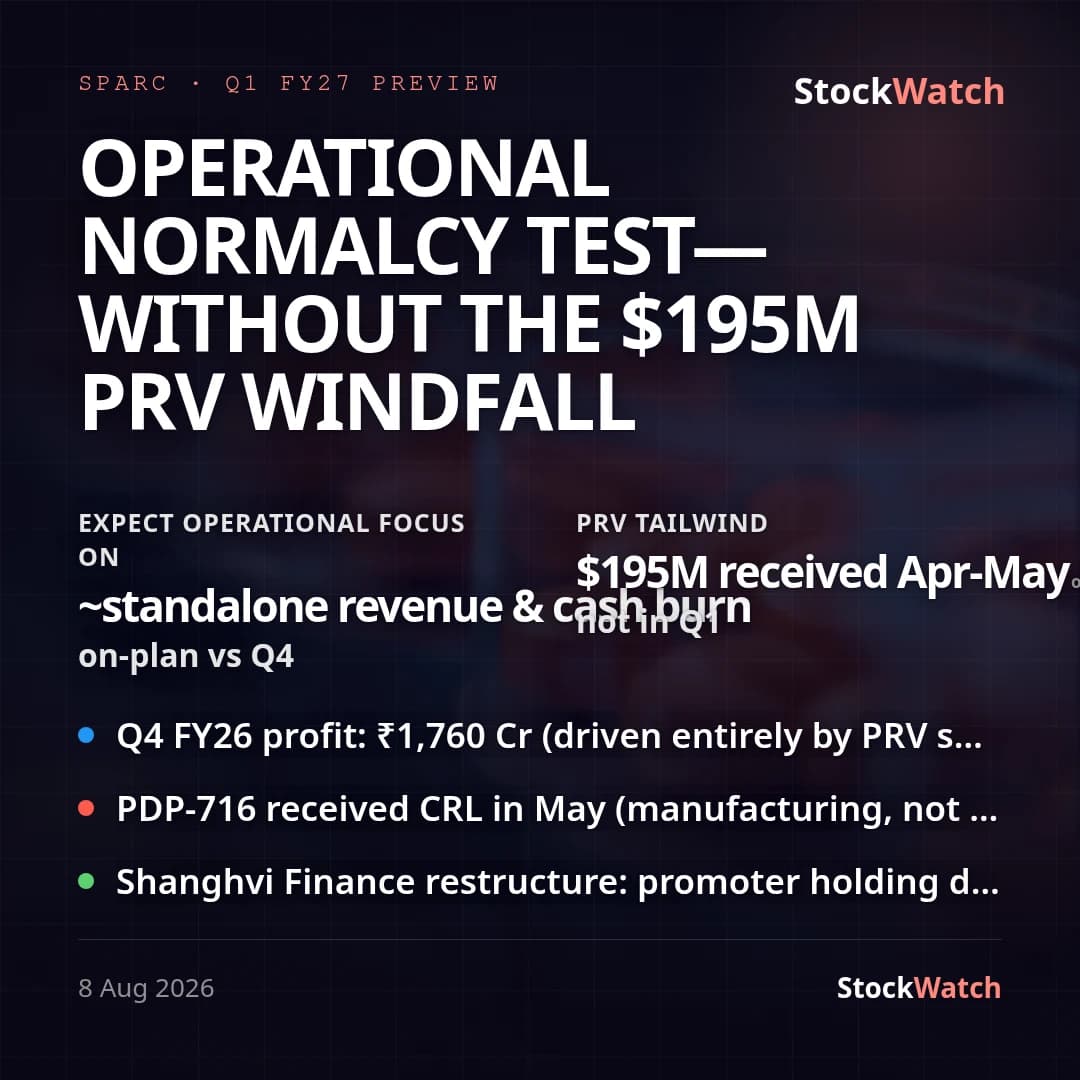
There is no formal management guidance on record for this business — SPARC does not issue quarterly guidance, and a web search for street/consensus estimates on this quarter found none (the stock is thinly covered for P&L specifics; available third-party material was limited to share-price targets, not revenue/PAT estimates) — so vsGuidance and vsStreet are both marked unknown rather than assumed. The QoQ swing from a ₹1,761.34 Cr consolidated profit in Q4 FY26 to this quarter's ₹20.78 Cr loss is not a sequential deterioration in the operating business: Q4 FY26 was inflated by a one-time ₹1,840.02 Cr gain from monetising a USFDA Priority Review Voucher for Sezaby®, sold in April 2026 for USD 195 million — an event-driven, non-recurring item unrelated to this quarter's run-rate. No separate management press release was available to cross-check against; the only company commentary was the regulatory outcome-of-board-meeting letter, which also disclosed approval of promoter-group reclassification requests (subject to Regulation 31A approvals) alongside the results.
Going into Q2 FY27, the read-through is that SPARC's core licensing/R&D revenue base remains small (~₹10-11 Cr/quarter) and lumpy, dependent on episodic monetisation events like the CMS termination fee and the Sezaby PRV sale rather than a recurring operating engine, with the underlying quarterly cash loss still running close to ₹50 Cr. The May 19, 2026 preferential warrant allotment to promoter entity Shanghvi Finance Pvt Ltd (3.85 Cr warrants at ₹155.80 each, 25% paid) leaves a ~₹450 Cr call obligation (₹116.85/warrant) due within 18 months — a funding event to track against the ongoing cash burn.