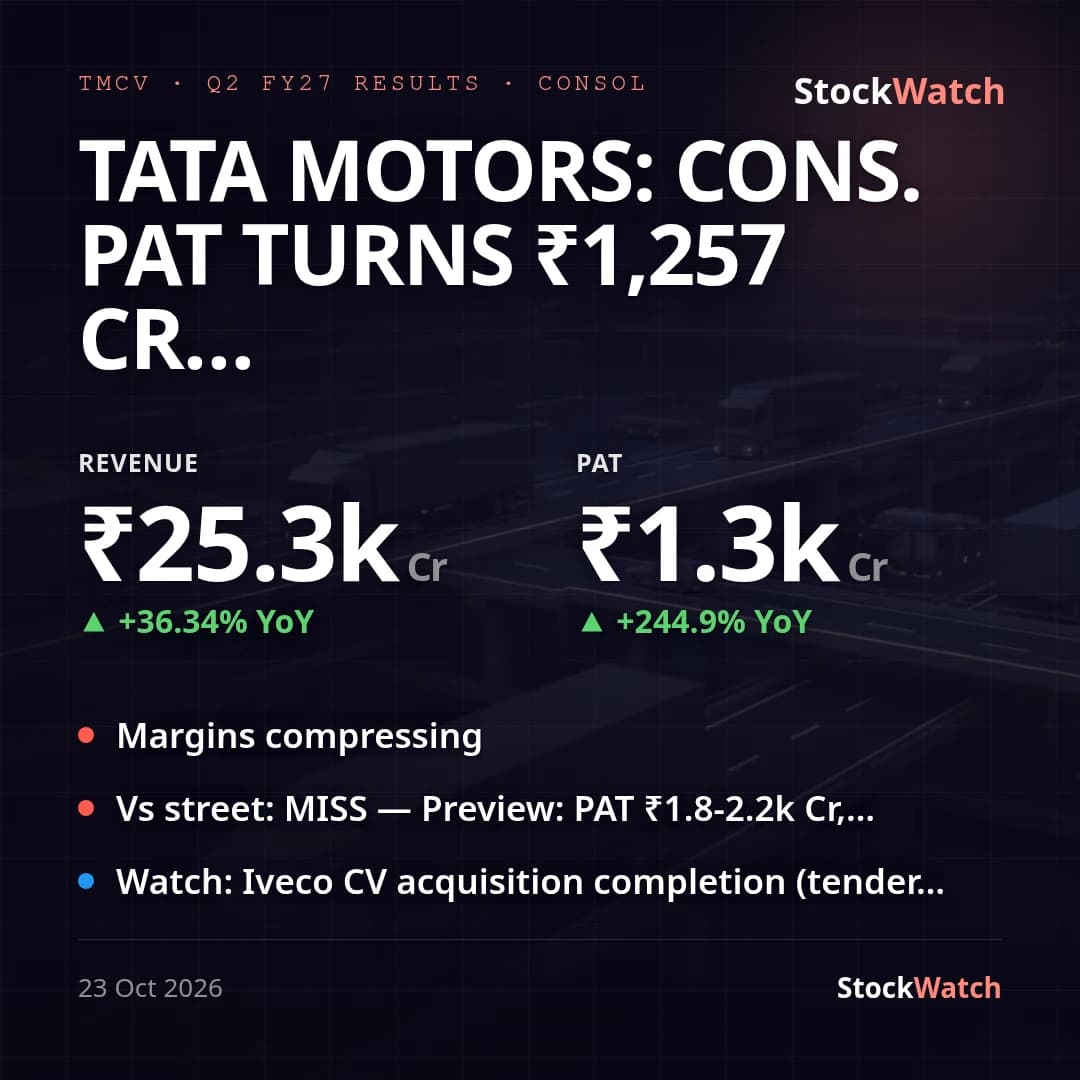
Tata Motors: cons. PAT turns ₹1,257 Cr YoY as revenue jumps 36%, margins stay tight
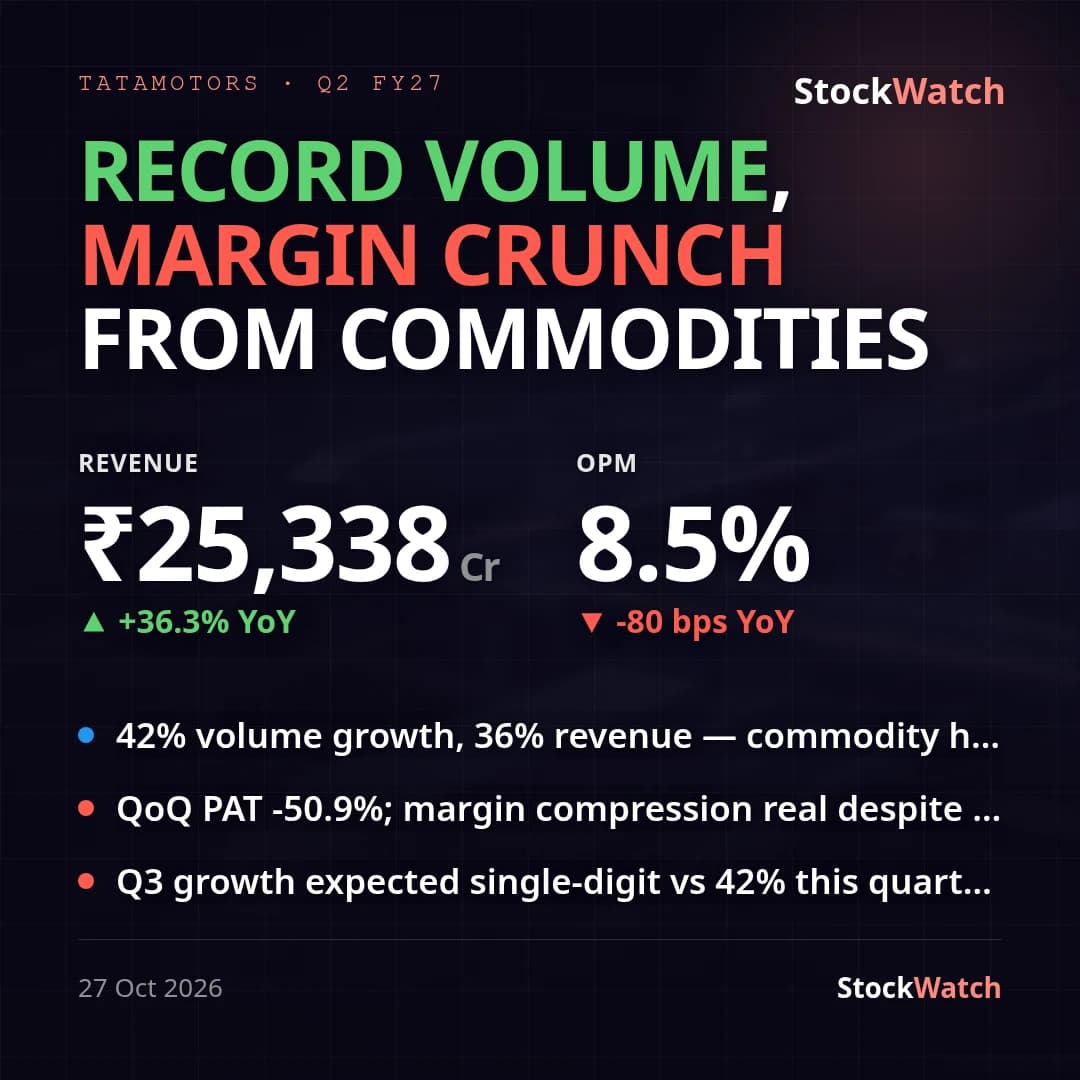
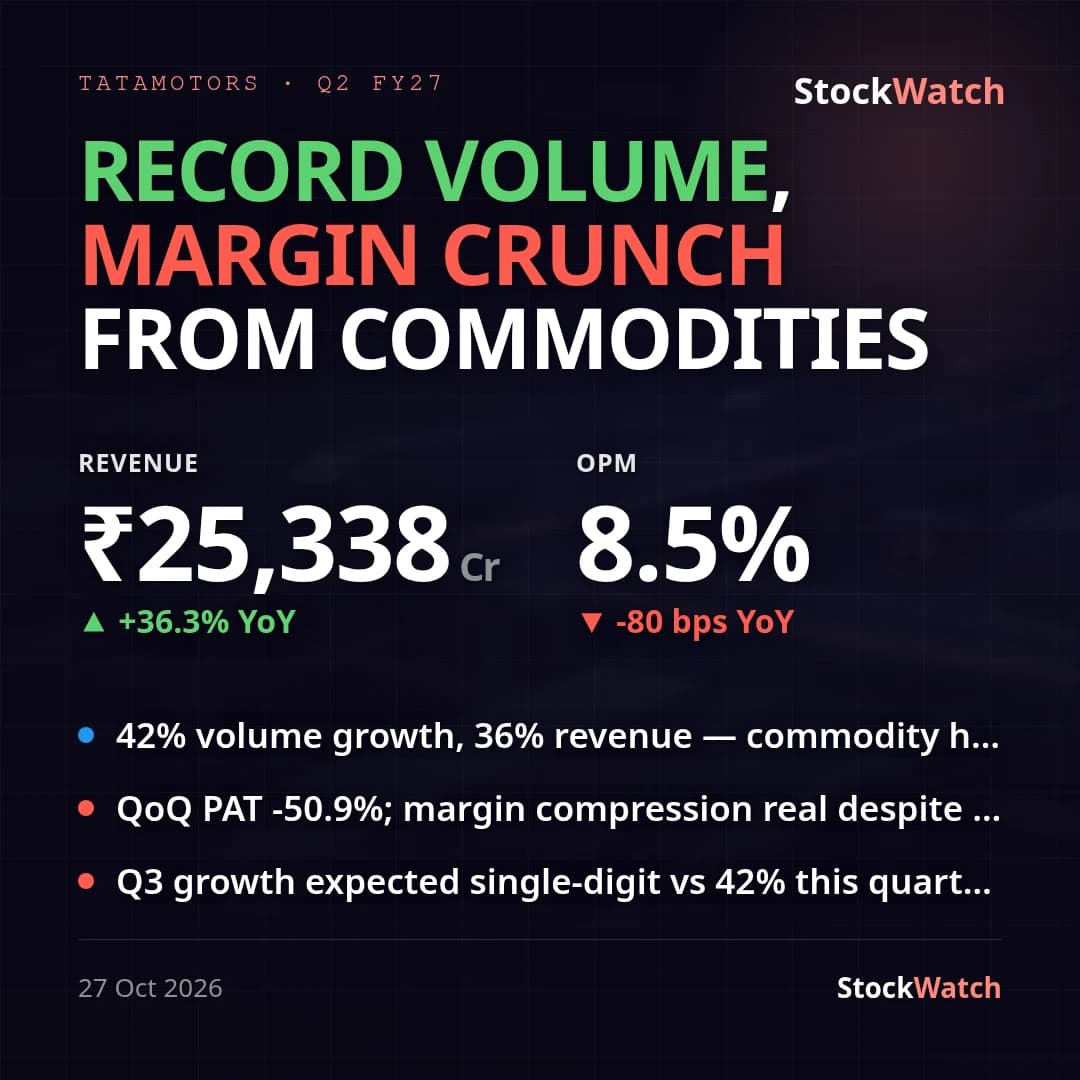
Tata Motors' consolidated revenue rose 36.3% YoY (and 22.6% QoQ) to ₹25,338 Cr for Q2 FY27, powered by a 42.7% jump in wholesale volumes to 135,114 units (domestic +30%, exports +177%). Consolidated PAT (attributable to owners) came in at ₹1,257 Cr, a reported swing from a ₹867 Cr loss a year ago, but down 50.9% sequentially from Q1's ₹2,560 Cr. Standalone, the primary CV entity, posted revenue of ₹23,930 Cr (+42% YoY) and PAT of ₹2,138 Cr against a ₹1,021 Cr loss a year ago.
The YoY swing to profit is flattered by comparison effects on both sides of the P&L. At the consolidated level, a ₹708 Cr fair-value loss on equity investments (likely the Tata Capital stake) dented this quarter's PBT, against a much larger ₹2,027 Cr loss in the year-ago quarter and a ₹1,135 Cr gain in Q1 FY27 — a swing large enough on its own to explain both the YoY jump and the QoQ drop. Stripping exceptional items and this FVTPL swing, adjusted PAT grew a more modest ~49% YoY, not the ~245% implied by the raw loss-to-profit comparison. Operating margin (OPM) was 11.00% this quarter, down ~144 bps YoY from 12.44% though roughly flat sequentially (10.88% in Q1), as steel and rubber cost inflation continued to outpace the July 2.5% price increase — management held margins sequentially through cost discipline rather than pricing fully offsetting input costs. Standalone's own one-off was different in nature: the year-ago quarter carried a ₹2,355 Cr impairment provision against an investment in a subsidiary/associate that doesn't repeat, which is why standalone's reported YoY swing (loss of ₹1,021 Cr to profit of ₹2,138 Cr) looks even larger than consolidated's.
Our pre-result preview had flagged revenue of ~₹23k Cr, EBITDA margin of 11.5-12.0% and PAT of ₹1,800-2,200 Cr as the bar to clear; the company beat on revenue (₹25,338 Cr) but missed on PAT (₹1,257 Cr), with margin landing just under the expected band. Against management's own prior guidance of 'healthy double-digit growth' for the quarter, the 36% YoY and 42.7% volume growth is a clear beat, though the commodity-cost commentary confirms the margin caution flagged on the last call rather than the fuller price pass-through the July hike implied. The quarter's other corporate developments — the Iveco tender offer price raised to €14.40/share on October 9 ahead of an October 26 acceptance deadline and a targeted month-end settlement, a 26% stake acquisition in an e-mobility firm, and an NSE 'Leader' ESG score — don't yet show up in these numbers but set up next quarter's consolidation scope.
Free cash flow of ₹4.6K Cr (standalone, up ₹2.4K Cr YoY) pushed net cash to ₹11.3K Cr standalone and ₹15.9K Cr consolidated, giving balance-sheet room for the Iveco close. CFO GV Ramanan flagged Iveco integration as the near-term priority 'as we prepare for consolidation from next quarter,' while MD Girish Wagh guided H2 growth to moderate against a higher base even with H1 volumes up 35%. The next print will show whether cost discipline can hold the 11% OPM line as the comparison base normalizes and whether the FVTPL swing factor settles down.