UCO Bank Q2 FY27: standalone PAT +27% YoY to ₹785.64 Cr; credit growth beats guidance
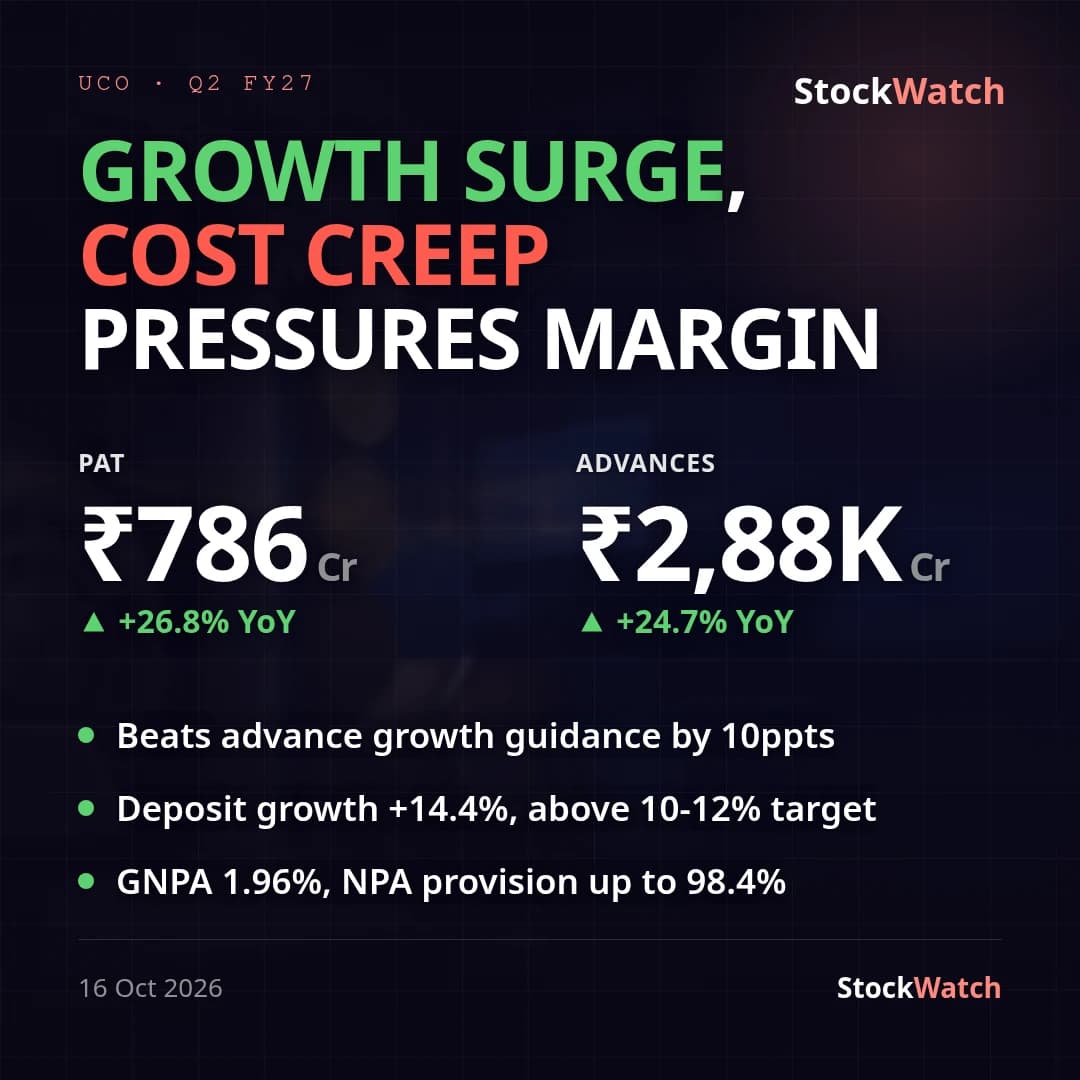
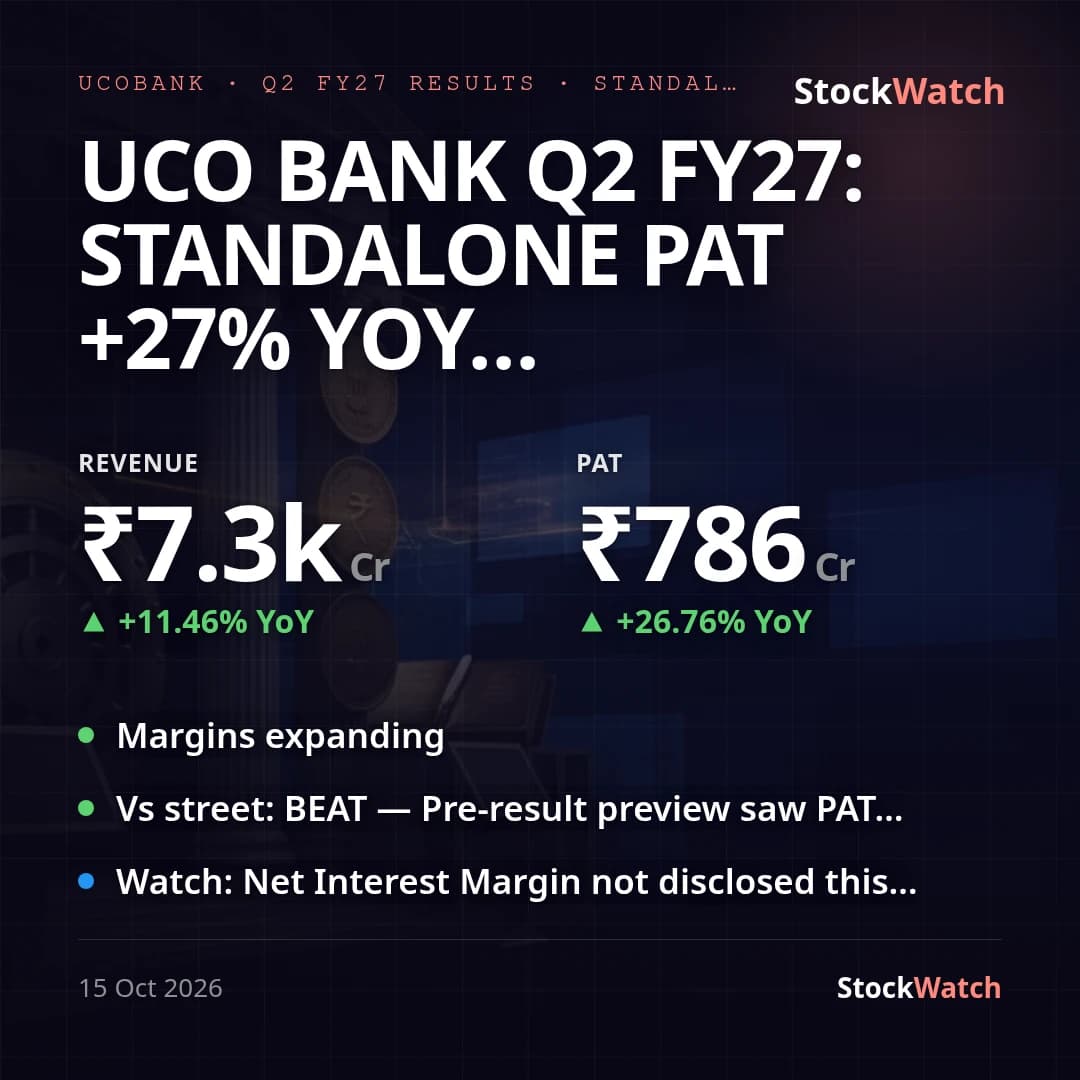
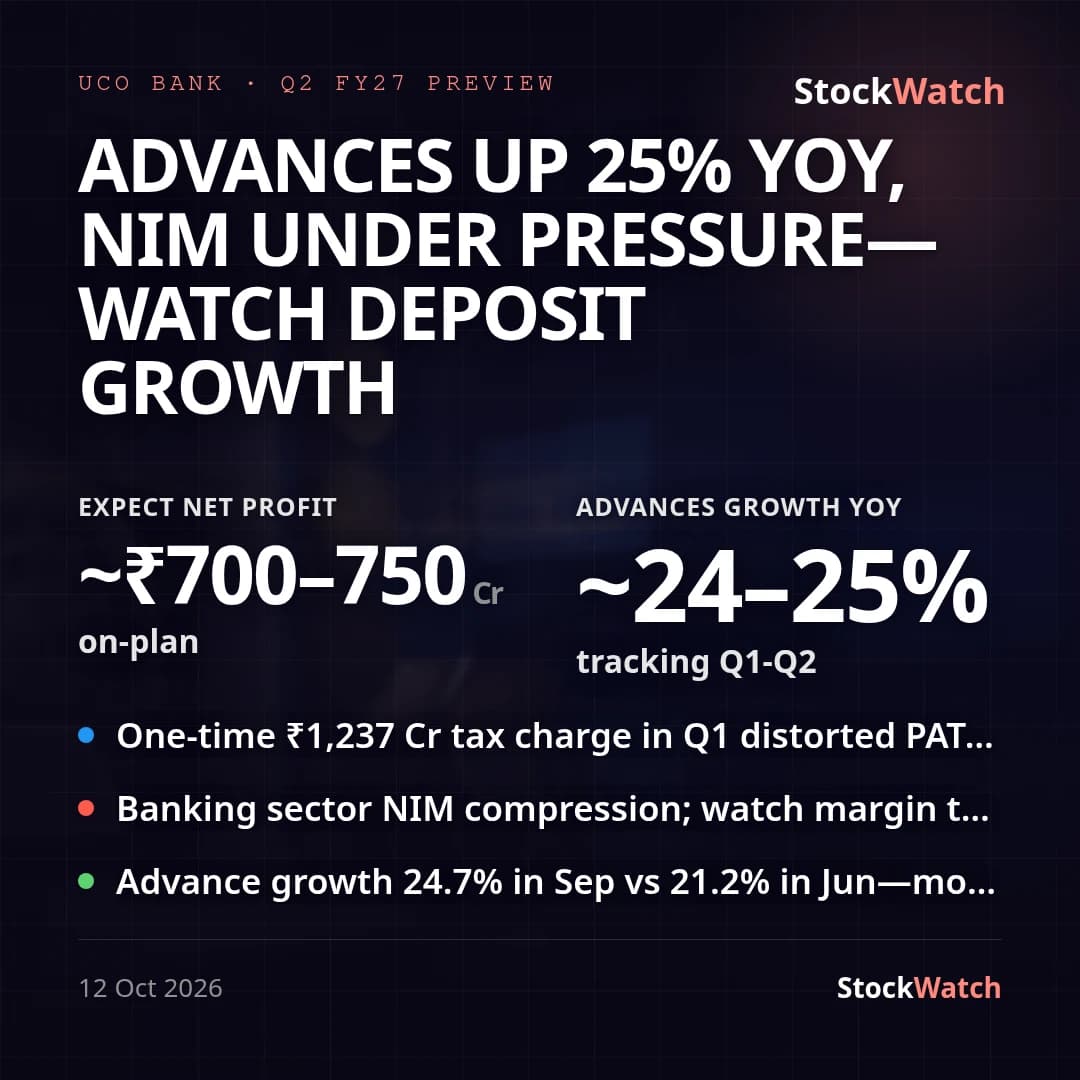
UCO Bank's standalone net profit for Q2 FY27 rose 26.8% year-on-year to ₹785.64 Cr from ₹619.76 Cr, on interest earned of ₹7,286.32 Cr (+11.5% YoY). No consolidated statement was filed this quarter. The print lands above our pre-result preview's ₹700–750 Cr expectation band — a beat — though the only external estimate found was an FY27E annual PAT figure of ~₹3,721 Cr (HDFC Sky), implying a quarterly run-rate this result is broadly tracking. Management's prior guidance (July 2026 concall) targeted FY27 credit growth of 12-14% and deposit growth of 10-12%; actuals of 25.2% and 14.4% YoY respectively clear both bands, with advances the standout beat.
The PAT-vs-PBT gap is the real story: PBT grew just 3.9% YoY (₹1,025.07 Cr to ₹1,064.69 Cr) while PAT grew 26.8%, because the effective tax rate fell from 39.5% to 26.2% following the bank's move to the Section 115BAA regime. That benefit was partly offset within the quarter by a ₹267.19 Cr deferred-tax-asset reversal (Note 13) — stripping that out, adjusted PAT would be ~₹1,052.83 Cr, an adjusted YoY increase of ~69.9%, materially stronger than the 26.8% reported figure. Sequentially, PAT rose 19.7% QoQ, but that compares against a Q1 FY27 base that itself absorbed a separate ₹1,237.13 Cr one-time tax charge (Note 12) — the QoQ jump is a one-off base effect, not fresh momentum, and total income actually fell 5.9% QoQ as other income dropped 47% to ₹887.76 Cr from ₹1,686.24 Cr, pulling operating margin down to 22.91% from 32.36% in Q1. On a YoY basis — the primary read — both NPM (9.61% vs 8.35%) and operating margin (22.91% vs 21.74%) expanded.
Asset quality and capital both improved against the backdrop of the quarter's events (trading-window closure for results, benchmark-rate revisions, staff strikes on Sep 11/28-30): Gross NPA fell to 1.96% from 2.56% YoY, Net NPA to 0.18% from 0.43%, and the Provisioning Coverage Ratio rose to 98.36% from 96.99%. CRAR improved to 18.85% (CET-1 17.06%) from 17.89% (CET-1 15.61%) a year ago. All of this is consistent with the pre-result Street read — thin analyst coverage, a ₹32 consensus target, and a thesis built on clean asset quality and advance growth — which this print reinforces rather than contradicts. No standalone management press release was extracted alongside the filing, so there is no separate management framing to reconcile against the numbers beyond the notes to accounts.
What's unresolved: the filing does not disclose Net Interest Margin directly, so the prior 2.8-2.9% NIM guidance remains unverified pending next quarter's disclosure or a post-results call. A rough cost-to-income calculation (opex over NII+other income) comes in near 50.3%, marginally above the bank's own <50% ceiling, though this is Street arithmetic rather than a bank-disclosed ratio and should be read as indicative only — particularly given the Q2 other-income dip that would affect the denominator. Advances outpacing deposits (25.2% vs 14.4% YoY) also pushed the credit-deposit ratio higher, a funding-mix point worth tracking into Q3.