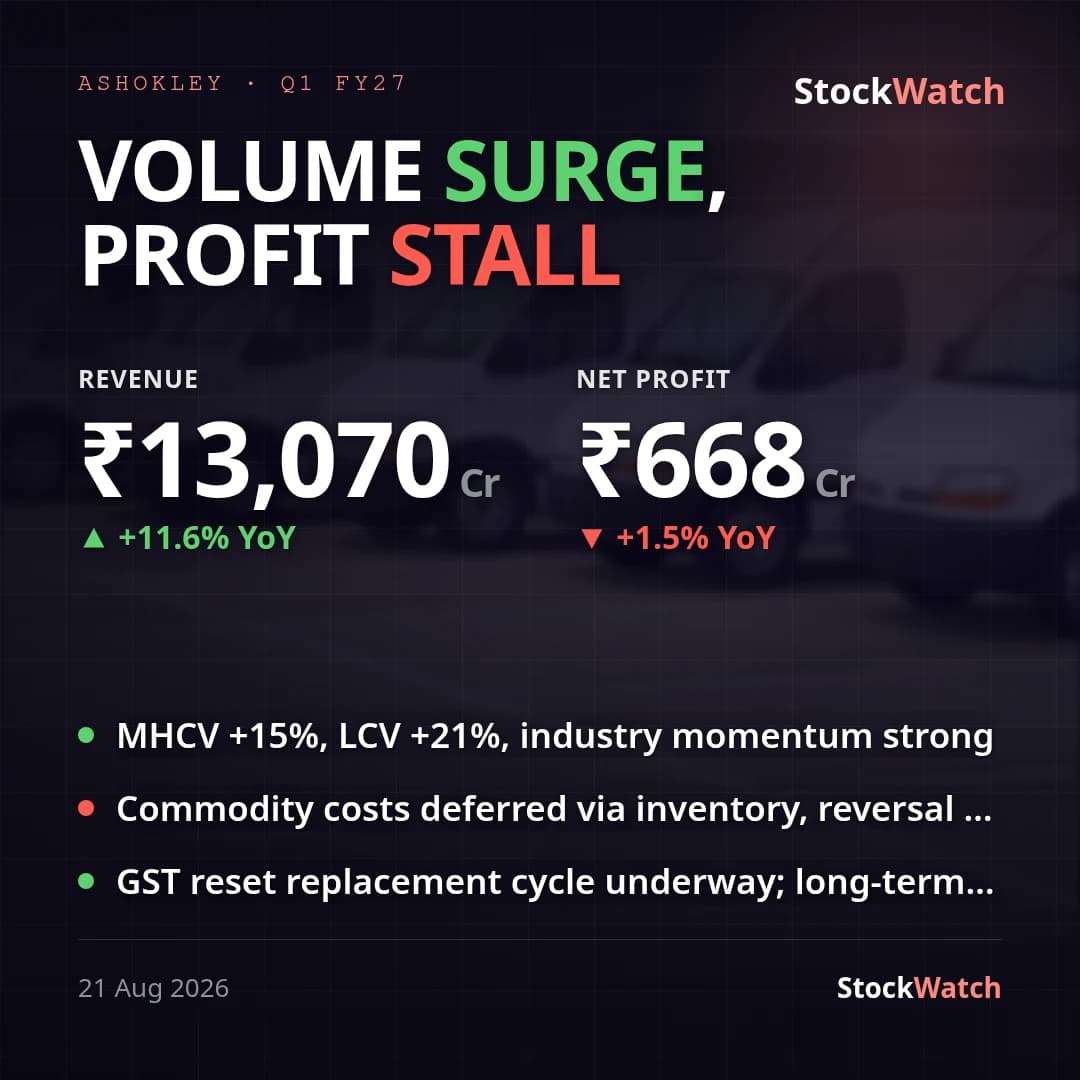
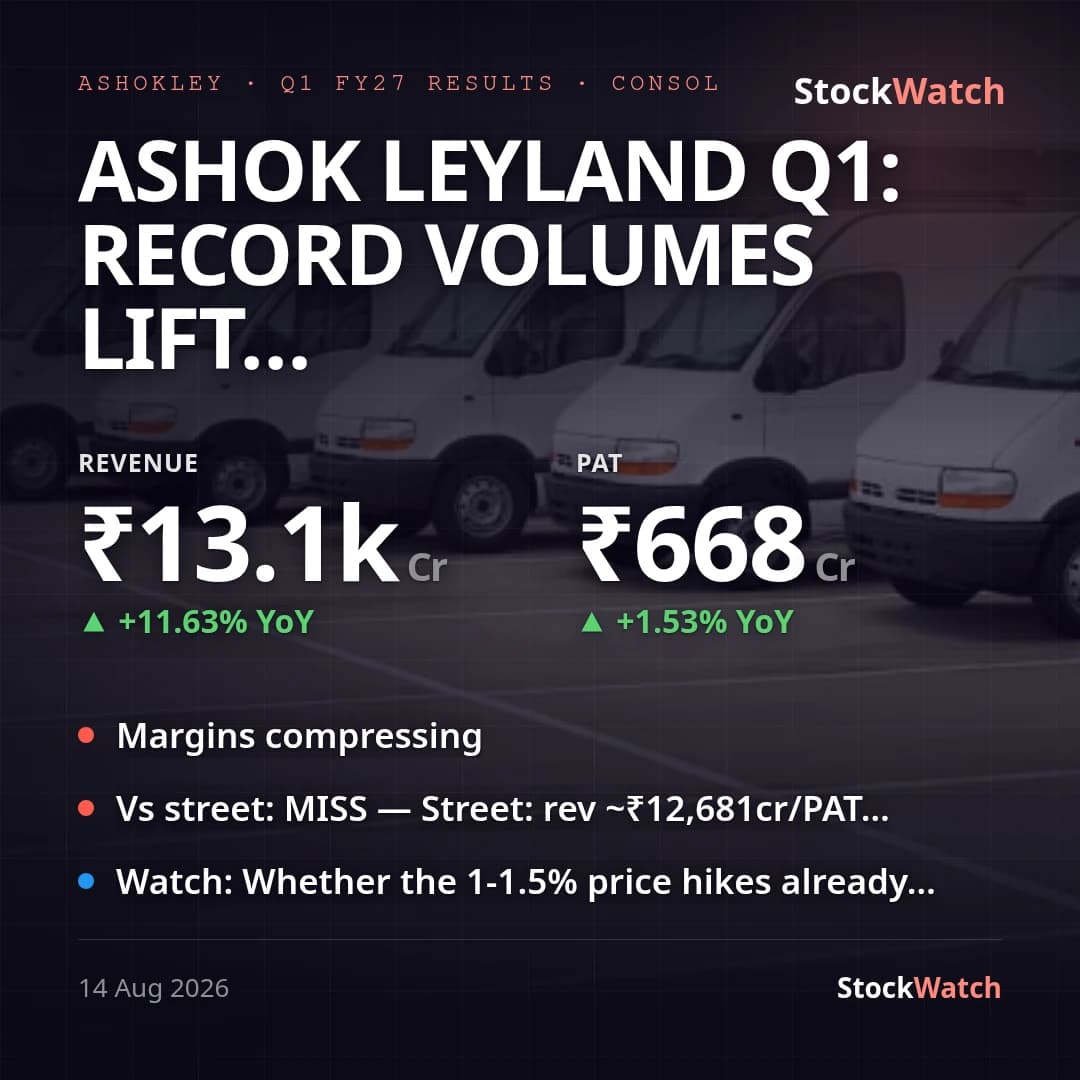
On a consolidated basis (primary), Ashok Leyland posted revenue of ₹13,069.59 Cr, up 11.6% YoY from ₹11,708.54 Cr, but consolidated PAT (including non-controlling interest) of just ₹667.77 Cr, up only 1.5% YoY from ₹657.72 Cr — sharply lagging revenue growth and well short of the ~14% YoY PAT growth Street had priced in. The 24.2% QoQ revenue decline from Q4FY26's seasonally strong ₹17,246.44 Cr is a routine post-year-end slowdown for the CV cycle, not a red flag. Standalone — the basis management chose to headline in its press release — told a stronger story: revenue ₹9,634.35 Cr (+10.4% YoY) and PAT ₹609.11 Cr (+2.6% YoY), both "highest-ever Q1" on record CV volumes of 48,763 units (+10.2% YoY, led by 15% MHCV truck growth ex-Defence and 21% domestic LCV growth).
The gap between the two bases traces to core segment profitability being essentially flat-to-down: the Commercial Vehicle segment's profit before interest and tax slipped to ₹701.86 Cr from ₹707.82 Cr, and Financial Services segment profit fell to ₹171.87 Cr from ₹178.22 Cr as impairment/write-off charges on financing receivables jumped 47.8% YoY to ₹471.96 Cr (from ₹319.32 Cr) inside Hinduja Leyland Finance. What actually lifted consolidated PBT to ₹949.72 Cr was other income nearly doubling to ₹188.65 Cr (from ₹98.66 Cr), even as segment interest expense rose 21% to ₹118.80 Cr. Management's own commentary confirms the squeeze on the standalone P&L: EBITDA margin fell to 10.1% (₹970 Cr) from 11.1% in Q1FY26 "owing to rising material costs," consistent with consolidated net profit margin compressing to 4.41% from 5.06% YoY and operating margin slipping to 9.15% from 9.72% (ex-financial-services basis).
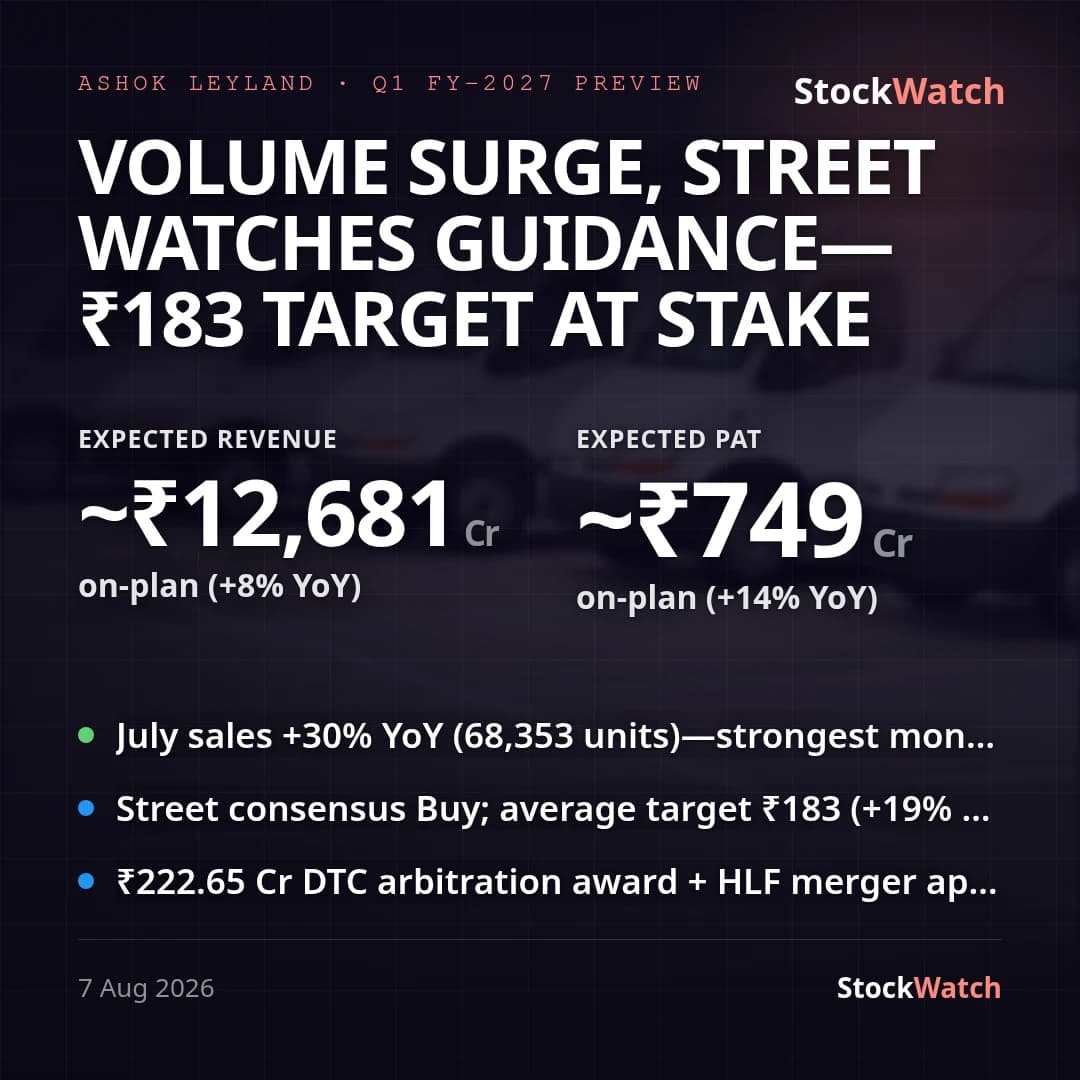
Street consensus (33-analyst FY27 estimates via Univest) had modeled ₹12,681 Cr revenue (+8.3% YoY) and ₹749 Cr PAT (+13.9% YoY) for the quarter; the actual print beat on revenue but missed materially on profit growth, validating rather than contradicting the Street's recent target cuts (₹198 to ₹183, with 22 Buy/11 Hold/1 Sell of 32 analysts). On the corporate-action front, the Hinduja Leyland Finance-into-NDL Ventures merger cleared its NCLT-directed shareholder and creditor meetings on July 30, 2026 with requisite majority support, and the Company allotted ₹300 Cr of NCDs on August 10, 2026 — both financing-side moves rather than operating catalysts. Net cash improved to ₹2,252 Cr, a ₹1,432 Cr positive YoY swing, giving some balance-sheet cushion against the cost pressure.
Management's prior guidance (Q3FY26 concall) had flagged "temporary gross margin compression" to be recovered "through price realization improvements and ongoing cost-saving efforts" — that recovery has not shown up yet; margins compressed further instead. Chairman Dheeraj Hinduja and MD Shenu Agarwal both reiterated confidence in demand, citing the government's Parivartan fleet-modernization push, and reaffirmed price-realization and cost-saving initiatives as the offset to commodity inflation, but neither issued specific FY27 numeric guidance in this release. The next checkpoints are whether the 1-1.5% price hikes already implemented feed through to Q2 margins, and whether the NBFC write-off run-rate normalizes.