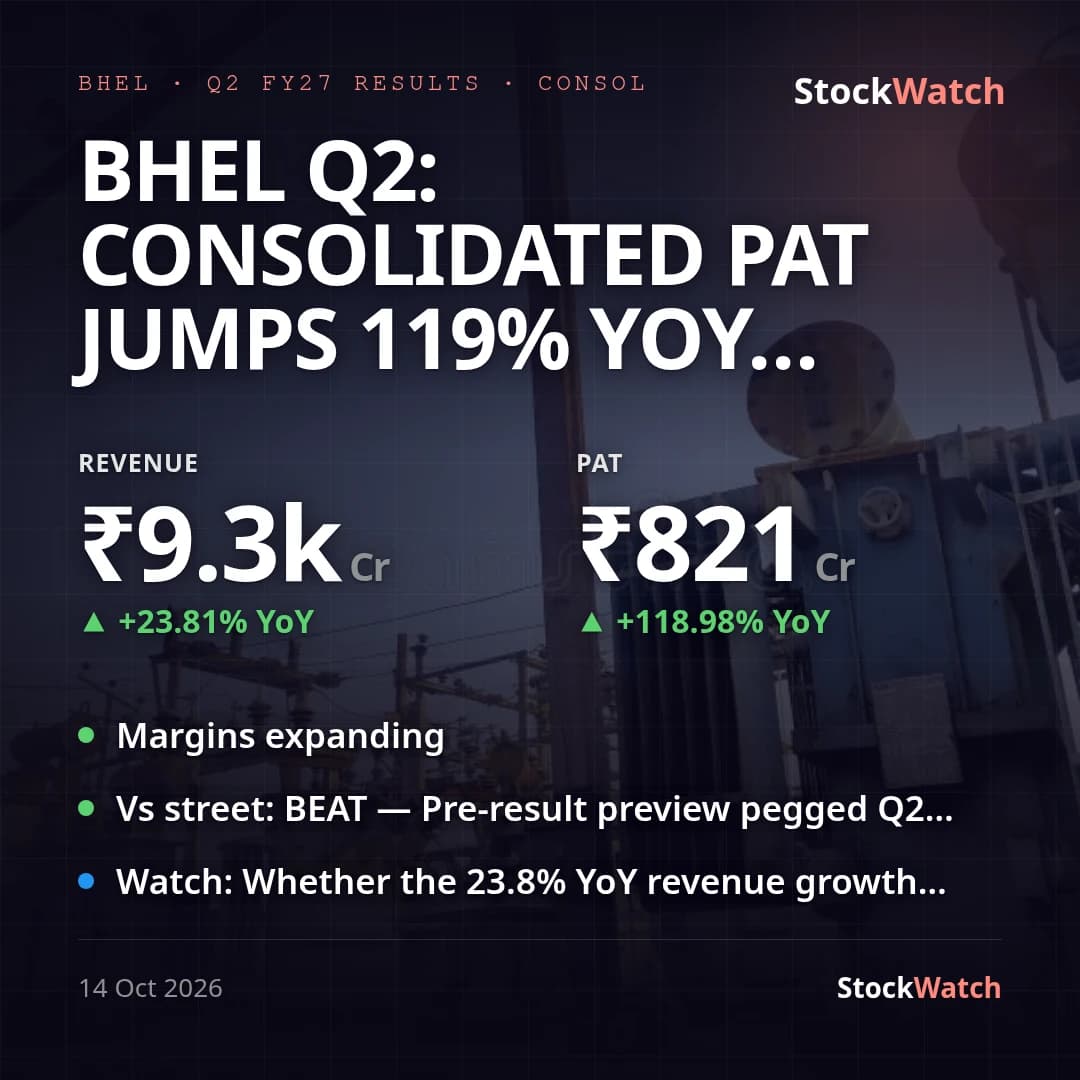
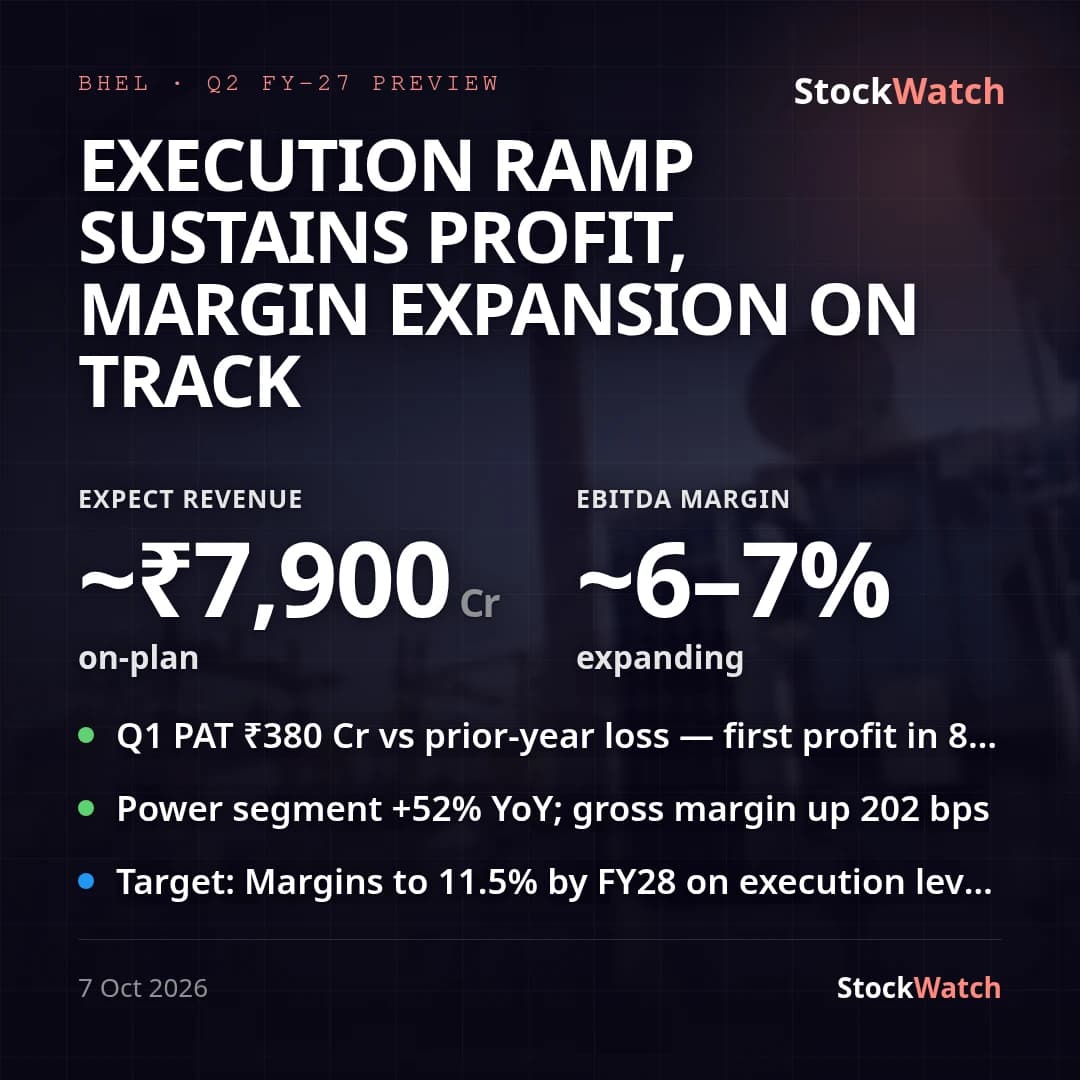
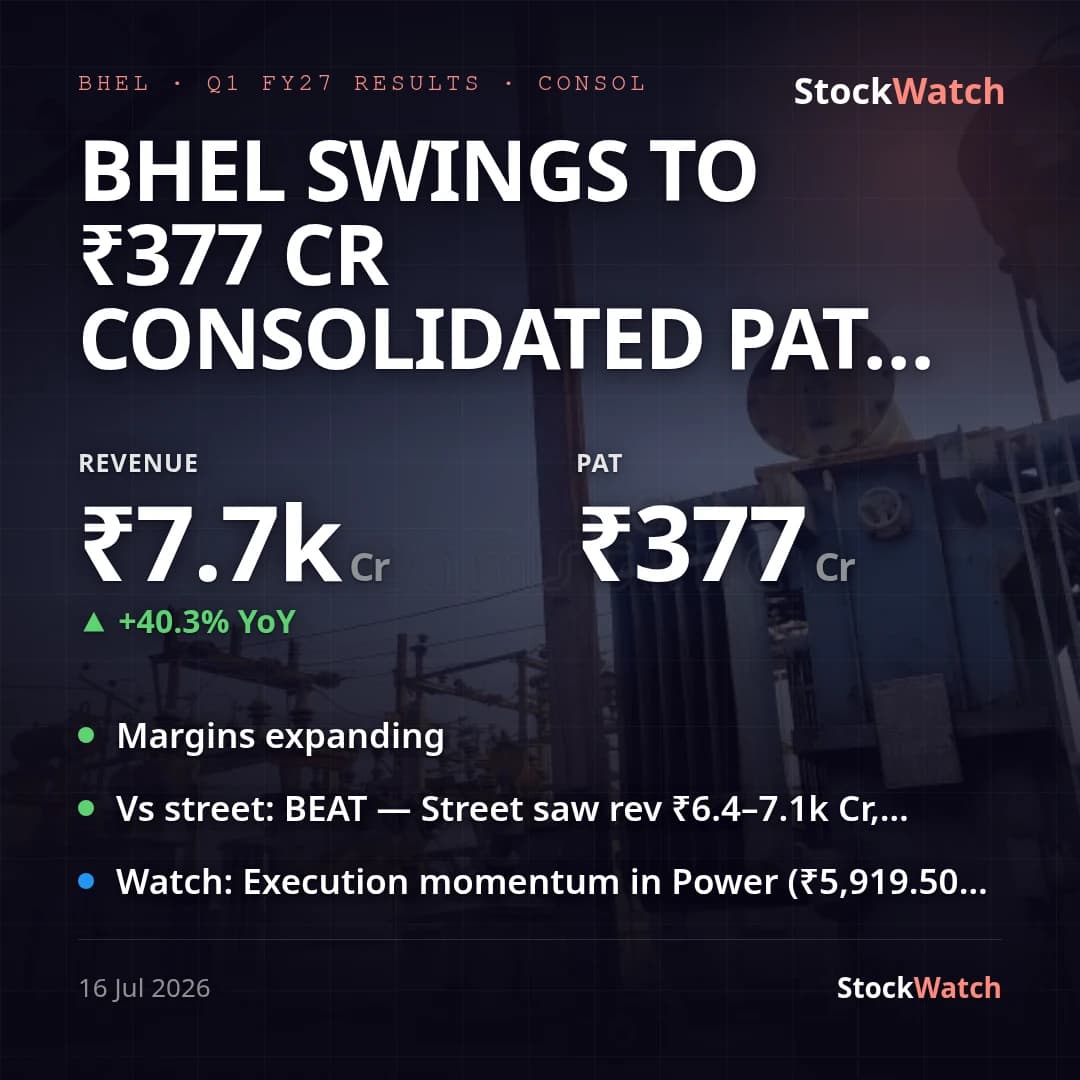
BHEL's consolidated PAT for Q2 FY27 came in at ₹820.94 Cr, up 119% year-on-year from ₹374.89 Cr and up 118% sequentially from ₹376.71 Cr, on revenue of ₹9,300.35 Cr (+23.8% YoY, +20.8% QoQ). The print comfortably cleared the bar set by our pre-result preview — revenue was expected around ₹7,900 Cr and EBITDA margin was pegged at a 6-7% trajectory, while actual operating profit margin landed at 11.23%, already past the top end of that range. BHEL carries no formal management guidance on record for this quarter, so the result is judged against street/internal expectations rather than a company-issued number; nor was any press-release commentary available to cross-check management's own framing of the quarter.
The margin expansion sits on the operating line rather than one-offs: standalone cost of materials & services rose a slower 21.2% YoY to ₹6,958.44 Cr against 23.8% revenue growth, employee costs grew just 11.6% YoY, and finance costs fell 36.2% YoY to ₹124.77 Cr as short-term borrowings were pared down. That operating leverage lifted consolidated net profit ratio to 8.83% from 4.99% a year ago and 4.89% last quarter. No exceptional items were booked in either the current or year-ago period, so the ~119% YoY PAT growth is organic, not one-off-driven. Both reporting segments contributed to the standalone PBT of ₹1,077.75 Cr: Power segment PBT rose to ₹858.37 Cr from ₹593.76 Cr YoY, and Industry segment PBT rose to ₹518.71 Cr from ₹280.04 Cr YoY.
The quarter's corporate actions track the execution narrative the Street has been debating: the Titagarh Rail Systems JV for Vande Bharat maintenance (Sep 15) and the ₹65 Cr equity investment in NTPC-BHEL Power Projects (Sep 14) point to continued order/capacity deployment, while a senior management change (Sep 25) and the RTA transition (Sep 18) are administrative items unconnected to the print. Pre-result, 20-analyst consensus was a split Hold with an average 12-month target of ₹398.75 against bull cases (ICICI Securities ₹520, ICICI Direct ₹575) built on a margin path from 6.5% to 11.5% — this quarter's 11.23% OPM is a data point in the bulls' favour, though the stock's valuation debate itself remains unresolved by one print.
One balance-sheet item flagged by the auditors: trade receivables include an overdue ₹196 Cr (USD 23 Mn) balance from Sudanese customer STPG, held as good despite the ongoing Sudan crisis, with a stated ₹176 Cr hit to PBT (net of ECL) if that classification changes.