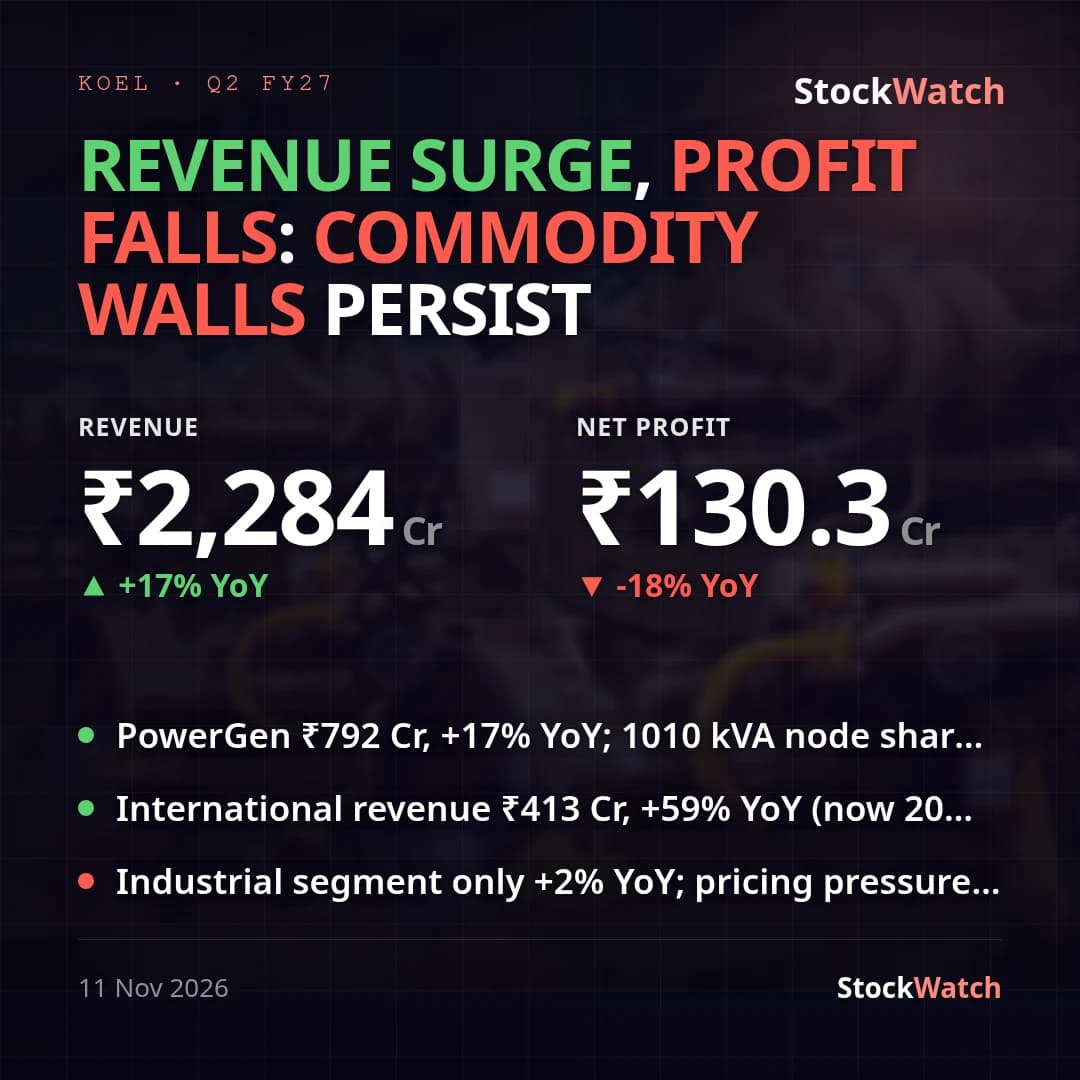
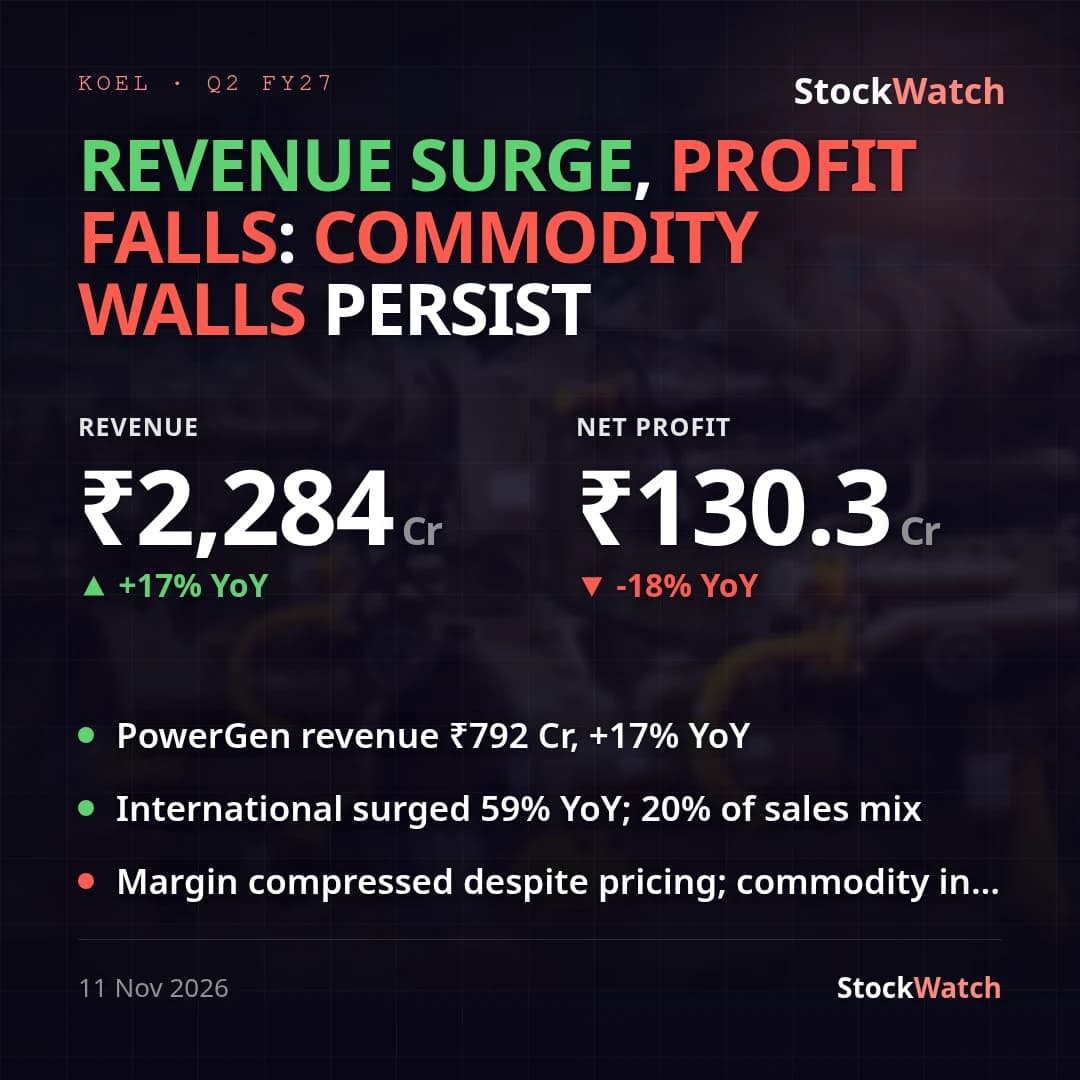
Kirloskar Oil Engines Q2 FY27: PAT falls 18% YoY to ₹130 Cr despite 17% revenue growth
Kirloskar Oil Engines' consolidated revenue rose 17.2% YoY to ₹2,284 Cr (₹1,948 Cr a year ago) and 14.2% sequentially (₹2,000 Cr in Q1 FY27), but consolidated net profit for the period fell 18.1% YoY to ₹130.3 Cr from ₹159.2 Cr, even as it climbed 17.3% QoQ from ₹111.1 Cr. Net margin compressed to 5.68% of total income from 8.12% a year ago (though it ticked up slightly from 5.51% in Q1), and PBT margin fell to 7.65% from 11.02% YoY. Basic EPS was ₹9.04 against ₹11.18 a year ago. On a YoY basis — the primary lens here — this is a weak print: topline growth did not convert to profit growth, and the profit decline cannot be attributed to any one-off, since neither this quarter nor either comparison quarter carried exceptional items.
The drag is concentrated, not broad-based. The Financial Services segment — the company's lending/NBFC arm — saw its segment profit collapse 82% YoY, from ₹33.5 Cr to ₹6.1 Cr, even as the finance cost on that book actually fell (₹115.4 Cr vs ₹130.5 Cr YoY), pointing to margin or asset-quality pressure within the lending business rather than a funding-cost problem. That single segment accounts for roughly 70% of the ₹40 Cr YoY decline in total segment profit. The core Business-to-Business (engines) segment grew revenue a healthy 19.8% YoY to ₹1,745 Cr, but its own segment profit still fell 9.6% YoY to ₹147.6 Cr — margin compression reached the core business too, not just the financial-services arm. B2C was the one bright spot, segment profit up 25.8% YoY to ₹22.9 Cr on a smaller post-transfer revenue base.
No Q2-specific street consensus was found; the most recent read available is Motilal Oswal's post-Q1 note, which cut FY27-29 EPS estimates by 7%/4%/2% citing an EBITDA margin miss, framed the pressure as 'temporary,' and has since raised FY27/28 estimates again (+3%/+10%) expecting recovery via order-delivery timing and operating leverage — a thesis this quarter's modest QoQ margin uptick is only partially consistent with, given margins are still well below year-ago levels. Management's only outlook on record is the FY30 aspiration of ~$2 billion revenue (~₹16,600 Cr) with 'higher double-digit' EBITDA margins, with no formal FY27 numeric target; it had flagged 'pricing actions already implemented' with realization 'staged over coming quarters' — this quarter's YoY margin compression suggests that realization has not yet shown up in the numbers, so guidance reads as missed-so-far rather than met. No company press release accompanying this result was available to cross-check management's own framing of the quarter.
The quarter also carried several corporate-development items consistent with the overseas-expansion leg of the FY30 strategy: a Netherlands subsidiary was incorporated, the KTSPL acquisition was completed via subsidiary KIME, and ₹8.25 Cr was invested toward a South African acquisition — all funded while the financial-services segment's domestic profitability eroded sharply. Separately, the company received a ₹9.9 Cr tax demand notice during the quarter, which does not appear in this quarter's P&L as an exceptional charge.