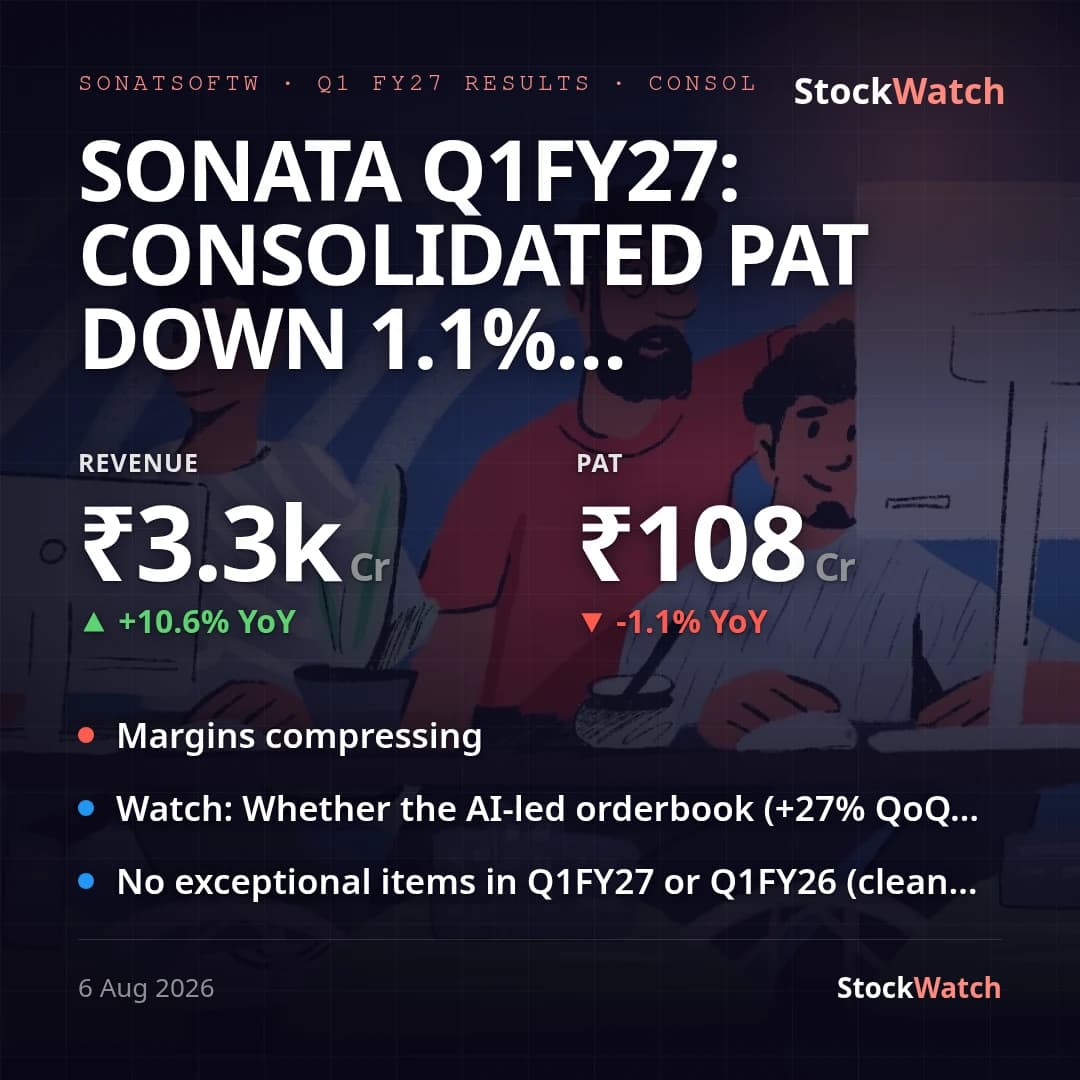
Sonata Software's consolidated (primary basis) revenue rose 10.6% YoY and 29.3% QoQ to ₹3,279.1 Cr, but PAT slipped 1.1% YoY and 17.1% QoQ to ₹108.1 Cr — no exceptional items sat in either this quarter or the year-ago quarter, so the YoY comparison is clean. Net profit margin compressed to 3.30%, down from 3.66% a year ago and 5.07% last quarter, meaning topline growth this quarter did not carry through to the bottom line.
The drag is traceable to two things. First, mix: Domestic Products & Services revenue jumped 42.4% QoQ to ₹2,505.6 Cr, a low-margin trading business — purchase of stock-in-trade alone was ₹2,635.97 Cr of the group's ₹3,148.78 Cr total consolidated expenses (84%) — so a bigger domestic distribution slice dilutes the blended margin even as EBITDA (company's own metric, ex other income/forex/exceptional items) still grew 12.1% YoY to ₹179.0 Cr. Second, forex: consolidated PAT this quarter carries a ₹7.4 Cr forex loss versus a ₹28 Cr forex gain in Q4FY26, a roughly ₹35 Cr adverse swing that falls mostly on International IT Services, whose PAT fell 26.1% QoQ and 12.0% YoY to ₹62.2 Cr despite that segment's EBITDA still rising 3.2% YoY.
No formal sell-side consensus for this specific print turned up in a web search, so vs-street is unknown. Against management's own Q4FY26 guidance — a flat international growth trajectory and stable elevated EBITDA margins driven by AI efficiencies — International IT Services revenue in USD grew just 0.2% YoY (2.1% in constant currency), essentially flat as guided, but that segment's own EBITDA margin compressed roughly 117bps YoY (15.39% vs 16.56%), a mild miss on the 'stable margins' pledge even though blended EBITDA still rose YoY on domestic strength (EBITDA +34.9% YoY there, on 14.5% YoY gross-contribution growth per Sonata Information Technology MD Sujit Mohanty, who cited renewed client contracts at higher values). Standalone (parent-only) PAT actually rose 81.3% YoY to ₹41.1 Cr off a small base — a materially different story from the consolidated print, reflecting the parent's narrower scope versus the group, which carries the larger, margin-diluting domestic distribution subsidiary. The Board also declared an interim dividend of ₹1.25/share (record date August 14, 2026). This is the first full quarter under CEO Rajsekhar Datta Roy, who took charge May 9, 2026 after Samir Dhir's exit, and who flagged a 21% rise in AI-led pipeline and 27% QoQ growth in AI-led orderbook as early traction — neither yet visible in reported margins.
Going into Q2FY27, the questions this quarter sets up are whether the domestic mix normalizes back toward Q4's ~8.2% EBITDA margin from this quarter's ~5.5%, whether the AI-led orderbook growth converts into billed revenue, and whether the adverse forex swing reverses.