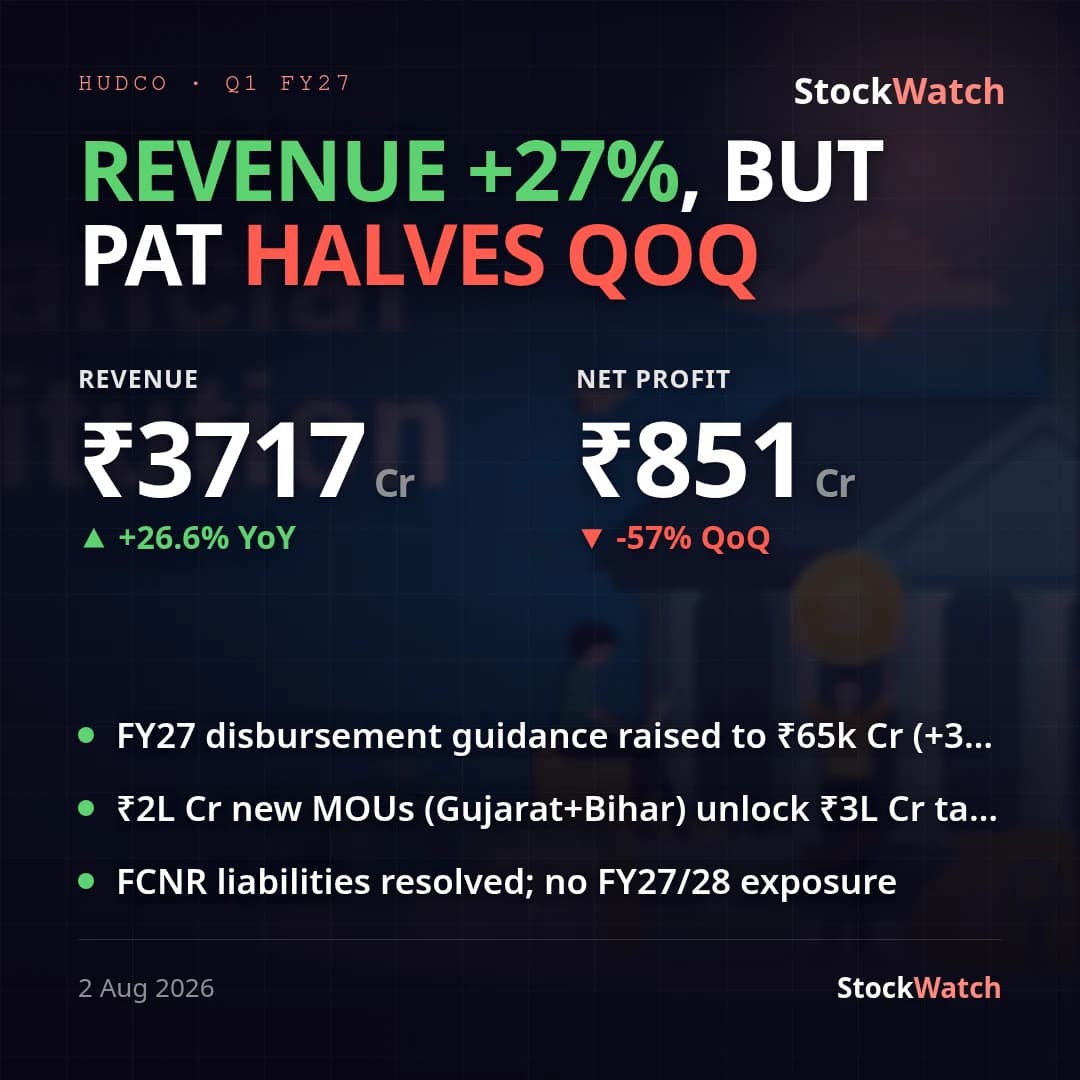
Consolidated PAT for Q2 FY27 (quarter ended September 30, 2026) rose 28.3% YoY to ₹911.04 Cr from ₹709.83 Cr, on revenue from operations of ₹4,040.42 Cr, up 25.5% YoY. Sequentially PAT grew a more modest 7.0% QoQ from ₹851.11 Cr, and revenue 8.7% QoQ from ₹3,717.17 Cr — for an NBFC lender this isn't a seasonality story, so the YoY print is the primary read and shows a straightforward growth quarter rather than a QoQ-driven one. Standalone and consolidated figures are effectively identical (basic EPS ₹4.55 both), since the sole associate, Shristi Urban Infrastructure Development Ltd, is equity-accounted and its share of loss (₹0.03 lakh for the quarter) is immaterial and rounds to ₹0 Cr in the consolidated statement.
Net profit margin expanded YoY to 22.49% from 21.83%, though it eased slightly QoQ from 22.77%. Two factors did the heavy lifting on the YoY margin gain rather than core spread widening: the effective tax rate fell to 18.8% (₹211.42 Cr tax on ₹1,122.46 Cr PBT) from 25.65% a year ago (₹244.88 Cr tax on ₹954.71 Cr PBT), and the company booked a net ECL reversal of ₹44.18 Cr this quarter versus a smaller ₹16.99 Cr reversal a year ago — consistent with continued asset-quality improvement, as the gross credit-impaired assets ratio fell to 0.71% from 1.21% YoY and the net credit-impaired ratio to 0.04% from 0.07%, with provision coverage at 93.76%. PBT itself grew a more modest 17.6% YoY (₹1,122.46 Cr vs ₹954.71 Cr). The company states there were no exceptional or extraordinary items in the half year (note 9), so this is a clean YoY number, not a one-off-boosted one.
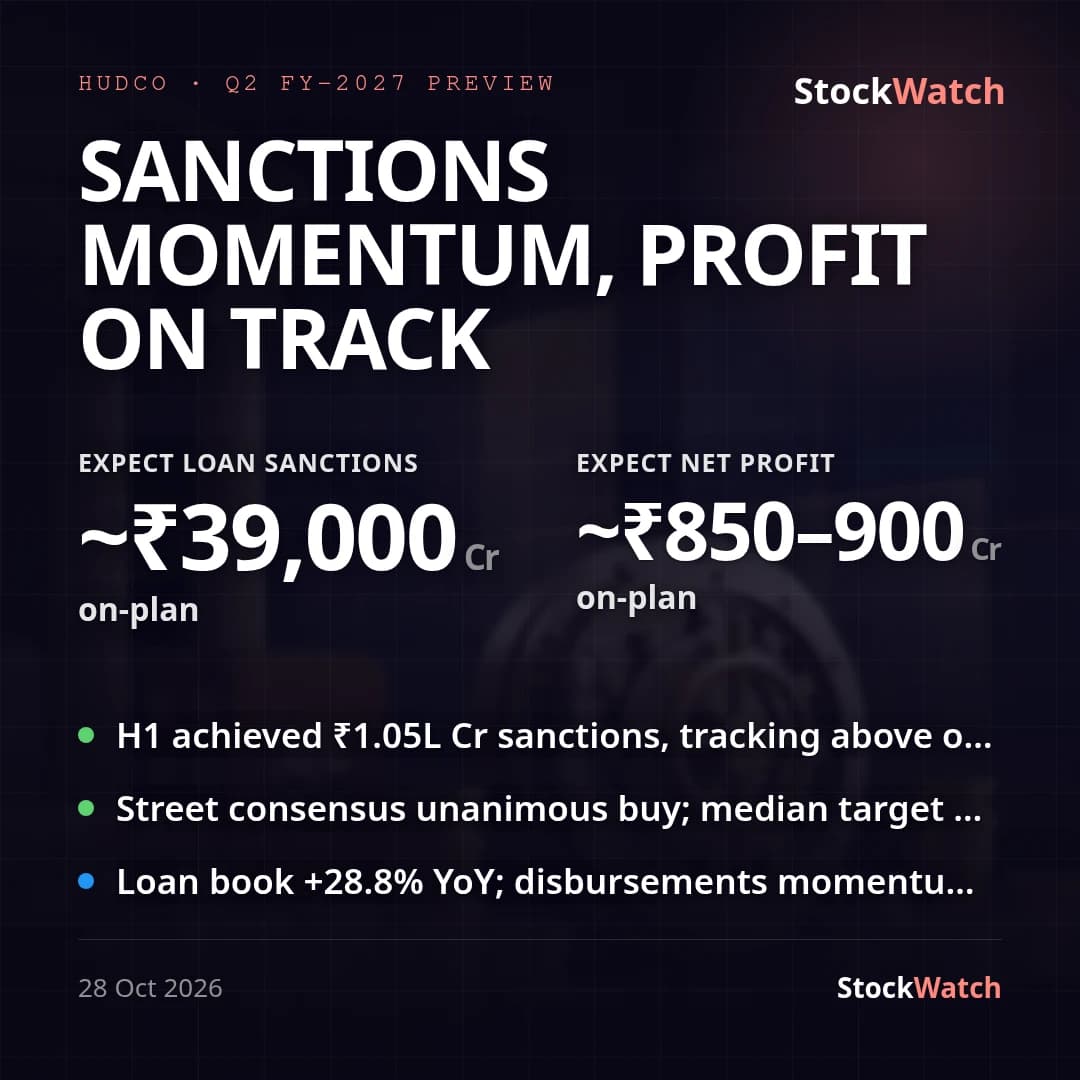
Against management's FY27 guidance from the July 2026 concall (raised full-year disbursement target of ₹65,000 Cr, loan book target of ₹3 lakh Cr by FY2030), HUDCO disbursed ₹35,371 Cr in H1 FY27 against ₹1,04,592 Cr of sanctions — a 54.4% run-rate on the full-year target at the half-year mark, ahead of a straight-line pace and consistent with the confident tone management carried into this quarter. The standalone loan book grew to ₹1,86,502 Cr as of September 30, 2026 from ₹1,60,547 Cr at FY26-end. We found no published Street consensus estimate specific to this Q2 FY27 print in a web search, and no company press release was available in the context for this quarter, so the result cannot be benchmarked against external estimates or management's own framing of the print. Separately, the board declared a 2nd interim dividend of ₹1.35/share (record date November 11, 2026); RBI classified HUDCO under the NBFC Upper Layer in August 2026; and during the quarter the Ministry of Rural Development transferred its 20.73% stake to the Ministry of Housing and Urban Affairs, consolidating the full 75% promoter holding with MoHUA — none of these are P&L items but they bear on capital and regulatory standing. The debt-equity ratio rose to 7.16x from 6.98x YoY on balance-sheet growth, and the ₹743.16 Cr Andrews Ganj Project recoverable from MoHUA (₹7.80 Cr interest accrued this quarter) remains outstanding pending resolution.
Going into H2 FY27, the questions this print sets up are whether the 54.4% H1 disbursement run-rate converts into the full ₹65,000 Cr target, whether the ECL-reversal-aided tax and credit-cost tailwinds that lifted this quarter's margin repeat or normalize, and how the pending Andrews Ganj recovery is eventually resolved.