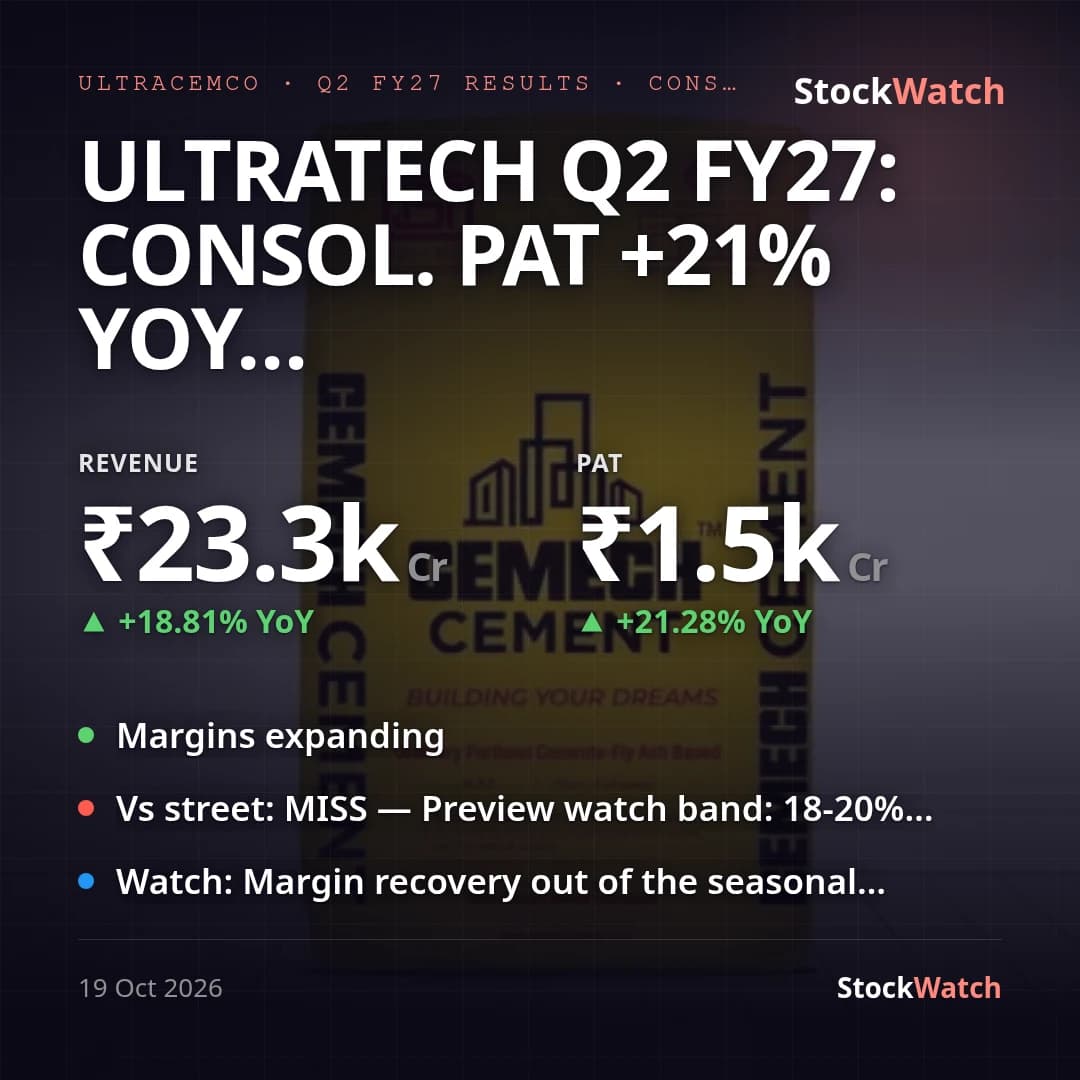
UltraTech Q2 FY27: Consol. PAT +21% YoY to ₹1,501 Cr, Margin Misses 18-20% Watch Band
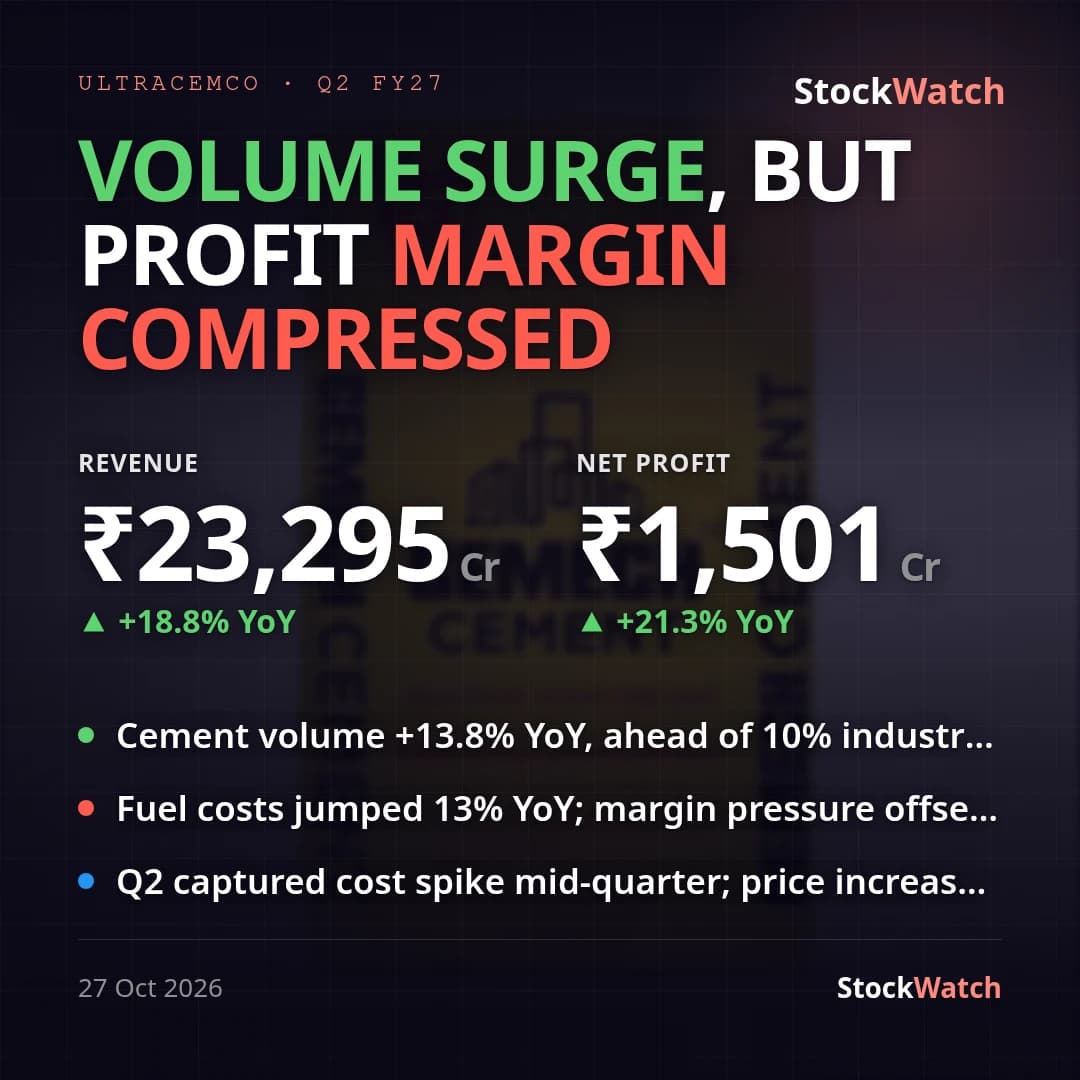
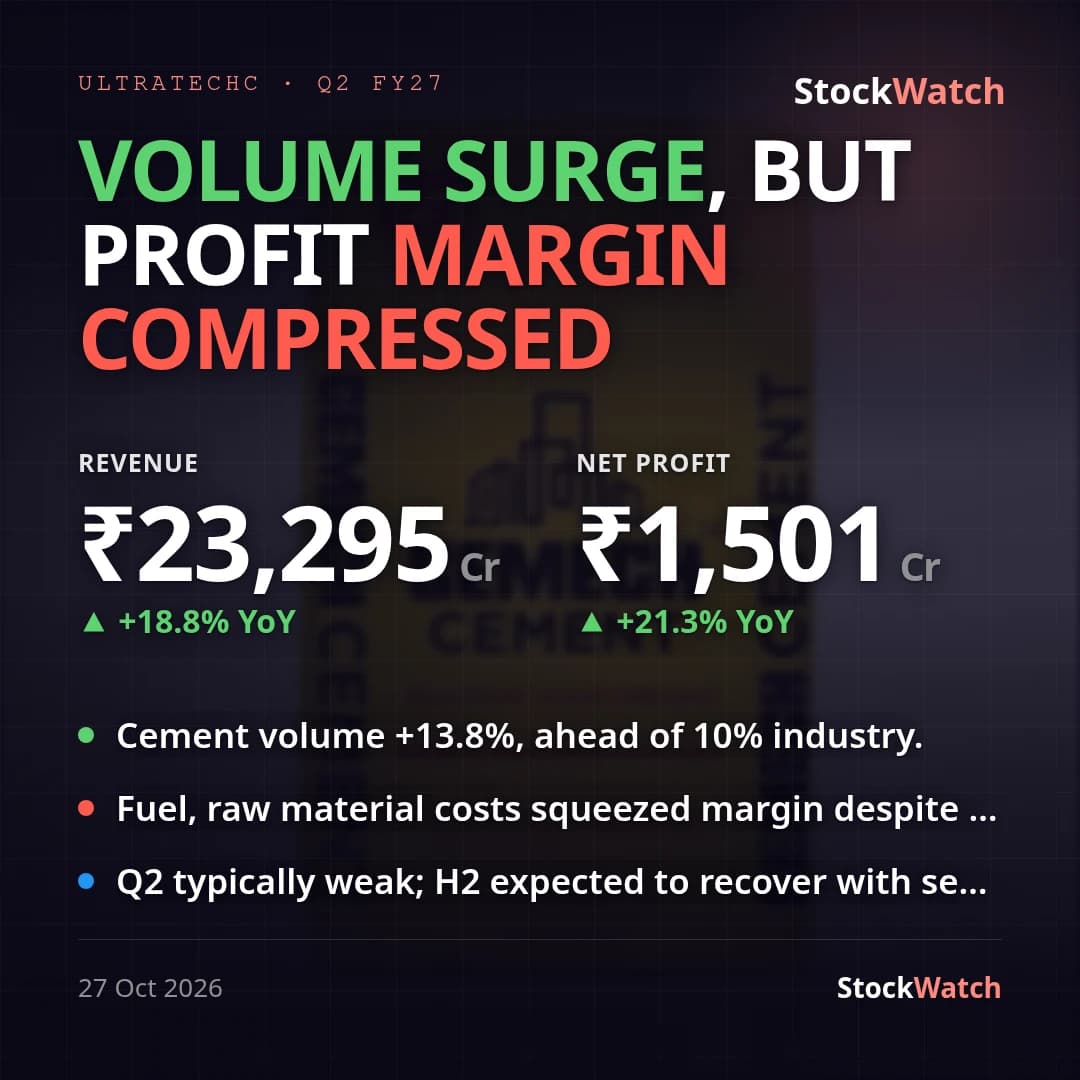
UltraTech's consolidated revenue rose 18.8% YoY to ₹23,295 Cr (from ₹19,607 Cr) and PAT grew 21.3% YoY to ₹1,501 Cr (from ₹1,238 Cr), with EPS at ₹50.78 versus ₹41.87 a year ago. Sequentially both lines fell — revenue -5.5% and PAT -42.3% from Q1 FY27's ₹24,648 Cr / ₹2,604 Cr — but this is a seasonal monsoon-quarter pattern rather than a YoY deterioration, since profit growth continued to outpace revenue growth on a year-on-year basis. Domestic grey cement volumes grew 13.8% YoY to 35.94 MT (from 31.58 MT) and capacity utilisation climbed to 71% from 66%. A ₹6.29 Cr pre-tax exceptional loss (asset sale) this quarter is immaterial — adjusted YoY PAT growth is ~21.6% versus 21.3% reported.
The margin picture is mixed by period: consolidated OPM (~16.5%, on PBIDT of ₹3,832 Cr, +17.3% YoY) expanded from 15.8% a year ago but compressed sharply from 20.3% in Q1 FY27, as power & fuel cost rose 18.7% YoY to ₹5,511 Cr and freight climbed to ₹4,810 Cr — exactly the cost-inflation pressure our pre-result preview flagged as the key watch item. NPM similarly ticked up to ~6.4% YoY (from 6.3%) but fell from 10.5% QoQ. Management's own press release framed the quarter as reflecting 'the stability of UltraTech's earnings, with revenue, operating profit and net profit all growing by double digits' — a framing the YoY numbers support, though it understates the sequential margin squeeze.
Against our pre-result preview's Street read (Buy consensus, 86% buy-rated, median target ₹13,950, betting on pricing power holding an 18-20% EBITDA margin), the actual ~16.5% consolidated OPM falls short of that band — a miss on the quarter's key watch item even as volume growth (13.8% YoY) comfortably cleared expectations. Against management's own FY27 guidance from the July 2026 concall — double-digit domestic volume growth (Q1 at 13.1%), a 240+ mtpa capacity target by March 2028 backed by ₹17,000 Cr capex, and Net Debt/EBITDA <1x — this quarter's 13.8% volume growth and the commissioning of 3.6 mtpa greenfield capacity at Petnikota (AP) plus 1.0 mtpa of debottlenecking (global grey capacity now 210.1 mtpa) both track the plan. Debt-equity rose to 0.37x from 0.27x QoQ as the capex programme continues; the <1x Net Debt/EBITDA target could not be independently verified from the disclosed figures. Standalone PAT grew faster YoY (+25.2% to ₹1,332 Cr) than consolidated (+21.3%), a gap above 3 points that traces to minority interest (₹7.6 Cr) and the JV/associate loss (₹2.2 Cr) at the group level.
The quarter also saw UltraTech launch Ultravolt, its wires & cables business — a new Building Solutions category built around a Jhagadia, Gujarat facility sized for 78,000 MT of copper and 24,000 MT of aluminium consumption, positioned as the second-largest player by planned housing-wires capacity. Board composition changes effective January 1, 2027 were announced this quarter with no disclosed P&L impact. Heading into Q3 FY27, the open question is whether margin recovers out of the seasonal trough as cost inflation on power, fuel and freight eases.